By Josh Tagg, mortgage broker · Mortgages for Less with INDI Mortgage · Calgary, serving all of Alberta ·
Buying your first home is exciting, but it can also be overwhelming. The process involves many moving parts, from saving for a down payment to securing the right mortgage and understanding the housing market. Planning ahead and getting the right professional guidance can make a huge difference. Here are the top five things every first-time homebuyer in Alberta should consider in 2026.
Open an FHSA. Start saving for your down payment in a tax-free account.
Consider an RRSP transfer. Move retirement savings into your FHSA without paying them back.
Review your credit early. Leave time to fix errors, high usage or old debts.
Find a realtor. Learn the neighbourhoods and get listings as soon as they hit the market.
Hold off on big financial changes. A new car or a job switch can affect your approval.
1. Why should you open a First Home Savings Account (FHSA)?
If you haven’t opened a First Home Savings Account (FHSA) yet, now is the perfect time. This account is designed specifically for first-time buyers, allowing you to save money for your home in a tax-advantaged way. Contributions grow tax-free, and withdrawals for your first home are also tax-free. Even small contributions made early can add up over time, giving you a head start on your down payment.
2. Should you transfer funds from your RRSP?
Another strategy to boost your savings is transferring money from your Registered Retirement Savings Plan (RRSP) into your FHSA. This allows you to move funds you’ve already been saving for retirement into your first home account without having to pay them back. It’s a smart way to make your existing savings work harder and reach your homeownership goals faster. A mortgage broker like Josh Tagg can help you understand exactly how this works and what the best approach is for your situation.
3. Why do a credit review early?
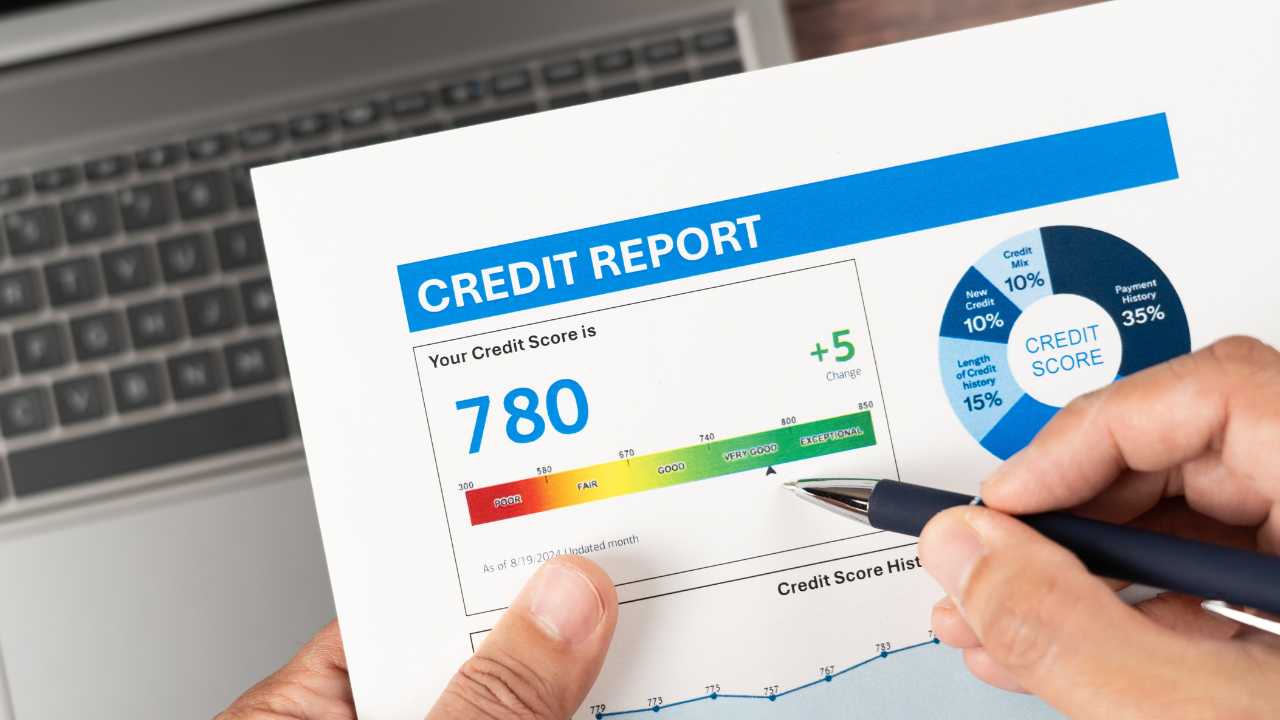
Your credit score plays a major role in the mortgage you can qualify for, and even small issues can affect your approval. That’s why it’s important to do a credit review with a qualified mortgage broker well before you start house hunting. If there are any surprises—like errors on your report, high credit usage, or old debts—you’ll have time to address them. Josh Tagg can provide a detailed review, help you understand your credit health, and offer guidance on improving it if needed. Taking this step early can save time, money, and stress down the road.
4. Why build a relationship with a realtor before you buy?
Having a trusted realtor in your corner can make a huge difference. Someone like Jay Lewis can guide you through the different neighbourhoods in Alberta, help you understand local market trends, and set you up to receive listings as soon as they hit the market. This gives you a competitive advantage, especially in fast-moving areas like Calgary or Edmonton. By building this relationship early, you can start learning what works best for you, your lifestyle, and your budget before you make an offer on a home.
5. Which financial changes should you avoid before buying?
Finally, be mindful of your finances leading up to your purchase. Large purchases, like a new car, or major life changes, such as switching jobs, can impact your mortgage approval. Even small shifts in income or debt can affect how much a lender is willing to lend. That’s why it’s critical to talk to a mortgage broker like me before making big financial decisions. I can help you understand what’s safe to do and what could potentially delay or complicate your home purchase.
How does professional guidance help first-time buyers?
Buying your first home is a big step, but you don’t have to do it alone. Working with a knowledgeable mortgage broker like me, Josh Tagg, ensures you’re taking the right steps at the right time. From understanding your savings options to reviewing your credit, exploring mortgage programs, and planning your financial moves, I can guide you through every stage of the homebuying process.
Starting your planning early, staying organized, and getting professional advice can put you in the strongest position to buy your first home in Alberta in 2026. With the right preparation, you’ll be able to focus on the exciting parts of homeownership—like finding the perfect space to call your own—without unnecessary stress or surprises. Contact me today to get started!
How an Alberta mortgage broker helps first-time buyers
The earlier you start, the more options you have when you find the right home:
- We run a credit review well before you shop, so surprises can be fixed in time.
- We help you plan how your FHSA and RRSP savings fit into your down payment.
- We tell you which financial moves are safe before you buy, and which could delay approval.
- We arrange a pre-approval so you know your budget before you make an offer.
- We work with first-time buyers across Calgary, Edmonton and all of Alberta.
Buying your first home in Alberta?
Let’s review your credit and savings and build a plan before you start house hunting.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageFirst-time homebuyer planning: common questions
What should first-time buyers in Alberta do before buying a home?
What is a First Home Savings Account (FHSA)?
Can you move RRSP money into an FHSA?
When should you check your credit before buying a home?
Why does a realtor help first-time buyers?
Can buying a new car affect your mortgage approval?
This article is general information for first-time homebuyers in Alberta, not financial, mortgage, tax or legal advice. It was written in November 2025; FHSA and RRSP rules, lender policies and market conditions can change. Any mortgage is subject to lender approval. Please speak with a licensed mortgage professional, and a tax professional for FHSA and RRSP questions, about your specific situation. Mortgages for Less with INDI Mortgage.