If you are buying a home or renewing your mortgage in Alberta, you have probably heard about the mortgage stress test. Many people assume the stress test is something new or something that only affects first-time buyers. That is not true. The mortgage stress test has been around for several years, and it plays a major role in how much you can qualify for.
As an Alberta mortgage broker, here’s what I want you to know.
What is the mortgage stress test?
The mortgage stress test is a federal rule that requires lenders to check whether you could still afford your mortgage if interest rates rise. Even if your actual mortgage rate is lower, you must qualify at a higher “stress test” rate.
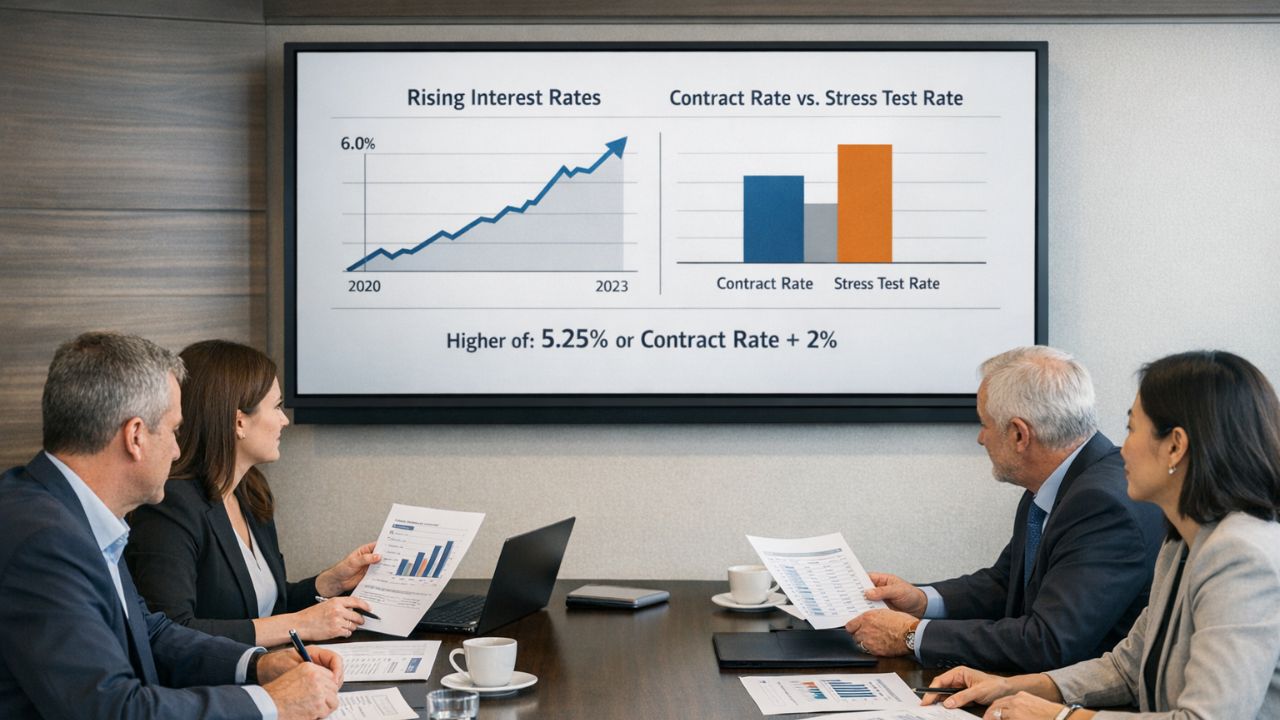
Right now, most borrowers must qualify at the higher of:
- 5.25%
- Or your contract rate plus 2%
So if you are offered a rate of 5.00%, you may need to qualify as if your rate were 7.00%. This does not mean you will pay 7.00%, it simply means the lender must confirm that your income can support the higher payment amount.
Why does the stress test exist?
The mortgage stress test was introduced by the federal government and is overseen by the Office of the Superintendent of Financial Institutions (OSFI).
The goal is simple: protect Canadians if interest rates rise.
We have seen in recent years how quickly rates can move. The stress test is designed to reduce the risk of homeowners falling behind on payments if rates increase in the future. It is meant to protect both borrowers and the overall financial system.
How does the mortgage stress test affect Alberta homebuyers?
In Alberta, housing is often more affordable than in some other provinces. But the stress test still reduces how much you can borrow. In many cases, the stress test lowers your maximum purchase price by tens of thousands of dollars.
For example, if your income supports a $500,000 home at your contract rate, the stress test might reduce your approval to something closer to $450,000 or less.
For first-time homebuyers, this can mean:
- Needing a larger down payment
- Looking at a lower price range
- Choosing a different neighbourhood
- Buying a condo instead of a detached home
This is why getting pre-approved early is important. It allows you to understand your real budget before you start shopping.
Does the stress test apply at renewal?
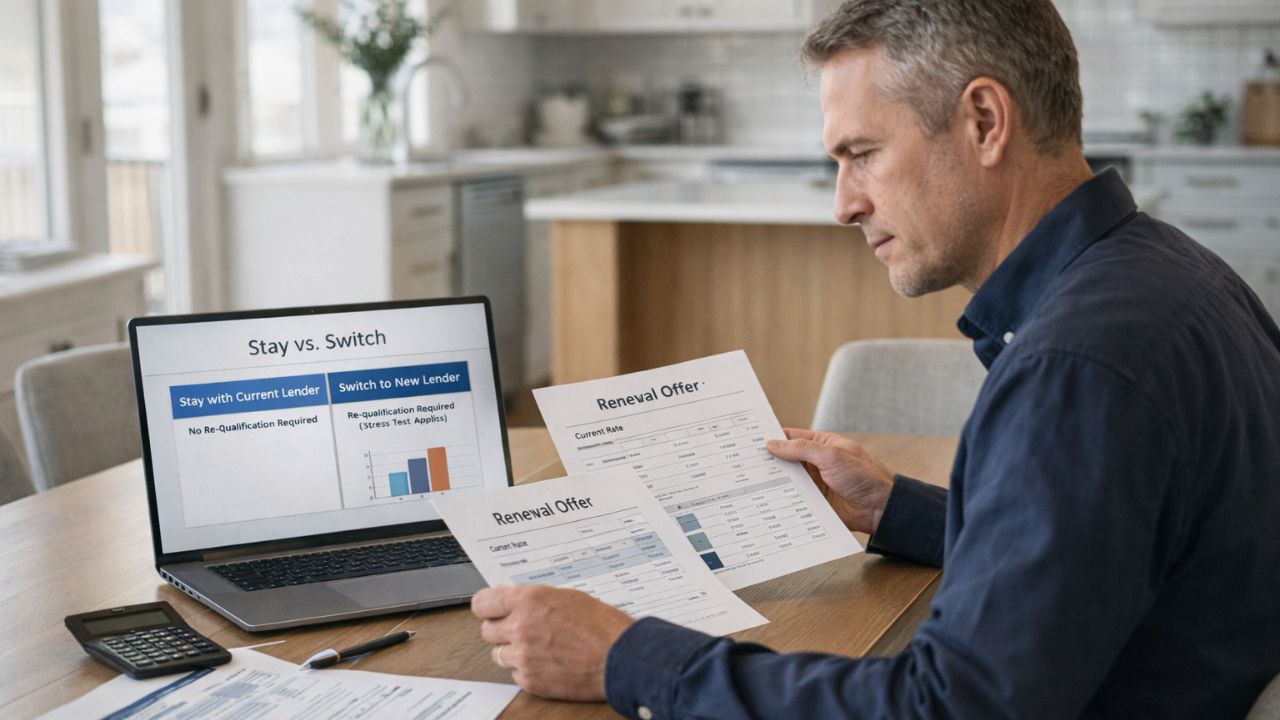
If you stay with your current lender at renewal, you typically do not have to re-qualify under the stress test.
However, if you want to switch lenders to get a better rate, you may need to re-qualify. In that case, the stress test could apply again.
That is one reason I always review renewal options early with my clients. Sometimes staying put makes sense. Other times, even with the stress test, switching lenders can still save you money.
How does the stress test work for self-employed borrowers?
If you are self-employed in Alberta, the stress test can feel even more challenging. Because lenders often use your two-year average income, any drop in reported income can reduce your borrowing power before the stress test is even applied. This is where proper planning becomes very important. Structuring your income and tax filings strategically can make a major difference in how you qualify.
Can you avoid the mortgage stress test?
In most traditional lending situations, no. All federally regulated lenders must follow stress test rules. That includes major banks and many mortgage lenders.
Some alternative or private lending options may not use the same stress test formula, but those solutions always come with higher interest rates or fees. They are not for everyone, and they should be reviewed carefully.
My job as your Alberta mortgage broker is to explore every reasonable option and explain the pros and cons clearly.
How can you prepare for the mortgage stress test?
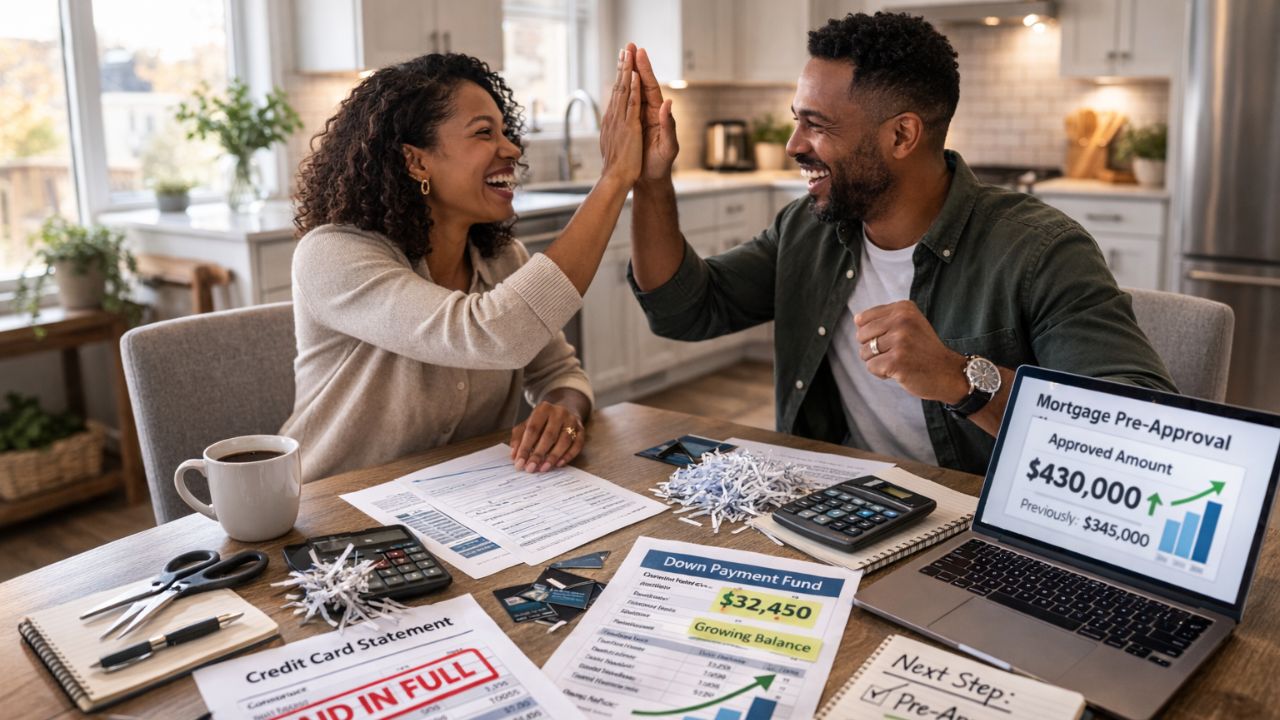
If you are planning to buy a home in Alberta, here are practical steps that help:
- Increase your down payment if possible
- Pay down high-interest debt
- Avoid taking on new loans before applying
- Keep your credit score strong
- Get pre-approved early
Even small improvements in your debt levels or income can increase your approval amount under the stress test calculation.
What is my advice as an Alberta mortgage broker?
The mortgage stress test is not meant to stop you from buying a home. It is meant to make sure you buy a home you can realistically afford over the next few years. That said, it can feel frustrating when the numbers do not match what you expected.
This is why working with an experienced Alberta mortgage broker makes a difference. I run the numbers before you make an offer. I explain your options clearly. And I help you structure your application properly so there are no surprises.
If you are thinking about buying, renewing, or refinancing in Alberta, let’s talk through your situation. The mortgage stress test does not have to be confusing. With the right plan, you can move forward confidently.
How an Alberta mortgage broker helps you pass the stress test
The stress test is the same rule at every federally regulated lender — but how your file is put together is not. Here’s where we come in:
- We run your numbers at the qualifying rate before you shop, so your budget is real from day one.
- We show you which debts to pay down first to get the biggest lift in your approval amount.
- At renewal, we check whether you can switch lenders without re-qualifying and still get a better rate.
- For self-employed borrowers, we present your income the way lenders read it and plan your filings ahead of time.
- When a bank says no, we weigh alternative and private options honestly — including the extra cost.
- We work with buyers and homeowners across Calgary, Edmonton and all of Alberta.
Know your real budget before you make an offer
Get pre-approved at the stress-test rate, or have us review your renewal options before you sign.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageMortgage stress test questions
What rate do I have to qualify at under the mortgage stress test?
How much does the stress test reduce what I can borrow in Alberta?
Who sets the mortgage stress test?
Do I have to pass the stress test when I renew my mortgage?
Is the stress test harder for self-employed borrowers?
Can I avoid the mortgage stress test?
How can I qualify for more under the stress test?
This article is general information for Alberta homebuyers and homeowners, not financial, mortgage, tax or legal advice. Qualifying rules, including the minimum qualifying rate and renewal switch rules, are set by federal regulators and can change. Any mortgage is subject to lender approval. Please speak with a licensed mortgage professional about your specific situation. Mortgages for Less with INDI Mortgage.