I have been helping Alberta homebuyers for years, and one trend is becoming impossible to ignore: first-time buyers are getting older.
A recent global study ranked Canadian cities among the hardest in the world for young people to buy their first home. In Vancouver, the typical first-time buyer is now 46. In Toronto, it is 40. In Montreal, 39. Even in the United States, the median age for first-time buyers has climbed to 40. That tells us something. The challenge is not just interest rates. It is the down payment.
While Alberta is more affordable than Vancouver or Toronto, we are not immune to this shift. Many first-time buyers in Calgary, Edmonton, Red Deer, and surrounding communities are waiting longer than previous generations did.
Here is why.
Why is the down payment the real barrier for first-time buyers?
We often talk about mortgage rates and monthly payments. Those matter. But the biggest obstacle for most buyers is saving the deposit. Some global research looked at how long it takes the average income earner to save a 15–25% down payment if they start saving at age 23. In Canada’s largest cities, it can take decades.
Even though Alberta home prices are lower than in British Columbia or Ontario, the down payment hurdle is still real. Rent, groceries, transportation, and student loans all compete for the same dollars.
I regularly meet clients who can comfortably handle a mortgage payment that is similar to their rent. But they feel stuck because building the down payment takes time. That is why buyers are older. It is not always about qualification. It is about accumulation.
Is monthly mortgage affordability improving?
There is some good news.
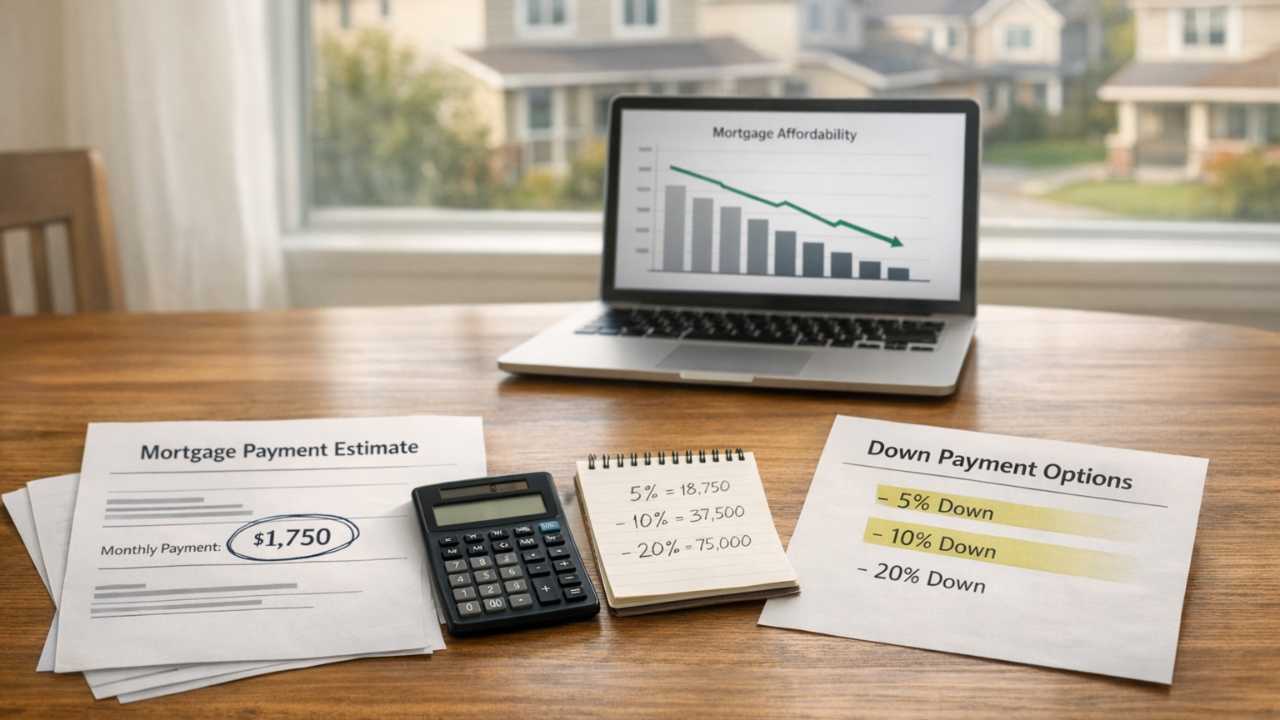
National affordability measures show that borrowing conditions have improved over the past two years. As rates have stabilized and prices cooled in some markets, monthly affordability has become more manageable.
But here is the key detail most headlines miss: those measures assume a 20% down payment. Most first-time buyers in Alberta are not putting down 20%. Many are using 5% or 10%, which is completely normal and often smart.
So while monthly affordability is improving, the savings hurdle has not magically disappeared.
Is Alberta a better place for first-time buyers?
Compared to Vancouver or Toronto, Alberta still offers real opportunity. We have:
- Lower average home prices
- Strong interprovincial migration
- Diverse employment sectors
- Ongoing housing development in many communities
In my experience as an Alberta mortgage broker, buyers here still have options. Detached homes, townhomes, and condos remain accessible at price points that would be impossible in other provinces. That does not mean it is easy. But it does mean it is achievable with a plan.
Which government changes are helping first-time buyers?
Recent policy changes are designed to ease some pressure. We now have:
- 30-year amortizations available for certain first-time buyers on new builds
- GST reductions on eligible new homes
- Continued efforts to increase housing supply
- Adjustments to immigration levels to help balance demand
These changes do not solve everything overnight, but they do create more flexibility. Longer amortizations, for example, can reduce monthly payments and improve qualification. That can help buyers enter the market sooner instead of waiting years to save a larger down payment.
What does this mean for first-time buyers in Alberta?
If you are in your 20s or 30s and feel behind, you are not. Globally, buyers are entering the market later. Canada is simply at the front edge of that trend. The key is not to compare yourself to your parents’ timeline, but to build a strategy based on today’s reality.
That strategy might include:
- Starting with 5% down instead of waiting for 20%
- Buying a condo or townhome first instead of a detached house
- Using gifted down payment options
- Exploring new construction incentives
- Creating a structured savings plan with a clear purchase target
When we run real numbers together, many clients are surprised at how close they actually are.
My advice as an Alberta mortgage broker
The worst thing you can do is assume you are years away and not ask. I regularly meet people who believed they needed $100,000 saved when they actually needed far less to get started. Yes, affordability is a challenge in Canada. Yes, buyers are older. But Alberta still offers one of the strongest paths to homeownership in the country.
If you are serious about buying in the next one to three years, the smartest move is not waiting. It is building a plan now. As your Alberta mortgage broker, my job is to show you what is possible, map out your options, and help you move forward with confidence.
If you are wondering where you stand, let’s run the numbers and create a strategy that works for you. Contact me to get started.
How an Alberta mortgage broker helps first-time buyers get in sooner
The gap between renting and owning is usually the down payment, not the payment. Here’s where we come in:
- We work out the real minimum down payment for the price range you’re looking at — often far less than buyers assume.
- We show you what 5% or 10% down does to your payment and your mortgage default insurance premium, side by side.
- We handle gifted down payment files properly — the gift letter and the paper trail lenders ask for.
- We check whether a 30-year amortization is available on your purchase and what it does to your qualification.
- We build a savings target and timeline so “someday” becomes a date you can plan around.
- We work with first-time buyers across Calgary, Edmonton, Red Deer and all of Alberta.
Find out how close you actually are
Let’s run your real numbers and build a plan to buy your first Alberta home — sooner than you think.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageAlberta first-time buyer questions
Why are first-time home buyers getting older?
How old is the typical first-time home buyer in Canada?
Do I need 20% down to buy my first home in Alberta?
Is it easier to buy a first home in Alberta than in Vancouver or Toronto?
Can first-time buyers get a 30-year amortization?
How can I buy my first home sooner?
How much do I really need saved to buy a home?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. Minimum down payments, amortization limits, mortgage default insurance premiums, GST rebates and government housing programs have eligibility rules and can change — confirm the details for your purchase. Any mortgage is subject to lender and insurer approval. Please speak with a licensed mortgage professional about your specific situation. Mortgages for Less with INDI Mortgage.