The economy and what it might mean for Alberta has always been a concern for those in the housing market. Between the recent news that Canada’s economy shrank in the fourth quarter and that Alberta’s deficit is set to more than double due to lower oil prices, it’s understandable that homebuyers and homeowners want an update. Here’s what I want you to know so you can make confident decisions.
What is happening with the Canadian economy?
Today Statistics Canada reported that the national economy shrank by 0.6 per cent in the fourth quarter of 2025. This doesn’t mean the economy collapsed. It mostly reflects businesses selling off inventory rather than producing more goods. Consumer spending and exports still showed positive movement. But overall, growth slowed. Lower economic activity can shape consumer confidence, hiring, and spending habits — and this affects housing demand.
A slower economy usually means people are more cautious about big financial decisions. For some homebuyers, that could translate to waiting longer to buy. For current homeowners, it could mean slower increases in home values compared to more robust economic periods.
Why is Alberta’s deficit growing in the 2026–27 budget?
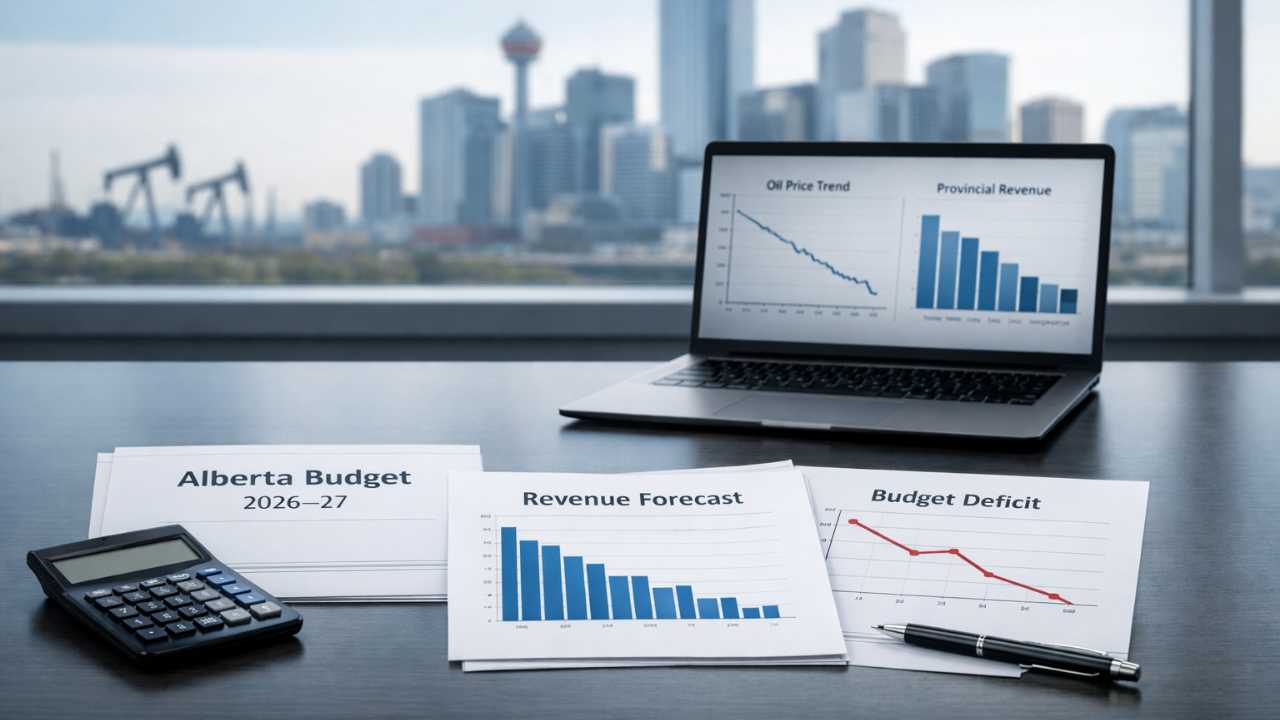
Alberta’s provincial budget for 2026–27 is forecasting a much larger deficit than last year, mostly because oil prices have dropped. Alberta’s government earns a significant portion of its revenue from oil royalties, so when oil prices fall, government income falls too. A larger deficit doesn’t directly change mortgage rates or home prices, but it does reflect broader economic pressures.
A weaker oil sector can slow job growth within energy and related industries. If fewer people are moving to Alberta for work and job growth softens, demand for housing slows too. When demand slows and supply stays steady or grows, that puts downward pressure on price increases.
How could a slowing economy affect housing demand in Alberta?
Housing demand is influenced by jobs, income, migration, confidence, and interest rates. So here’s how slowing economic growth and a bigger provincial deficit could play out:
- Job growth may slow if the economy and oil sector aren’t as strong.
- Fewer newcomers and interprovincial migrants might choose Alberta if opportunities are less attractive compared to other provinces.
- Buyers could become more cautious about taking on big purchases like homes.
When demand softens, we tend to see longer listing times, fewer bidding wars, and more negotiating room for buyers. Rather than fast price increases, we may see more balanced markets in many areas.
Will Alberta home prices drop?
A slower economy and weaker oil prices often don’t cause home prices to crash. Instead, they slow the pace of price growth. In Alberta, we’ve seen strong migration and demand over the past few years which supported price gains. If that slows, prices may stabilise or grow more slowly.
The impact can vary by city and neighbourhood. More affordable areas where first-time buyers are active may stay resilient. Luxury and higher-priced segments could see more softness first. The key takeaway is that markets tend to balance rather than swing wildly in one direction.
| Pressure | What it can do | What it usually doesn’t do |
|---|---|---|
| National economy shrank 0.6% in Q4 2025 | Makes buyers more cautious; slows home-value growth | Signal a collapse — it mostly reflects inventory sell-off |
| Larger Alberta deficit from lower oil prices | Slows energy job growth and in-migration, softening demand | Directly change mortgage rates or home prices |
| Softer demand with steady supply | Longer listing times, fewer bidding wars, more negotiating room | Cause prices to crash — markets tend to balance |
Does Alberta’s deficit affect mortgage rates?
It’s also important to remember that mortgage rates are set by national and global forces — especially the Bank of Canada’s policy decisions, inflation trends, and financial markets. Alberta’s provincial finances do not directly determine mortgage rates.
If the national economy continues to slow, that could eventually influence rate decisions and borrowing costs. But rates don’t move based solely on headlines.
What should Alberta buyers and homeowners do now?
If you’re a buyer in Alberta, this environment could work to your advantage. Increased inventory and less competition for offers may give you more choice and time to make smart decisions. You may also have more negotiating power.
If you’re a homeowner preparing for a mortgage renewal, slower price growth doesn’t mean you’re at risk. Housing markets go through cycles. Long-term ownership still benefits from steady demand, population growth, and the fundamental need for housing.
If you’re thinking about buying, selling, or renewing a mortgage, now is a good time to talk through your goals and options. Your situation is unique — and having a mortgage strategy that fits your income, timeline and comfort level matters more than reacting to headlines.
I’m here to help translate what’s happening in the economy into meaningful advice you can act on.
How an Alberta mortgage broker helps in a slowing economy
Headlines about GDP and deficits don’t tell you what to do with your own mortgage. Here’s where we come in:
- We turn the economic news into your numbers — what you qualify for today, and what your payment looks like.
- For buyers, we get you pre-approved and ready to negotiate when listings sit longer and bidding wars thin out.
- For homeowners, we shop your renewal across lenders instead of taking the first offer in the mail.
- We help you weigh fixed against variable based on your comfort level, not the latest headline.
- If you work in energy or a related industry, we structure the file around your income the way lenders will actually read it.
- We work with buyers and homeowners across Calgary, Edmonton and all of Alberta.
Make your plan on your numbers, not the headlines
Buying, selling or renewing? Let’s map out a mortgage strategy that fits your income, timeline and comfort level.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageAlberta economy and home price questions
Will Alberta’s deficit cause home prices to fall?
How much did Canada’s economy shrink in the fourth quarter of 2025?
Why is Alberta’s deficit getting bigger?
Does Alberta’s budget affect mortgage rates?
Which parts of the Alberta market could soften first?
Is a slowing economy a good time to buy a home in Alberta?
Should I worry about my mortgage renewal if prices grow more slowly?
This article is general information for Alberta homebuyers and homeowners, not financial, mortgage, tax or legal advice. Economic data, provincial budget forecasts, housing market conditions and mortgage rates change over time and vary by city and neighbourhood. Any mortgage is subject to lender approval. Please speak with a licensed mortgage professional about your specific situation. Mortgages for Less with INDI Mortgage.