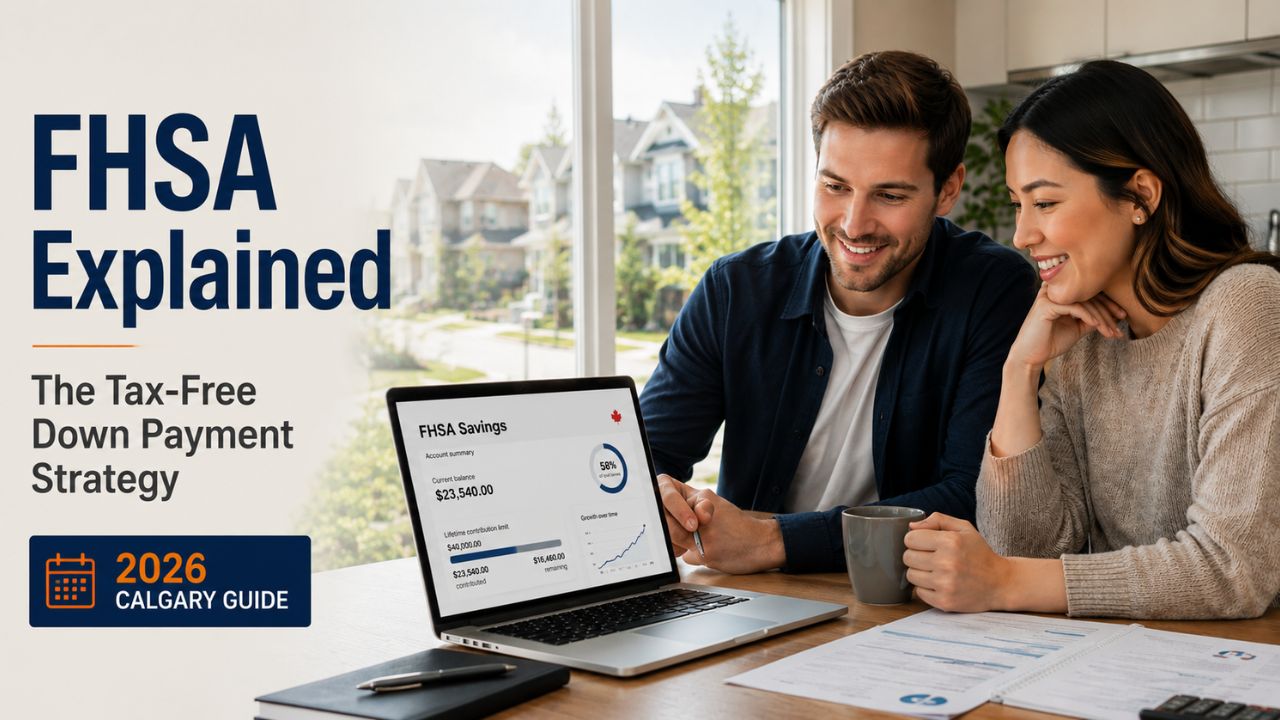
Buying your first home in Alberta can feel overwhelming, especially when you’re trying to save for a down payment while balancing rising living costs and higher mortgage rates. A lot of buyers still don’t fully understand how powerful the First Home Savings Account (FHSA) can be.
In many cases, it’s one of the best tax advantages available to first-time homebuyers in Canada. You can receive a tax deduction when you contribute, grow your savings tax-free, and withdraw the money tax-free when you buy your first home.
If you’re planning to buy your first home in the next few years, understanding how the FHSA works could help you get there faster.
What Is a First Home Savings Account (FHSA)?
The First Home Savings Account is a registered savings account created specifically for Canadians buying their first home. It combines some of the biggest advantages of both an RRSP and a TFSA.
Like an RRSP:
- Your contributions are tax deductible
Like a TFSA:
- Your investments grow tax-free
- Qualified withdrawals are tax-free when used to buy your first home
That combination makes the FHSA one of the most powerful savings tools available for first-time homebuyers in Canada.
What’s Changed With the FHSA in 2026?
The FHSA remains one of the best savings tools available for Canadian first-time homebuyers in 2026. Here are a few important reminders:
- The annual contribution limit remains $8,000 per year
- The lifetime contribution limit remains $40,000
- Unused contribution room can still carry forward
- Buyers can still combine the FHSA with the Home Buyers’ Plan (HBP)
For Edmonton buyers, the FHSA can be especially valuable because home prices here are still more affordable than many major Canadian cities. That means your FHSA savings can often go further toward a meaningful down payment.
I’m also seeing more buyers use the FHSA alongside gifted down payments, co-signers, or longer savings timelines as affordability remains a challenge for many first-time buyers.
Who Can Open an FHSA?
To open an FHSA, you must:
- Be a Canadian resident
- Be at least 18 years old
- Be considered a first-time homebuyer
Generally, that means you cannot have owned a home that you lived in during the current calendar year or the previous four calendar years. If you’re unsure whether you qualify, it’s a good idea to speak with a mortgage broker or accountant before opening the account.
How Much Can You Contribute?
You can contribute up to $8,000 per year to your FHSA, with a maximum lifetime contribution limit of $40,000. Unused contribution room can carry forward, but there are limits to how much can accumulate.
For example, an Alberta couple contributing the maximum amount each year could build a significant down payment much faster than many buyers realize, especially when combined with tax refunds and investment growth inside the account.
Can You Combine the FHSA With the Home Buyers’ Plan?
Yes. One of the biggest advantages of the FHSA is that it can still be used alongside the RRSP Home Buyers’ Plan (HBP). This allows some buyers to combine:
- FHSA savings
- RRSP withdrawals through the HBP
- Personal savings
- Gifted down payments
That combination can significantly increase your available down payment when purchasing your first home. Unlike the Home Buyers’ Plan, FHSA withdrawals do not need to be repaid later.
What Can You Hold Inside an FHSA?
An FHSA can hold many of the same investments as other registered accounts, including:
- Savings accounts
- GICs
- Mutual funds
- ETFs
- Stocks
Depending on your timeline and comfort level with risk, some buyers choose to invest their FHSA contributions rather than leaving the money sitting in cash.
What are the most common FHSA mistakes Calgary buyers make?
Waiting Too Long to Open the Account
Even if you’re not planning to buy immediately, opening an FHSA earlier can help you start building contribution room sooner.
Confusing the FHSA With the RRSP Home Buyers’ Plan
The FHSA and HBP work differently. The FHSA does not require you to repay withdrawals later like the RRSP Home Buyers’ Plan does.
Leaving the Money Sitting in Cash
Many buyers open the account but never invest the funds. Depending on your timeline and risk tolerance, some buyers choose to invest their FHSA contributions rather than leaving them in a standard savings account.
Missing Contribution Opportunities
Unused contribution room can carry forward, but there are still annual limits. Waiting too long can reduce how much tax-free room you can build before purchasing a home.
Assuming You Need to Buy Right Away
You do not need to purchase a home immediately after opening an FHSA. Many buyers use it as part of a longer-term savings strategy.
Is the FHSA Worth It?
For many Alberta first-time homebuyers, the answer is yes. The ability to receive a tax deduction on contributions while also withdrawing the funds tax-free for a home purchase is extremely valuable. If you know you want to buy a home in the future, opening an FHSA early can help you start building savings and contribution room sooner.
What should your next step be?
The FHSA has quickly become one of the best tools available for Alberta first-time homebuyers. Whether you’re planning to buy next year or several years from now, building a strategy early can make a major difference when it comes to your down payment, mortgage approval, and monthly payments.
If you’re planning to buy your first home anywhere in Alberta, I can help you create a strategy that combines your FHSA, down payment options, and mortgage approval plan before you start shopping. Contact me to get started!
How an Alberta mortgage broker helps you use the FHSA
Opening the account is the easy part. Turning it into an approved mortgage is where the planning matters:
- We confirm whether you actually count as a first-time homebuyer under the current-year-plus-four-previous-calendar-years test before you open the account.
- We map how much room you can realistically build by your target purchase date, at $8,000 a year toward the $40,000 lifetime cap.
- We stack the FHSA alongside the RRSP Home Buyers’ Plan, personal savings and gifted down payments to see what your total down payment could be.
- We show you what that down payment does to your approval — the mortgage amount, the insurance and the monthly payment.
- We flag the timing traps: waiting too long to open the account, or leaving the money in cash when your purchase is still years away.
- We build the plan before you start shopping, so the savings strategy and the mortgage approval line up.
Planning your first home purchase in Alberta?
Let’s put your FHSA, your down payment sources and your mortgage approval into one plan — with real numbers, before you start looking at listings.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageFHSA questions Alberta first-time buyers ask
What is a First Home Savings Account (FHSA)?
How much can you contribute to an FHSA?
Who can open an FHSA?
Can you combine the FHSA with the RRSP Home Buyers’ Plan?
What investments can you hold inside an FHSA?
What are the most common FHSA mistakes?
Is the FHSA worth it for Alberta first-time buyers?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. FHSA rules, contribution limits and eligibility requirements are set by the federal government and can change, and any mortgage is subject to lender approval. Please speak with a licensed mortgage professional or accountant about your specific circumstances. Mortgages for Less with INDI Mortgage.