Over the past couple of months, a lot of homebuyers have been asking the same question:
“How does what’s happening in Iran affect mortgage rates here in Alberta?”
It’s a fair question. At first glance, a conflict halfway around the world doesn’t seem connected to buying a home in Edmonton, Calgary, Red Deer, or anywhere else in Alberta. But global events can move financial markets very quickly, especially when oil prices are involved. And right now, rising oil prices are becoming one of the biggest factors affecting inflation expectations and mortgage rates in Canada.
Here’s what Alberta homebuyers and homeowners should understand.
How does a conflict in Iran reach mortgage rates in Alberta?
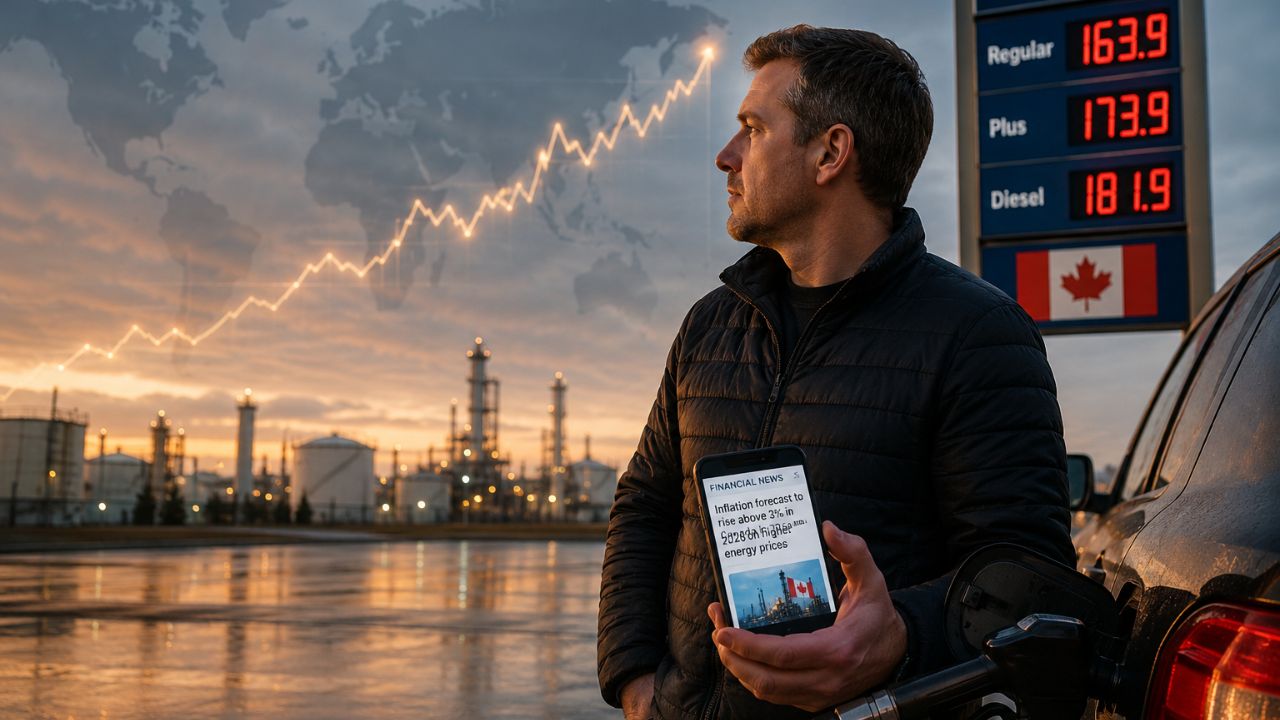
The main concern right now is oil. The conflict involving Iran has created fears about disruptions to global oil supply. When investors worry oil could become harder to transport or produce, prices usually rise quickly.
We’re already seeing that happen. According to economists at Desjardins, higher energy prices tied to the Iran conflict could push Canadian inflation back above 3% in 2026.
That’s something we need to keep an eye on because when inflation rises, central banks become more cautious about cutting rates. Bond markets also react by pushing yields higher, which directly impacts fixed mortgage rates.
Why are fixed mortgage rates more sensitive right now?
A lot of people assume fixed mortgage rates move directly with the Bank of Canada overnight rate. They don’t.
Fixed mortgage rates are primarily driven by bond yields. And bond yields tend to rise when investors think inflation could stay higher for longer.
Right now, markets are becoming concerned that rising oil prices could slow progress on inflation both in Canada and globally. That’s one reason we’ve already seen some upward pressure on fixed mortgage pricing in recent weeks.
Capital Economics recently noted that rising oil prices are contributing to higher mortgage rates and continued weakness in Canada’s housing market. This is especially important for buyers who were hoping fixed rates would continue falling throughout 2026. At this point, that outlook has become much less certain.
What does this mean for Alberta specifically?
Alberta is in a unique position compared to many other provinces.
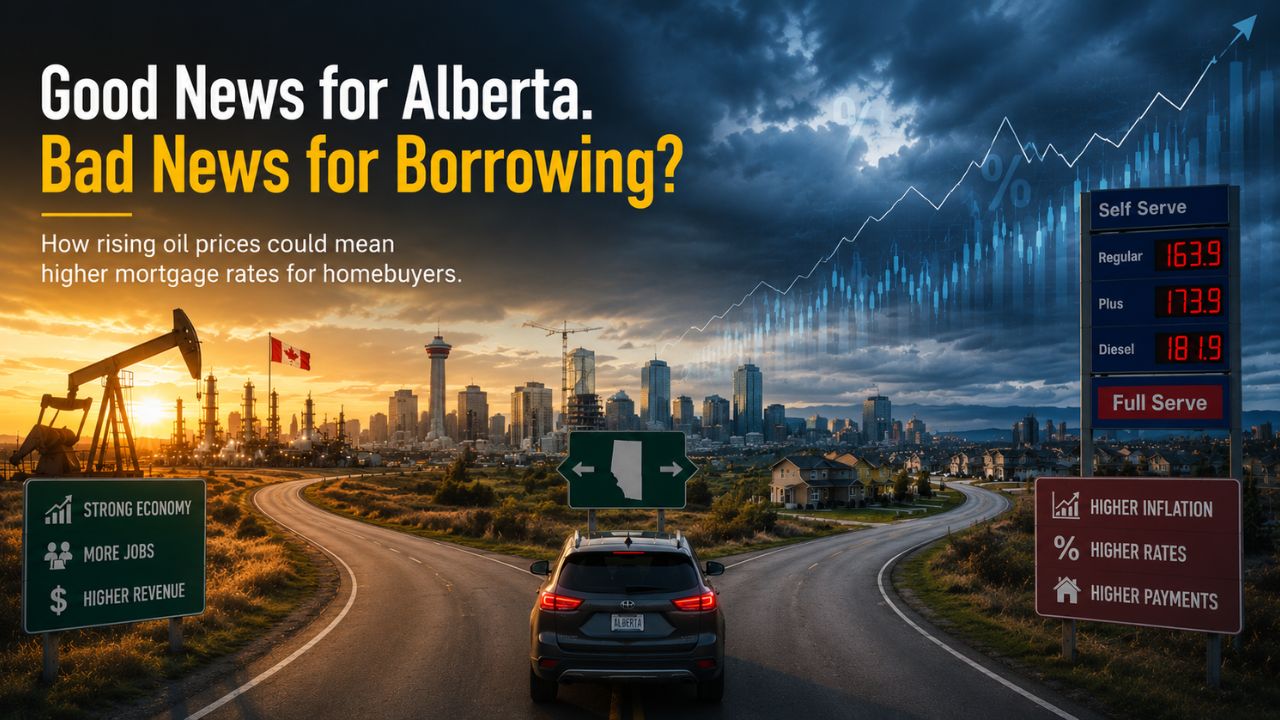
Higher oil prices can actually benefit Alberta’s economy in some ways. More oil revenue can support jobs, wages, government revenue, and economic activity here at home. Desjardins noted that higher oil prices are generally positive for Alberta’s economy overall.
But there’s also a downside. Higher oil prices can increase inflation nationally, which may keep mortgage rates elevated longer than many Canadians hoped.
So Alberta can experience both sides of this at the same time:
- Stronger local economic conditions
- Higher borrowing costs
That creates a complicated environment for homebuyers.
Could the Bank of Canada still cut rates?

Possibly, but the situation is becoming more complicated. Before oil prices started climbing again, many economists believed the Bank of Canada would eventually have room for additional cuts if economic growth weakened. Now the Bank faces competing pressures:
- Slower economic growth
- Weak manufacturing and consumer spending
- Higher inflation risks from energy prices
- Rising inflation expectations
Capital Economics recently pointed to weakening manufacturing activity and softer economic momentum in Canada. At the same time, inflation risks are rising again because of energy prices. That combination makes it harder for the Bank of Canada to move aggressively in either direction.
Right now, the most likely short-term scenario still appears to be a hold.
What should Alberta homebuyers do right now?
In uncertain markets, I usually tell clients not to focus too heavily on trying to perfectly time rates. That’s extremely difficult to do consistently.
Instead, I think buyers should focus on preparation and flexibility. If you’re planning to buy this year, a mortgage rate hold can still make a lot of sense. A rate hold allows you to secure today’s pricing while you continue shopping for a home. That can be especially valuable in volatile markets where rates can move quickly based on global events.
I also think buyers should avoid stretching themselves too aggressively right now. Even if rates eventually decline later, monthly costs are still relatively high compared to the ultra-low-rate years many people became used to. It’s important to leave some room in your budget.
What should Alberta homeowners be watching?
If your mortgage renewal is coming up within the next 12 to 18 months, this is a good time to start planning early. A lot can change between now and renewal time.
Oil prices, inflation data, bond yields, trade tensions, and Bank of Canada decisions are all moving markets right now. That doesn’t mean rates are guaranteed to rise significantly from here. But it does mean volatility is back. And in my experience, having a plan early usually creates better options later.
What are the next steps?
Global events often feel distant until they start affecting everyday costs here at home. Right now, Alberta homeowners and buyers are seeing how quickly that connection can happen.
The Iran conflict is influencing oil prices. Oil prices are influencing inflation expectations. Inflation expectations are influencing bond yields and mortgage rates. That chain reaction matters for anyone buying, renewing, refinancing, or planning ahead in Alberta’s housing market.
The good news is that preparation still matters more than prediction. If you understand your budget, your options, and your long-term plan, you’ll usually make better decisions than someone trying to guess the next Bank of Canada headline. Contact me to discuss how to navigate your own mortgage, whether it’s your first or a renewal.
How an Alberta mortgage broker helps when rates move on global headlines
You can’t control oil prices or bond markets. You can control how ready you are when they move. Here is what we work through together:
- We put a rate hold in place so today’s pricing is locked while you keep shopping, instead of shopping first and pricing later.
- We compare fixed against variable on your actual numbers, because the two react to completely different things — bond yields versus the overnight rate.
- We build in room in the monthly budget, rather than qualifying you for the maximum and hoping rates fall.
- We start renewal planning 12 to 18 months out, which is when you still have options rather than a deadline.
- We shop multiple lenders, since not every lender reprices at the same speed when bond yields move.
- We keep the focus on your file, not the headlines — income, down payment, debts and timing are the parts you can actually change.
Worried about where rates go next? Lock in a plan, not a guess.
Let’s look at your numbers, get a rate hold in place if you’re buying, and build a renewal plan you control — whatever oil and inflation do next.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageOil, inflation and Alberta mortgage rates: common questions
Does the conflict in Iran actually affect mortgage rates in Alberta?
Do fixed mortgage rates follow the Bank of Canada overnight rate?
How high could Canadian inflation go because of oil prices?
Are higher oil prices good or bad for Alberta?
Will the Bank of Canada still cut rates?
Is a mortgage rate hold worth it in a volatile market?
My renewal is coming up. When should I start planning?
This article is general information for Alberta homebuyers and homeowners, not financial, mortgage, tax or legal advice. Oil prices, inflation, bond yields, mortgage rates and lender guidelines change, and any mortgage is subject to lender approval. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.