Buying your first home in Alberta can feel overwhelming at the start. Between mortgage pre-approvals, down payments, home inspections, lawyers, and possession day, there are many moving parts.
The good news? It’s actually very manageable when you understand the steps in advance.
In this guide, we’ll walk through the entire process of buying a home in Alberta, from your first mortgage pre-approval all the way to getting the keys and moving in. Whether you’re buying in Calgary, Edmonton, or anywhere else in the province, this article will help you know what to expect.
Before you shop
Pre-approval, down payment plan, full application, ID and credit review — steps 1 to 4. This is where your real price range gets set.
Under contract
House hunting, the offer, final lender approval, inspection and condo documents, then removing conditions — steps 5 to 9.
Closing
The lawyer appointment, closing costs, property tax adjustments and possession day — steps 10 to 13.
Step 1: Why start with a mortgage pre-approval?
Before looking at homes, the smartest first step is getting a mortgage pre-approval in Alberta. A pre-approval helps determine:
- How much home you may qualify to buy
- What monthly payments may look like
- What mortgage programs fit your situation
- Whether you need to improve credit or reduce debt first
- How much down payment is required
- Whether you can lock in an interest rate early
What Impacts Your Mortgage Approval?
Several factors affect how much you qualify for:
Income — Employment income, salary, hourly income, bonuses, self-employment income, and other sources all matter.
Existing Debt — Car loans, student loans, credit cards, lines of credit, and other monthly obligations reduce borrowing power.
Credit Score — Better credit often creates more lender options and stronger rates.
Down Payment — Your down payment can significantly affect both affordability and available mortgage products.
Step 2: What are the down payment rules in Alberta?
In Canada, minimum down payments are generally:
- 5% on the first $500,000
- 10% on the portion between $500,000 and $1,500,000
- 20% minimum over $1,500,000
Why 20% Makes a Difference
Once you reach a 20% down payment, you move into what’s called a conventional mortgage, which can open up a few additional options. Most notably, you avoid paying mortgage default insurance, which can significantly reduce your overall borrowing cost. In some cases, you may also have access to longer amortization options, depending on the lender and property type.
With 20% down, lenders can sometimes be more flexible. This may include different qualification strategies and, in certain situations, slightly more borrowing flexibility. While it doesn’t automatically mean you’ll qualify for a higher purchase price, it can give you more room to structure your mortgage in a way that fits your goals.
For many first-time buyers, though, purchasing with less than 20% down is still an excellent path into homeownership.
Step 3: What goes into a full mortgage application?
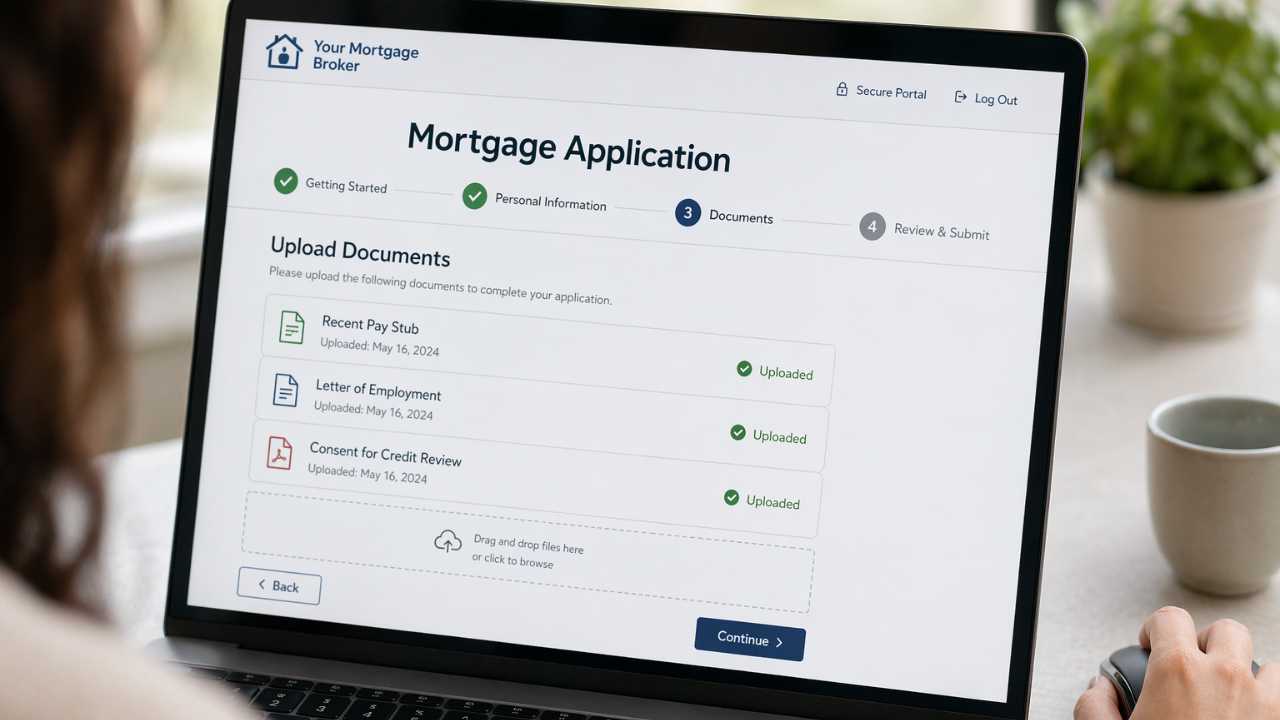
Once you’re ready, your mortgage broker will typically have you complete a secure online mortgage application. This usually includes:
- Personal information
- Employment history
- Income details
- Current debts
- Down payment sources
- Consent for credit review
- Co-borrower details (if buying with spouse/partner/family)
Important for New Canadians
If you have not been in Canada for a full three years, some applications may display errors regarding address or employment history. Often these can still be worked through depending on the lender and program available.
Step 4: What happens during ID verification and credit review?
Mortgage brokers in Alberta must comply with anti-fraud and identity verification regulations.
This often means using secure ID verification links, using your driver’s license or passport for verification, doing a credit bureau review, and having a final pre-approval discussion. Once complete, your broker can give you a much firmer buying range.
Step 5: Why house hunt with a realtor?
Once you’re pre-approved, you can start shopping for homes with confidence, knowing your price range and what your monthly payments may look like. This is where having a trusted Alberta realtor really becomes valuable. They’ll help you book showings, write competitive offers, negotiate on your behalf, and walk you through local neighbourhood trends so you understand what you’re buying into. They can also review comparable sales to make sure you’re not overpaying, and guide you through conditions and key deadlines so nothing gets missed during the process.
If you’re considering a new construction home, it’s especially important to have representation in place early. Builders often have their own sales teams, so having your own realtor ensures you have someone looking out for your best interests from the very beginning.
Step 6: What do you negotiate when you make an offer?
When you find the right property, your realtor helps prepare an offer. Typical items negotiated include:
- Purchase price
- Possession date
- Deposit amount
- Included appliances or items
- Conditions (financing, inspection, condo docs, etc.)
- The Deposit
Many Alberta purchases involve an initial deposit (example: $10,000), though it varies by property and market. That deposit is usually held in trust by the real estate brokerage and later forms part of your total down payment.
Step 7: What does the lender check for final mortgage approval?
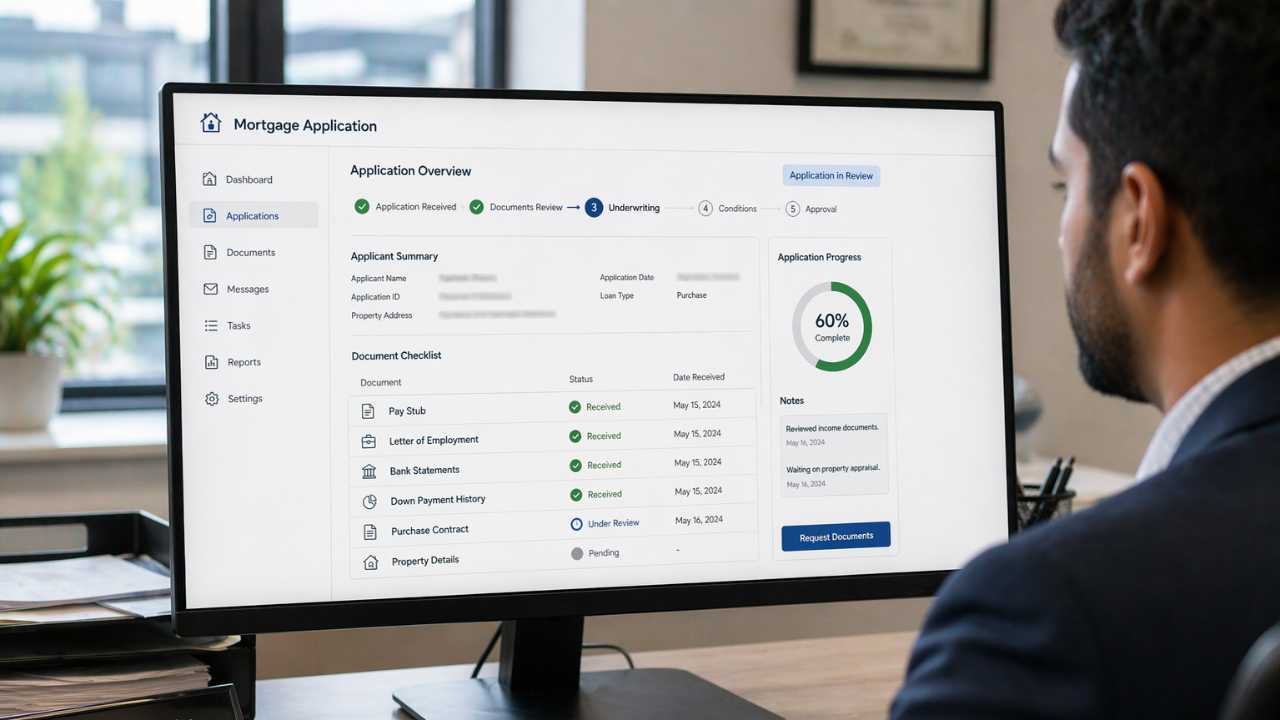
Once your offer is accepted, your mortgage moves from pre-approval to full approval.
Now the lender verifies:
- Income documents
- Most recent pay stubs
- Job confirmation if needed
- Bank statements
- Down payment history
- Purchase contract
- Property details
Important Tip
If documents are older, updated versions may be required. For example, they may need a more recent pay stub, updated bank statements, and proof of the deposit transfer. Responding quickly helps avoid delays.
Step 8: What should you check during the condition period?
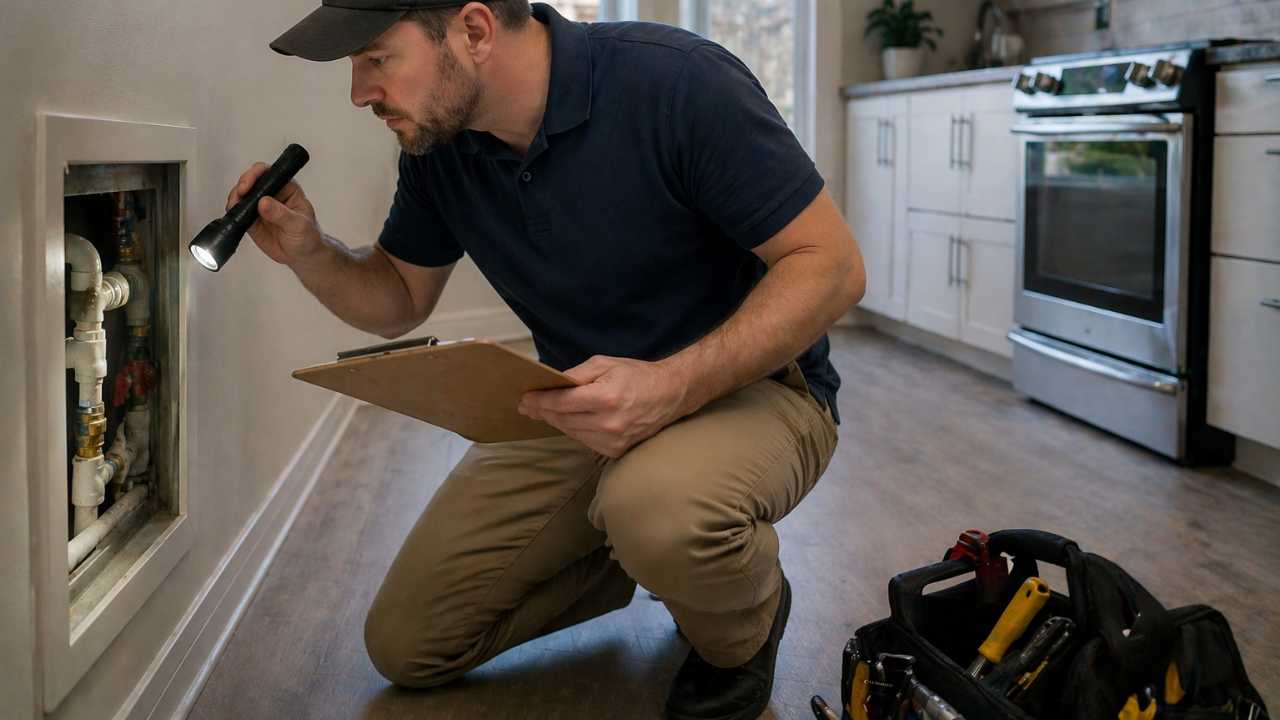
During your condition period, you’ll usually complete due diligence.
Home Inspection
A professional home inspection is designed to give you a clear picture of the property’s condition before you fully commit. Inspectors can identify potential roof issues, estimate the age and condition of the furnace, and flag any electrical or plumbing concerns. They’ll also look for signs of moisture or water damage, along with general maintenance items that may need attention now or in the near future.
Even if no major problems are found, the inspection still provides valuable insight for first-time buyers. It helps you understand how the home functions, what to expect for ongoing maintenance, and where you may need to budget for repairs or upgrades over time.
Condo Document Review
If buying a condo or townhouse with condo fees, documents should often be reviewed for:
- Reserve fund health
- Pending special assessments
- Litigation risk
- Rules and bylaws
- Financial management
Step 9: What does it mean to remove conditions?
Once financing, inspection, and condo review are satisfactory, you sign waivers removing conditions.
At that point, the deal becomes firm, the seller cannot sell to someone else, and the buyer generally cannot back out without consequences.
This is a major milestone.
Step 10: What happens at the lawyer appointment before possession?
Usually about a week before possession, you meet with your real estate lawyer. You may need to bring:
- Government ID
- Proof of home insurance
- Certified funds or bank draft
- Remaining down payment funds
- Closing cost funds
Your real estate lawyer plays a key role in making sure everything is completed properly before possession. They handle the mortgage registration and title transfer, ensure the lender’s funds are received, and arrange for the seller to be paid. They also take care of the final adjustments, such as property taxes or prepaid expenses, so that both sides are treated fairly on closing.
Alberta Note
Signatures written in ink (rather than digitally) are commonly required for certain land title registrations in Alberta, so in-person signing is often still common.
Step 11: What closing costs should you budget for?
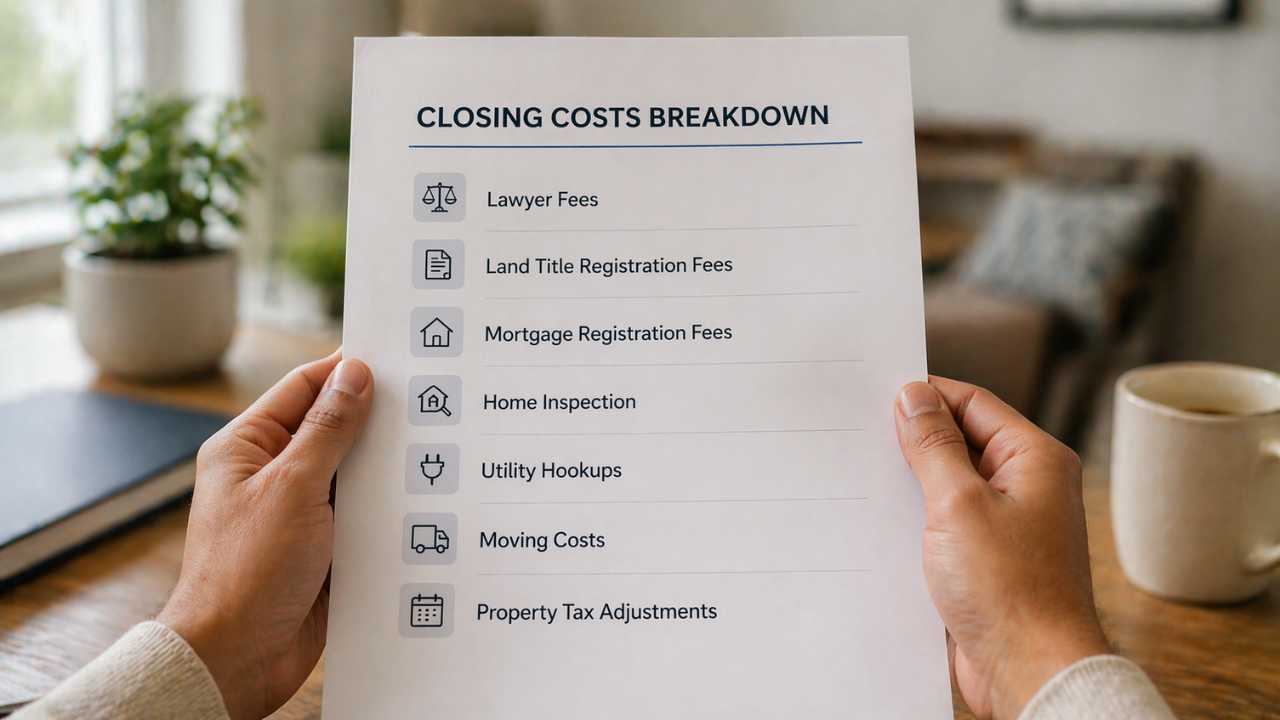
Beyond your down payment, first-time buyers should budget for closing costs. A common planning range is often 1% to 3% of purchase price, depending on circumstances. These costs include items such as:
- Lawyer fees
- Land title registration fees
- Mortgage registration fees
- Home inspection
- Utility hookups
- Moving costs
- Property tax adjustments
Step 12: How do property tax adjustments work?
This surprises many first-time buyers. If the seller already paid property taxes for the year, you may reimburse them for the portion covering the months you own the home. If they have not paid, adjustments may work in your favour. Your lawyer calculates this during closing.
Step 13: What happens on possession day?
On possession day:
- Funds are transferred
- Title work completes
- Realtor confirms release
- You receive keys
- You officially become a homeowner
Congratulations!
Smart First-Day Tip
Change the locks after taking possession.
What mistakes do first-time homebuyers make most often?
Many first-time buyers run into avoidable issues simply by not understanding the process upfront. Common mistakes I see include looking at homes before getting pre-approved, spending savings before closing, or taking on new debt before possession, all of which can impact your mortgage approval. Others miss document deadlines, underestimate closing costs, or ignore important findings during the home inspection. One of the biggest mistakes, though, is buying at the maximum amount a lender approves instead of choosing a monthly payment that actually feels comfortable for your lifestyle.
Why work with a mortgage broker in Alberta?
A mortgage broker is like a search engine. Instead of having to go to each website one by one, it brings up multiple results all at once. Instead of going from bank to bank, A mortgage broker can help compare multiple lenders, explain options, and guide you through the process from start to finish. For first-time buyers in Alberta, this can reduce stress and save time.
Need help buying your first home in Alberta?
If you’re thinking about buying in Calgary, Edmonton, or elsewhere in Alberta, getting expert guidance early can make the process much easier.
Whether you need a mortgage pre-approval in Alberta, down payment advice, or help understanding your options, the first step is simply starting the conversation. Contact me to talk.
How an Alberta mortgage broker helps a first-time buyer
Thirteen steps sounds like a lot. Most of them go smoothly when the financing is set up properly at the start:
- We get you a real pre-approval, not a rate quote — income, debts and credit reviewed, so your price range holds up when you write an offer.
- We map your down payment against the 5% / 10% / 20% tiers and show what crossing into conventional actually saves you in default insurance.
- We compare multiple lenders on one application, including the programs that work when you haven’t been in Canada three full years.
- We build a document list before you need it, so a stale pay stub or an unexplained deposit doesn’t stall your financing condition.
- We hold your financing condition deadline with your realtor, so conditions come off on time rather than at the last hour.
- We budget the closing costs and lawyer funds with you up front, so possession day isn’t the day you discover the shortfall.
- We help you pick a payment you’re comfortable with, not the maximum a lender is willing to approve.
Ready to start step one?
A pre-approval takes a short conversation and tells you exactly what you can shop for — in Calgary, Edmonton or anywhere in Alberta.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageBuying a first home in Alberta: common questions
What is the first step to buying a home in Alberta?
How much down payment do you need to buy a home in Alberta?
Why does a 20% down payment make a difference?
What documents does the lender need for final mortgage approval?
How much should first-time buyers budget for closing costs in Alberta?
What happens when you remove conditions on a home purchase?
What are the most common first-time homebuyer mistakes?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. Down payment rules, closing costs, land titles procedures and lender policies change, figures vary by property, purchase price and lender, and any mortgage is subject to lender approval. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.