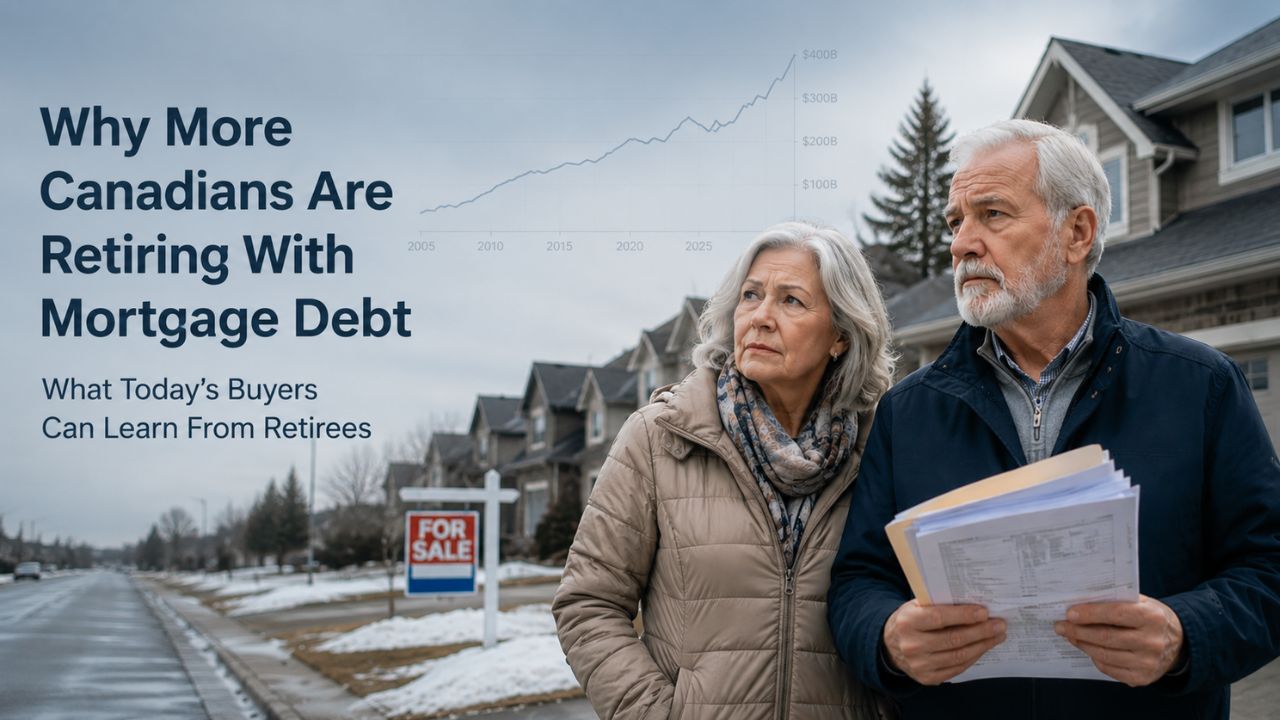
For years, many Canadians viewed retirement as the point where the mortgage would finally be paid off.
That’s changing.
Recent reports show that Canadians approaching retirement are carrying more mortgage debt than ever before, and many older homeowners are delaying plans to downsize. At first glance, this might not seem very relevant to a first-time homebuyer in Alberta. But in reality, these trends are having a major impact on affordability, housing supply, family finances, and even mortgage qualification strategies for younger buyers.
As a mortgage broker working primarily with first-time buyers, I think this is an important shift to understand because it helps explain why the housing market feels so competitive and financially stressful for many Canadians today.
Why are Canadians carrying mortgage debt longer?
According to recent data highlighted by Canadian Mortgage Trends, Canadians aged 55 to 64 saw the fastest growth in mortgage debt in 2025. There are a few reasons for this.
Many homeowners bought later in life or refinanced during periods of rising home values. Others helped children or family members enter the housing market by accessing equity from their homes. Some simply saw higher living costs, rising interest rates, and larger mortgage balances stretch repayment timelines longer than expected.
This is becoming increasingly common across Canada. The old idea that people enter retirement completely debt-free is no longer guaranteed.
Why is downsizing not happening as expected?
For years, many people assumed that older homeowners would eventually sell larger family homes and move into smaller properties or condos. That would theoretically create more inventory for younger buyers. But that is not happening nearly as quickly as expected.
Another recent report found that many retirees are delaying downsizing plans because they do not feel it is the right time to sell. Some are concerned about weaker housing markets. Others are worried that downsizing no longer saves as much money as it once did.
In many cities, condos, townhomes, and smaller properties have become very expensive themselves. Once you factor in moving costs, legal fees, property taxes, condo fees, and higher interest rates, downsizing may not feel financially attractive. Many retirees also simply prefer staying in their current home longer.
The result is that fewer family homes are entering the market than many experts expected.
Why does this matter to Alberta first-time homebuyers?
You might be wondering what this has to do with buying your first home in Alberta. Quite a bit, actually.
When fewer older homeowners sell, there are fewer detached homes available for younger families. That can keep prices elevated in certain segments of the market, especially in desirable neighbourhoods.
Even in Alberta, where affordability is generally better than places like Toronto or Vancouver, limited supply still affects competition and pricing. For first-time buyers, this means you may need to:
- expand your search area
- consider different property types
- adjust expectations on size or features
- move faster when the right home becomes available
How common is family financial support now?
One of the more interesting findings in these reports is that some older homeowners are taking on debt to help younger family members buy homes. I see this regularly in my own work. Parents are helping with:
- down payments
- gifted funds
- co-signing
- co-borrowing
- temporary financial support during qualification
With home prices and qualification rules becoming more difficult, many first-time buyers rely on some level of family assistance. There is nothing wrong with that, but it also means families are staying financially connected much longer than they used to. In some cases, parents are delaying their own retirement goals to help their children enter the housing market.
Why do mortgage decisions matter more than ever?
Another reason this trend matters is because today’s buyers need to think long-term. Stretching too aggressively to buy a home can create financial pressure later in life.
Many Canadians who bought during periods of ultra-low rates are now renewing at much higher rates, which has significantly increased monthly payments for some households. That does not mean homeownership is a bad decision. Far from it. But it does mean buyers should focus on sustainable affordability instead of simply qualifying for the maximum possible amount.
When I work with first-time buyers, we often discuss questions like:
- What happens if rates rise later?
- Will you still be comfortable financially?
- Are you planning to start a family?
- Could one income temporarily support the household?
- Are condo fees or property taxes likely to increase?
- Would a slightly lower purchase price reduce stress?
These conversations matter because homeownership should improve your financial future, not overwhelm it.
Do Alberta buyers still have opportunities?
The good news is that Alberta remains one of the more affordable housing markets in Canada. Compared to many major cities, buyers here can still find opportunities to purchase detached homes, townhomes, and condos at price points that are much more manageable. That is one reason Alberta continues attracting interprovincial migration and first-time buyers.
But affordability does not mean buyers should ignore long-term planning. The goal is not just buying a home today, but building financial stability over time.
What is my advice for first-time buyers?

If there is one takeaway from these recent trends, it is this:
Think beyond just getting approved.
A mortgage is not only about what a lender says you qualify for. It is about creating a financial plan that still works years from now. For first-time buyers, that means:
- keeping an emergency fund
- avoiding becoming house-poor
- understanding future renewal risk
- choosing a payment you can realistically manage
- planning for future life changes
The housing market will always shift over time. Interest rates will move and home values will rise and fall. But buyers who make sustainable decisions tend to put themselves in the strongest long-term position. And increasingly, that long-term thinking matters more than ever.
Contact me for personalized advice or to start planning your first home purchase.
How an Alberta mortgage broker helps a first-time buyer plan past the approval
Getting approved is the easy half. Here is what we work through so the mortgage still fits years from now:
- We separate the maximum a lender will approve from the payment that still leaves your budget comfortable after possession.
- We stress-test the renewal, so you know what happens to the payment if rates are higher when your term ends.
- We structure family help properly — gifted funds, co-signing or co-borrowing — so it strengthens the file instead of complicating it.
- We show what co-signing actually costs the co-signer, since that debt sits on their credit and can affect their own retirement plans.
- We widen the search where it helps: different property types, different areas, and what each does to your qualifying amount.
- We build in room for life changes — a growing family, one income for a stretch, rising condo fees or property taxes.
Planning your first home purchase in Alberta?
Let’s look at what you qualify for, what you should actually spend, and how family help fits in — before you start shopping.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageRetirement mortgage debt and first-time buyers: common questions
Are Canadians really entering retirement with a mortgage?
Why are retirees not downsizing the way everyone expected?
How does that affect a first-time homebuyer in Alberta?
What should first-time buyers do about limited supply?
How are parents helping their children buy homes?
Should I borrow the maximum amount I qualify for?
Is Alberta still a good place to buy a first home?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. Home prices, mortgage rates, qualification rules and lender guidelines change, and any mortgage is subject to lender approval. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.