If you’re looking to buy a home in Alberta right now, you’ve probably noticed how much prices and monthly costs have changed over the past few years. One cost-saving strategy I recommend to my clients is buying a home with a rental suite.
Whether it’s a basement suite that’s already built or a home where you plan to add one later, this can be a smart way to make homeownership more affordable and build long-term wealth. But there are a few important things you need to understand before you go down this path.
Why are rental suites becoming more popular in Alberta?
The biggest reason is simple: affordability.
A rental suite can help offset your mortgage payments each month. That means you may qualify for a higher purchase price, or just feel more comfortable with your monthly budget.
For a lot of first-time buyers, especially those new to Canada, this can be the difference between buying now or waiting years.
It’s not just about qualifying either. It’s about reducing financial stress. Having that extra income can give you breathing room if rates change or unexpected expenses come up.
What happens when you buy a home that already has a suite?
Lenders will typically accept the potential rent from an suite as part of your income. Some lenders will also ignore certain costs like heat and property taxes from the rental unit when doing the math. That can make a very big difference in how much you qualify for.
If the suite is legal, some lenders will allow you to use up to 100% of the rental income. If the suite is not legal but still fits within zoning, that amount is usually reduced to around 50%.
It’s also important to understand that lenders base your approval on more than just your mortgage payment. They include property taxes and heating costs in their calculations. So if we’re able to offset or exclude some of those costs because of the suite, it can significantly improve your approval.
Can you buy a home and add a suite later?
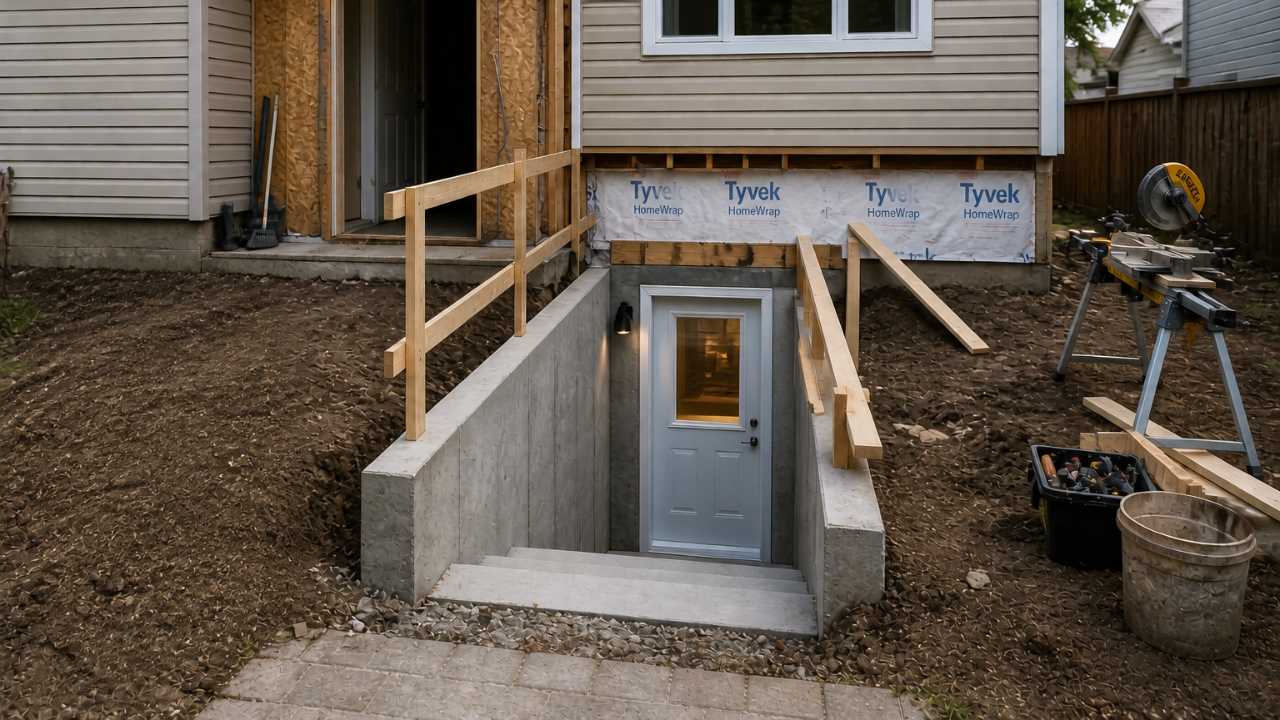
This can be a great strategy if you’re willing to put in some work.
Homes without suites are often cheaper upfront. If you can renovate and add a legal basement suite, you can increase both your income and your property value.
But there are a few key things to plan for.
First, you need to check zoning and municipal rules. Not every property allows for a secondary suite, and there are specific requirements around things like ceiling height, separate entrances, parking, and fire safety.
Second, you need to budget properly. Renovations can get expensive quickly, especially if you’re adding plumbing, electrical, and soundproofing.
In some cases, there are programs or lenders that can help with improvement financing, but it needs to be structured correctly from the start.
How does rental income affect your mortgage approval?
Different lenders treat rental income differently. Some are more flexible and allow us to use a higher percentage of the rent, while others are more conservative.
We also look at the overall structure of the deal. In some cases, we can offset certain property expenses with the rental income, which improves your ratios and increases what you can qualify for.
I’ve seen situations where one lender says no and another says yes, simply because of how they treat rental income.
What are the risks you should think about?
Rental suites can be a great strategy, but they’re not risk-free.
You need to think about things like:
- Vacancies where you don’t have a tenant
- Maintenance and repair costs
- Managing tenants and dealing with issues
- Local bylaws and compliance
You’re not just buying a home. You’re becoming a landlord. For some people, that’s exciting. For others, it’s more responsibility than they want, especially when your tenant is right downstairs.
Is buying a home with a rental suite the right strategy for you?
For a lot of my clients in Alberta, buying a home with a rental suite is one of the most effective ways to get into the market and stay comfortable financially.
It depends on your income, your goals, your comfort level with being a landlord, and the type of property you’re looking at.
The key is planning this properly before you start shopping. That way, you know exactly what you can afford, how rental income will be treated, and what your options are.
If you’re thinking about this strategy, I’m happy to walk you through the numbers and show you what it could look like in your situation. Book a call to talk about it.
How an Alberta mortgage broker helps with a suited property
A suite turns one straightforward mortgage question into several. Here is what we work through before you start writing offers:
- We confirm whether the suite is legal, and what that does to the percentage of rent a lender will use — up to 100% versus roughly 50%.
- We find the lenders that treat rental income most favourably for your file, because one may say no where another says yes on the same deal.
- We look at which property costs can be offset or excluded, since heat and property taxes are part of your approval calculation.
- We compare buying a home that already has a suite against adding one later, including improvement financing structured from the start.
- We flag the zoning and municipal requirements — ceiling height, separate entrance, parking, fire safety — before you commit to a renovation plan.
- We put a real purchase price and monthly payment beside each scenario, so you shop knowing what the rent does and doesn’t buy you.
Thinking about a home with a rental suite?
Let’s run your numbers on a suited property before you start shopping — so you know how the rent will be treated and what you can actually afford.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageBuying a home with a rental suite: common questions
How much of the rental income can a lender use?
Does a rental suite help me qualify for a bigger mortgage?
Why do heat and property taxes matter to my approval?
Is it better to buy a home that already has a suite, or add one later?
What do I need to check before adding a suite to a home?
Can I finance the cost of building the suite?
What are the risks of buying a home with a rental suite?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. Municipal suite rules, zoning bylaws and lender policies change, the treatment of rental income varies by lender, insurer, property and mortgage structure, and any mortgage is subject to lender approval. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.