The Bank of Canada made its latest interest rate announcement this week, and for many Edmonton homebuyers, the reaction was simple: not much has changed.
I joined Jay for a quick interview on January 28 to break down what the rate hold really means, what to watch next, and how upcoming changes like GST rebates could impact buyers here in Edmonton. If you’re thinking about buying your first home or planning your next move, here’s what you need to know.
Why did the Bank of Canada hold rates in January 2026?

The Bank of Canada left its key interest rate unchanged. While some people were hoping for early rate cuts in 2026, that didn’t happen.
“We did have a rate announcement,” I said during the interview, “but the rate announcement was that the interest rate by the Bank of Canada will remain unchanged.”
This wasn’t a surprise. Even though Canada saw weaker GDP and employment data toward the end of 2025, the Bank of Canada is taking a cautious approach. Inflation is coming down, but policymakers don’t want to move too fast.
“Inflation is well on track to be closer to 2% throughout the rest of the year,” I explained, “leaving room, if our economy needs it, for the Bank of Canada to cut rates later in the year.”
In other words, rate cuts are still possible in 2026, just not right away.
Why is uncertainty keeping rates steady?
One key reason rates are staying put is uncertainty around international trade. In 2026, Canada, the United States, and Mexico are set to renegotiate their free trade agreement. That creates risk, and central banks don’t like making big moves during uncertain times.
“The Bank of Canada doesn’t want to pre-emptively start stimulating our economy,” I said, “but rather be monitoring it and ready to create that stimulus if necessary.”
For Edmonton homebuyers, this means today’s rates are likely to stick around for a while. That stability can actually be helpful when you’re planning a purchase and budgeting for monthly payments.
How much could GST rebates and cost-of-living relief be worth?
We also talked about GST relief and rebates, which are especially important for lower- and middle-income families.
“A family of four may see that $1,100 go up to around $1,700 of rebate for the year 2026,” I shared.
This extra money isn’t huge compared to pandemic-era stimulus, and it’s unlikely to cause major inflation. But it does help families manage rising grocery costs and other essentials, which can make homeownership feel more achievable.
Could the new-home GST rebate help Edmonton buyers?
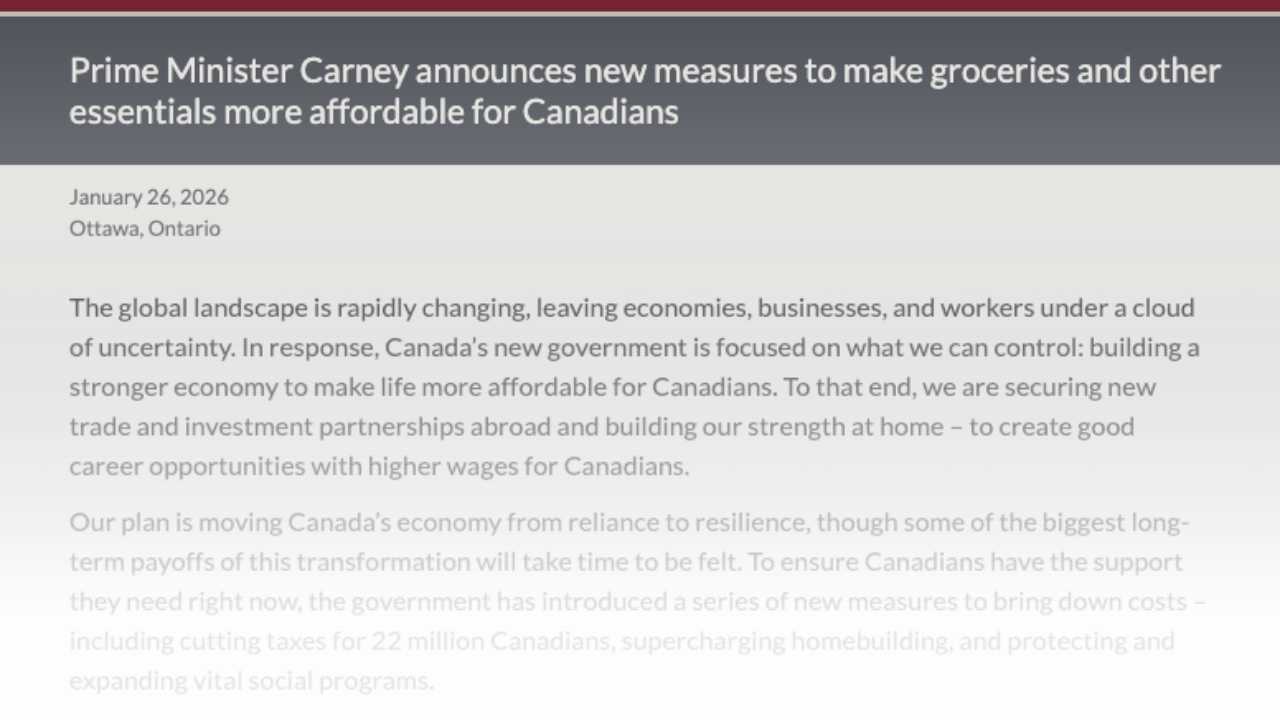
One of the most important developments for Edmonton buyers is the proposed GST rebate on new homes. Builders are already preparing for it, even before it officially becomes law.
Jay noted that many builders are adding clauses to contracts so the rebate can be passed on as soon as it receives royal assent. That could lower purchase prices and improve affordability for first-time buyers.
From my side as a mortgage broker, we’re still waiting on full details.
“Because it’s not in place yet, it’s not really impacting our pre-approvals per se,” I explained. “But we are looking forward to getting some more clarity on exactly how it’s going to be implemented.”
The rebate is expected to apply retroactively to purchases made after last April, which could benefit many buyers once the rules are finalized.
What does the rate hold mean for Edmonton homebuyers?
Right now, the market feels a bit like Groundhog Day. Rates haven’t changed, but important shifts may be coming later in 2026. For Edmonton buyers, this is a good time to get informed, plan ahead, and make decisions based on facts, not headlines.
This is where working with a local mortgage broker matters. I help buyers understand how today’s rates, future changes, and government programs actually affect their real numbers.
Where can you watch the full interview?
If you want to hear the full conversation and stay up to date with weekly market insights, head over to YouTube. Please like the video, subscribe to the channel, and click the bell so you don’t miss future updates. Your comments also help us know what topics you want covered next.
If you’re buying a home in Edmonton and want clear, honest mortgage advice, I’m always happy to help.
How an Alberta mortgage broker helps when rates are on hold
A rate announcement is a headline. What matters is what it does to your numbers:
- Get you pre-approved so you know the price range you qualify for at today’s rates.
- Show how a future rate change would move your monthly payment, so you’re not guessing from the news.
- Compare fixed and variable options across lenders with your purchase timeline in mind.
- Explain how government programs, like the proposed new-home GST rebate, fit into your purchase once the rules are final.
- Work alongside your Edmonton realtor so financing and the offer line up.
Planning to buy in Edmonton?
Find out what today’s rates mean for your budget before you start viewing homes.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageBank of Canada rate hold questions Edmonton buyers ask
What did the Bank of Canada announce in January 2026?
Why did the Bank of Canada hold rates?
Could the Bank of Canada cut rates later in 2026?
How much could the GST rebate be worth for a family?
Does the new-home GST rebate affect mortgage pre-approvals?
What should Edmonton homebuyers do while rates are on hold?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. It reflects the Bank of Canada’s January 28, 2026 announcement and the details of the GST measures known at that time; rates and government programs may have changed since. Any mortgage is subject to lender approval. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.