If you’ve been watching mortgage rates lately, you’ve probably noticed they’ve been making big jumps. That kind of volatility can put a lot of pressure on folks trying to get into the housing market right now. It can also create a lot of hesitation.
What a lot of first time buyers don’t know is that you can get something called a mortgage rate hold, something that can become one of the most important tools you use.
What is a mortgage rate hold?
A mortgage rate hold is when a lender agrees to “hold” a specific interest rate for you for a set period of time, usually between 90 and 120 days. That means even if rates go up during that time, you are protected and can still get the lower rate you locked in. This gives you time to get all your paperwork together and hunt for a house you want, not just one you feel pressured into.
If rates go down, most lenders will let you take the lower rate instead. So you’re essentially getting a safety net while you shop for a home or finalize your plans.
What is a pre-approval?
This is where I (as your broker) look at your full financial picture, including your income, job history, down payment, debts, and credit. From there, we figure out:
- How much you can realistically qualify for
- What your monthly payments might look like
- What price range makes sense for you
A proper pre-approval gives you clarity and confidence before you start making offers.
What is the difference between a rate hold and a pre-approval?
- A rate hold protects your interest rate.
- A pre-approval looks at whether you actually qualify.
You can have a rate hold without being fully pre-approved. In that case, you may have a great rate locked in, but no clear idea if you’ll actually be approved for the home you want.
On the other hand, a strong pre-approval will usually include a rate hold. That means you’re covered on both sides, your budget and your rate.
Why do rate holds matter more right now?
In a stable market, rate holds are helpful. In a volatile market like we’re seeing now, they become critical.
We’ve been in a period where bond yields, inflation expectations, and global events are all pushing rates around quickly. That creates uncertainty, and uncertainty makes it harder to make confident decisions.
A rate hold gives you one less thing to worry about. Instead of guessing where rates might go, you can lock something in and move forward knowing you aren’t going to miss out on lower rates.
How does a rate hold protect your budget?
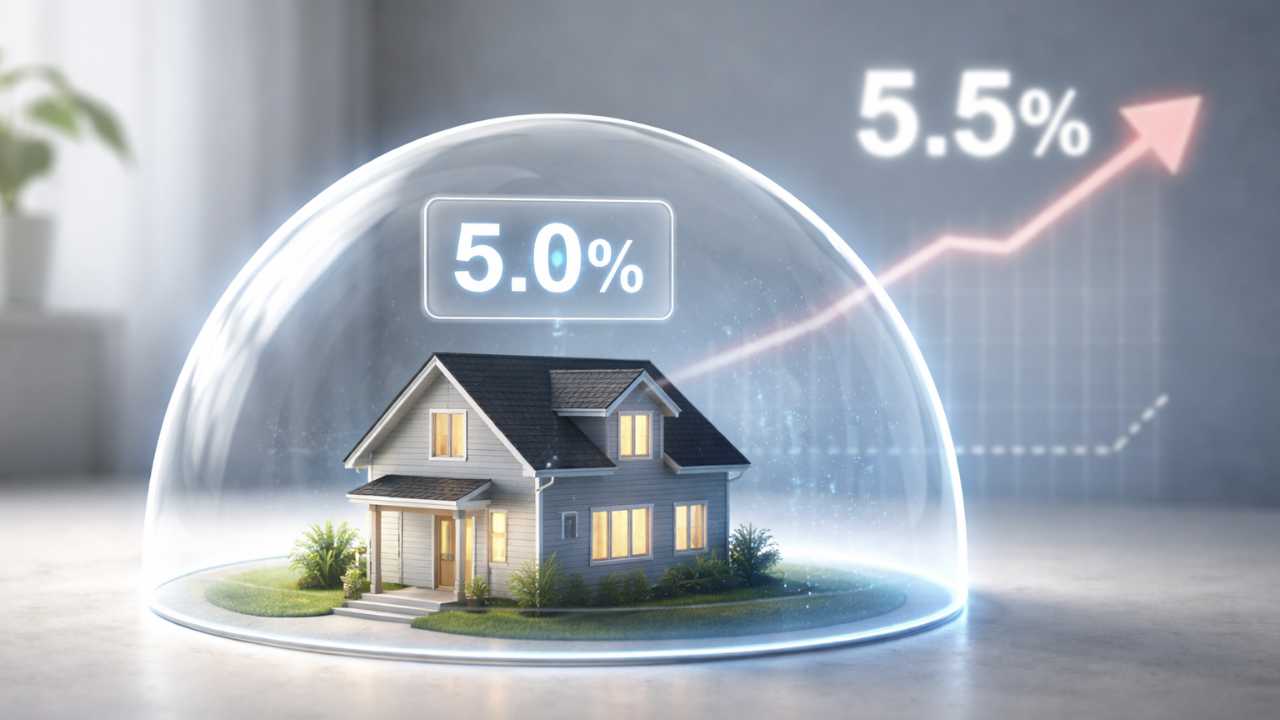
Let’s say you’re approved at a 5.0% rate on a $500,000 mortgage. If rates increase to 5.5% before you buy, your monthly payment could go up by a few hundred dollars, which is often enough to push most folks out of the market.
A rate hold locks in that 5.0% so your numbers stay consistent while you shop.
How does a rate hold protect your buying power?
When rates go up, your maximum purchase price can actually go down because of the mortgage stress test. Even a small increase in rates can reduce how much a lender is willing to approve. By securing a rate hold early, you’re also protecting your buying power while you’re out looking at homes.
Who should be using a rate hold?
In my opinion, everyone who is even thinking about buying in the next 3 to 4 months should have one in place.
That includes:
- First-time buyers who are just starting their search
- Move-up buyers who haven’t sold yet
- Homeowners planning a refinance or renewal strategy
- Anyone waiting for the “right” property
A rate hold doesn’t commit you to anything. It simply gives you options and protection.
Can you use a rate hold for a mortgage renewal?
Rate holds can also be useful if your mortgage renewal is coming up. If you’re within a few months of your renewal date, you may be able to lock in a rate ahead of time. This can protect you if rates increase before your renewal is finalized. This is especially important right now, because we’ve seen how quickly the market can shift.
What is the biggest mistake to avoid?
The biggest mistake I see is waiting too long.
A lot of people try to “time the market” or wait until they find the perfect home before talking to a broker. By then, rates may have already moved against them. I was working with a client last week who was likely going to qualify at 3.99%, but he wanted to wait until he found the house he wanted. On Wednesday night the rates went up at most lenders and now he won’t qualify unless he buys something smaller and cheaper.
Getting a rate hold early costs you nothing, but waiting can cost you money and time.
What is my advice as a mortgage broker?
Mortgage rate holds are one of the simplest and most effective ways to protect yourself in a changing rate environment.
The real advantage comes from combining a rate hold with a proper pre-approval. That way, you’re not just protected from rising rates, you also know exactly what you can afford.
If you’re thinking about buying, refinancing, or even just exploring your options here in Alberta, I’m always happy to walk you through both so you can move forward with clarity and confidence.
How an Alberta mortgage broker helps you lock in a rate
A rate hold is free to set up — the value is in pairing it with a real approval:
- We arrange a rate hold, typically for 90 to 120 days, so rising rates don’t catch you mid-search.
- We build a proper pre-approval from your income, job history, down payment, debts and credit — so you know your budget, not just your rate.
- We show how a rate change would affect your payment and stress-test buying power.
- We help move-up buyers who haven’t sold yet protect their numbers while they wait.
- We can lock a rate ahead of a renewal or refinance when you’re within a few months of the date.
- We work with buyers and homeowners across Calgary, Edmonton and all of Alberta.
Thinking about buying in the next few months?
Get a pre-approval with a rate hold in place — it costs you nothing and protects your rate and your budget.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageMortgage rate holds: common questions
What is a mortgage rate hold?
What happens if rates go down during my rate hold?
What is the difference between a rate hold and a pre-approval?
How does a rate hold protect my buying power?
Who should get a mortgage rate hold?
Can I get a rate hold for my mortgage renewal?
Does a mortgage rate hold cost anything?
This article is general information for homebuyers and homeowners in Alberta, not financial, mortgage, tax or legal advice. Rate-hold periods, terms and rate-drop policies vary by lender, rates change frequently, and any mortgage is subject to lender approval. Rate commentary reflects market conditions when the article was first published in March 2026. Please speak with a licensed mortgage professional about your specific situation. Mortgages for Less with INDI Mortgage.