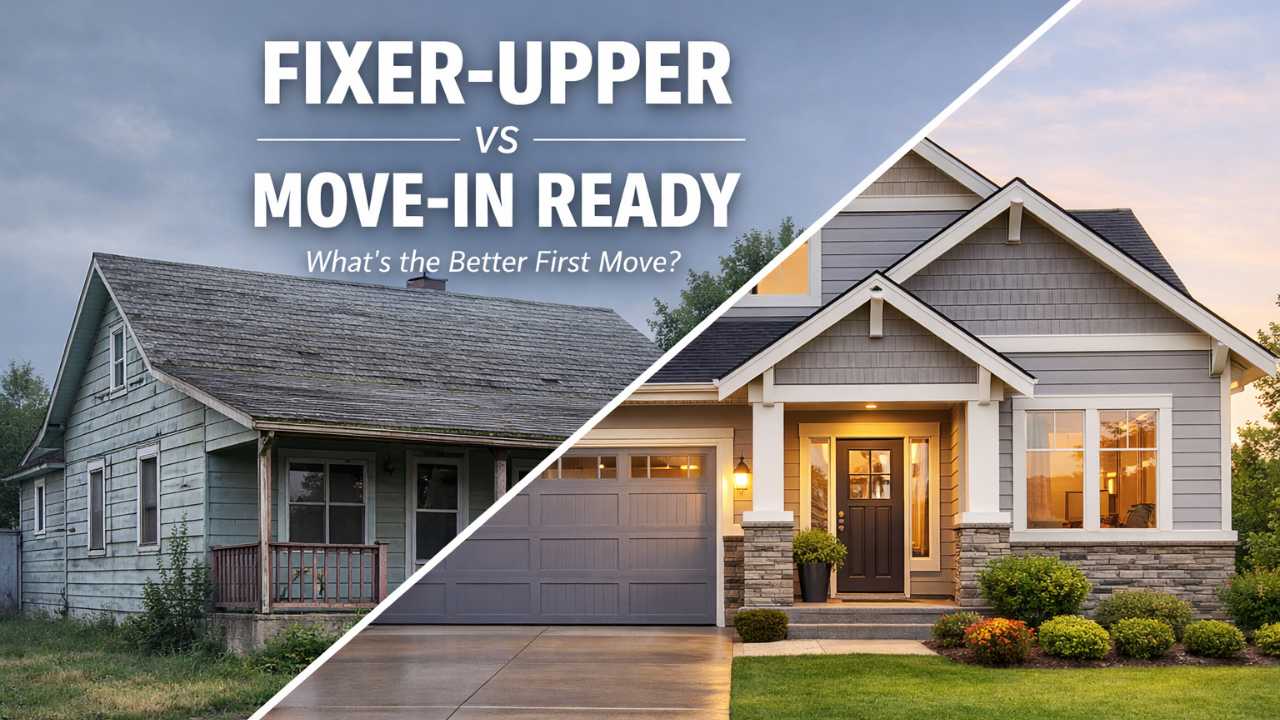
If you’re buying your first home, it can feel like every decision is a big one. One of the most common questions buyers ask themselves is this: Should I buy a fixer-upper, or go with something that’s move-in ready?
Both options can work well. But they come with very different costs, risks, and timelines. In this article, I’ll walk you through both options so you can figure out which one fits your situation best.
What is a fixer-upper?
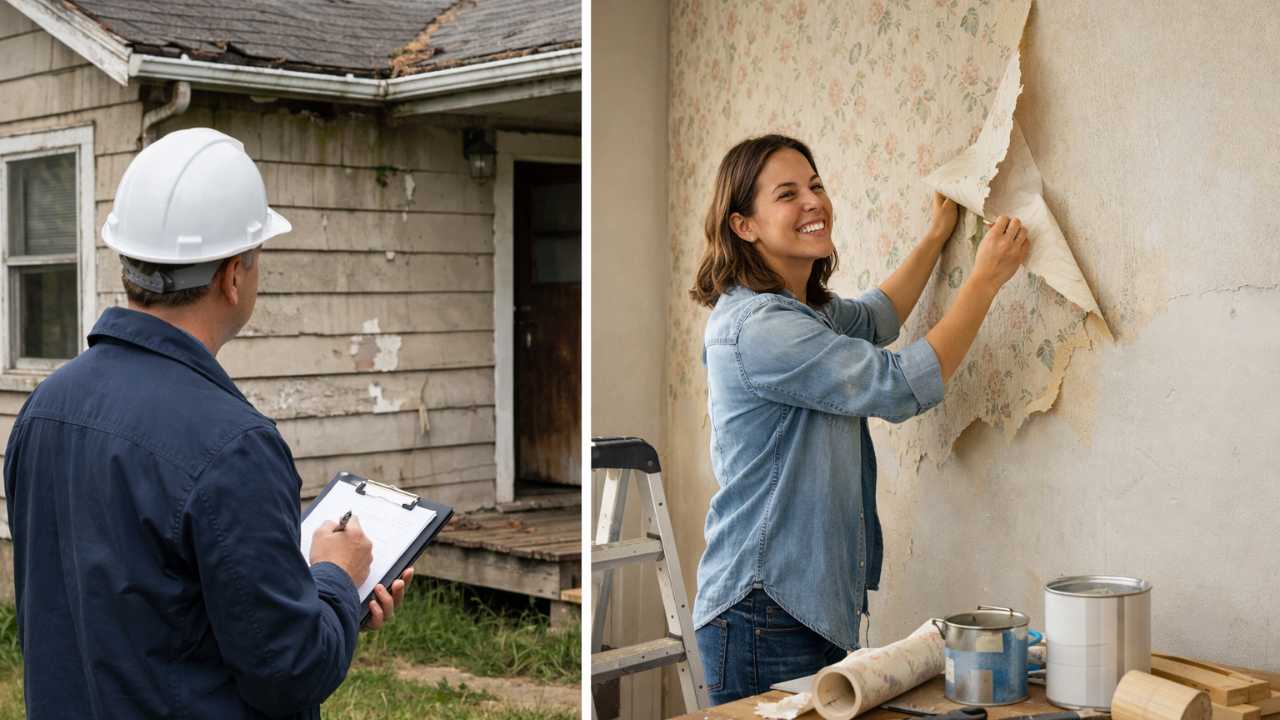
A fixer-upper is a home that needs work. That could mean small cosmetic updates like paint and flooring, or bigger repairs like kitchens, bathrooms, or even structural issues. You’re buying a home at a lower price, but planning to invest time and money to improve it. The best way to find out if the home you have your eye on is going to need some work is to have a professional inspection done.
Key characteristics:
- Lower purchase price compared to similar homes
- Visible wear and tear or outdated finishes
- May require repairs before or after moving in
- Renovation costs need to be budgeted
Why some buyers choose it:
- It can be more affordable upfront
- Opportunity to customize the home
- Potential to increase the home’s value over time
For some buyers, this is a way to get into the market sooner—especially if move-in ready homes feel out of reach.
What is a move-in ready home?
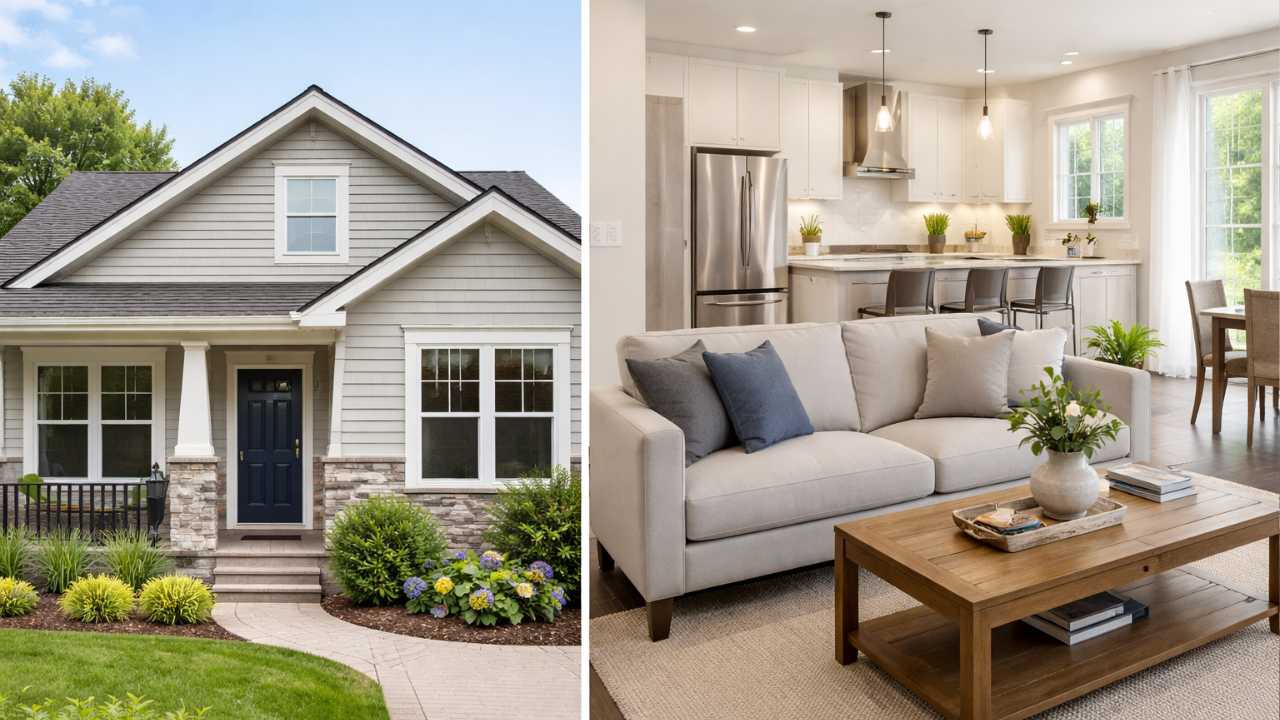
A move-in ready home is exactly what it sounds like. It’s a home you can move into right away without needing to do major work. Everything is functional, clean, and generally updated to modern standards.
Key characteristics:
- Higher purchase price
- Minimal or no immediate repairs needed
- Updated finishes and systems
- Ready for immediate occupancy
Why some buyers choose it:
- Convenience and simplicity
- Predictable costs
- Less stress after closing
- Ideal for busy schedules or families
If you want a smoother, more predictable experience, this option is often appealing.
What are the pros and cons of each?
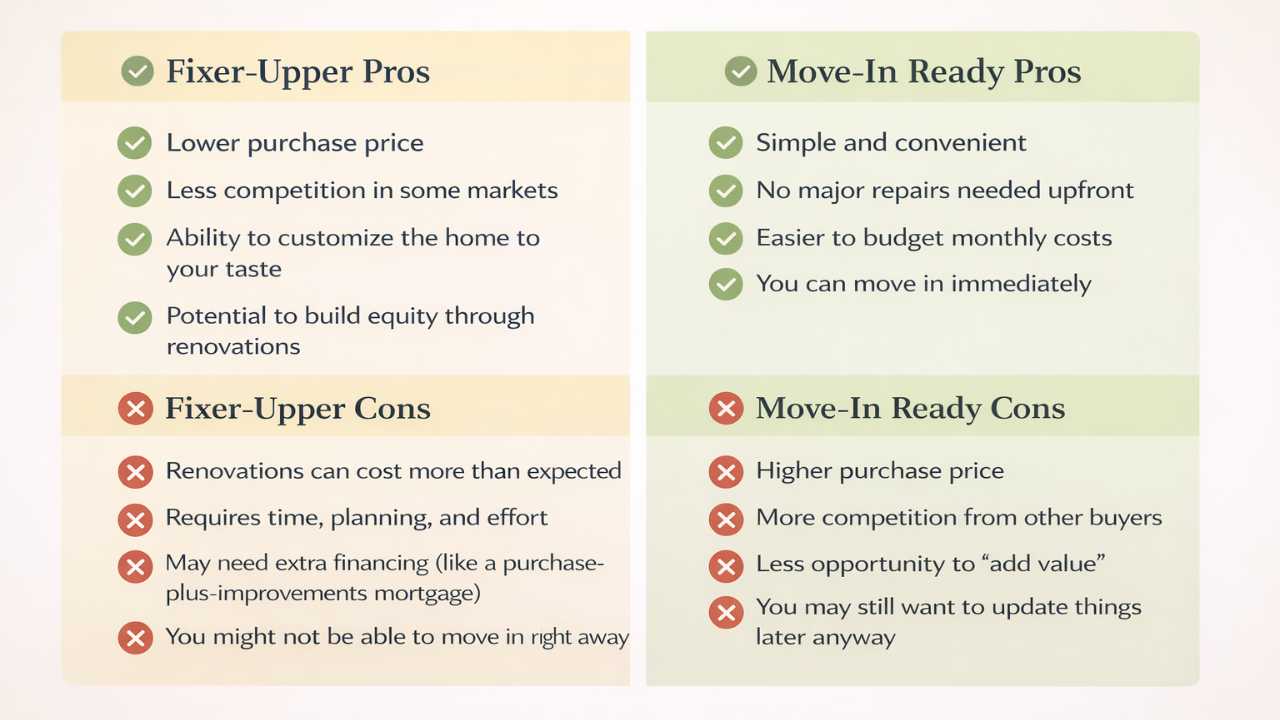
Fixer-Upper Pros
A fixer-upper typically comes with a lower purchase price and may face less competition in some markets. It also gives you the ability to customize the home to your taste, with the potential to build equity over time through renovations.
Fixer-Upper Cons
Renovations can cost more than expected and often require time, planning, and effort. You may also need extra financing, such as a purchase-plus-improvements mortgage, and in some cases, you might not be able to move in right away.
Move-In Ready Pros
A move-in ready home is simple and convenient, with no major repairs needed upfront. It makes it easier to budget your monthly costs, and you can move in immediately without the added stress of renovations.
Move-In Ready Cons
These homes usually come with a higher purchase price and more competition from other buyers. There is also less opportunity to add value, and you may still find yourself wanting to update certain features later on.
Which option is better for first-time buyers?
There’s no one-size-fits-all answer in home ownership. It really depends on your situation.
If affordability is your biggest concern:
A fixer-upper might help you get into the market sooner. But you need to be realistic about renovation costs. I often see buyers underestimate this part.
If your income is stable but tight:
A move-in ready home can be safer. You’ll have fewer surprise costs, which makes budgeting easier.
If you want flexibility and control:
A fixer-upper gives you the chance to shape the home the way you want. But it comes with more responsibility.
If you have a busy lifestyle or young family:
Move-in ready is usually the better fit. Renovations take time and energy that not everyone has.
If you’re comfortable managing projects:
A fixer-upper can be a great opportunity—especially if you’re handy or have reliable contractors.
From a mortgage perspective, both options are possible. But fixer-uppers sometimes require a bit more planning, especially if you’re financing renovations.
What mistake do many first-time buyers make?
The biggest mistake I see is focusing only on the purchase price. A fixer-upper might look cheaper at first. But once you add renovation costs, temporary living arrangements, and unexpected repairs, it can end up costing more than a move-in ready home.
On the flip side, some buyers stretch too far to afford a move-in ready home. That can leave them feeling “house poor,” with little room in their budget for anything else. The key is to look at the total cost, not just the listing price.
How does a mortgage broker help you decide?
My job is to look at your full financial picture and help you understand what each option actually looks like for you.
For example:
- Can you qualify for a purchase-plus-improvements mortgage?
- How will renovation costs affect your approval?
- What will your monthly payments look like in each scenario?
- Do you have enough buffer for unexpected costs?
Sometimes the “cheaper” home isn’t actually cheaper once everything is factored in. And sometimes a slightly higher purchase price is the safer choice.
It’s about making a decision that works not just today, but over the next few years. Contact me to talk it out and I’ll help you take your first steps toward home ownership.
How an Alberta mortgage broker helps you choose the right home
Before you fall for a listing, we run the numbers on both paths:
- We check whether you qualify for a purchase-plus-improvements mortgage if the home needs work.
- We show how renovation costs affect your approval before you write an offer.
- We compare your monthly payments in each scenario, side by side.
- We look at the total cost — renovations, temporary living costs and a buffer for surprises — not just the listing price.
- We help you avoid becoming “house poor” by stretching too far for a finished home.
- We work with first-time buyers across Calgary, Edmonton and all of Alberta.
Deciding between a fixer-upper and move-in ready?
Find out what each option really costs you — and what you qualify for — before you make an offer.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageFixer-upper vs move-in ready: first-time buyer questions
What is the difference between a fixer-upper and a move-in ready home?
Is a fixer-upper cheaper than a move-in ready home?
Can I get a mortgage to cover renovations on a fixer-upper?
Which is better for first-time buyers with a tight budget?
Who should choose a move-in ready home?
How do I know if a home needs a lot of work?
This article is general information for first-time homebuyers in Alberta, not financial, mortgage, tax or legal advice. Lender products, rates and policies vary and change, and any mortgage — including a purchase-plus-improvements mortgage — is subject to lender approval. Please speak with a licensed mortgage professional about your specific situation. Mortgages for Less with INDI Mortgage.