By Josh Tagg, mortgage broker · Mortgages for Less with INDI Mortgage · Calgary, serving all of Alberta ·
For many Albertans, the dream of home ownership is stronger than ever, but rising prices and high interest rates make the decision between renting and buying more complicated. While buying allows you to build equity, renting provides flexibility and fewer upfront costs. The key is deciding which option fits your financial situation and lifestyle today—and into the future.
When does renting make sense?
Some financial experts argue that renting can be a smart long-term option. Monthly rent is often cheaper when you factor in all the costs of ownership. Beyond your mortgage, home ownership comes with added expenses like property taxes, higher insurance and utilities, repairs, and ongoing maintenance.
For those who value mobility, renting makes sense. If your job or personal circumstances change, you can move without worrying about selling a property. Renting can also reduce stress since landlords, not tenants, are responsible for major repairs.
When does buying make sense?
On the other side of the debate, many realtors and financial experts believe that renting long-term comes at a cost. Renters can easily spend over a million dollars in their lifetime with nothing to show for it. Homeowners, on the other hand, build equity with every mortgage payment and can benefit from future price appreciation.
Homeownership also comes with advantages like stability, personalization, and the ability to borrow against your home equity when needed.
How do lifestyle and long-term goals change the answer?
Financial considerations aside, lifestyle plays a big role in the rent-versus-buy decision. Renting is ideal if you value flexibility, travel frequently, or aren’t ready to settle in one location. Buying makes more sense if you want stability, the freedom to personalize your space, and the chance to grow your wealth through property ownership.
If you’re uncertain about your long-term plans, renting might give you the breathing room to figure it out. But if you’re confident you’ll stay in Calgary and can afford the upfront costs, buying may be worth serious consideration.
What is happening in Calgary’s housing and rental market?
Alberta’s housing market is on the upswing. Home sales and prices are expected to keep climbing, with Calgary leading the way due to strong population growth and limited housing supply. For buyers who can commit to staying in Calgary for at least eight to ten years, buying a home could provide a solid financial foundation.
At the same time, Calgary’s rental market is tightening, with rents increasing as demand outpaces supply. For many renters, this means less certainty about long-term housing costs.
What does renting vs buying cost in Calgary over 25 years?
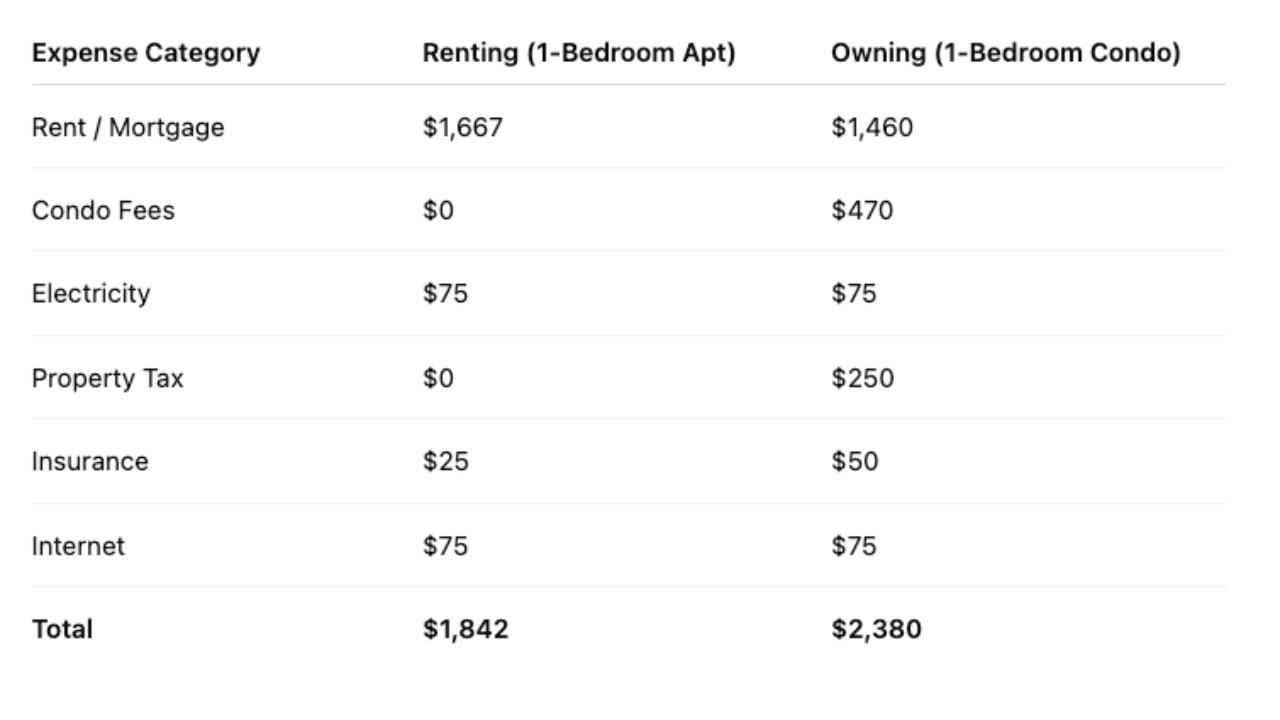
Let’s put this into perspective with a comparison between a rented 1 bedroom apartment and a purchased 1 bedroom condo, both in Calgary. The total cost of renting would be about $1,842 each month, compared to a $335,000 condo with a monthly mortgage payment of $1,460.
| Expense | Renting (1-bedroom apartment) | Owning (1-bedroom condo) |
|---|---|---|
| Rent / mortgage payment | $1,667 | $1,460 |
| Condo fees | $0 | $470 |
| Electricity | $75 | $75 |
| Property tax | $0 | $250 |
| Insurance | $25 | $50 |
| Internet | $75 | $75 |
| Total | $1,842 | $2,380 |
For those of you who appreciate a visual representation (like me) here’s a bar graph.
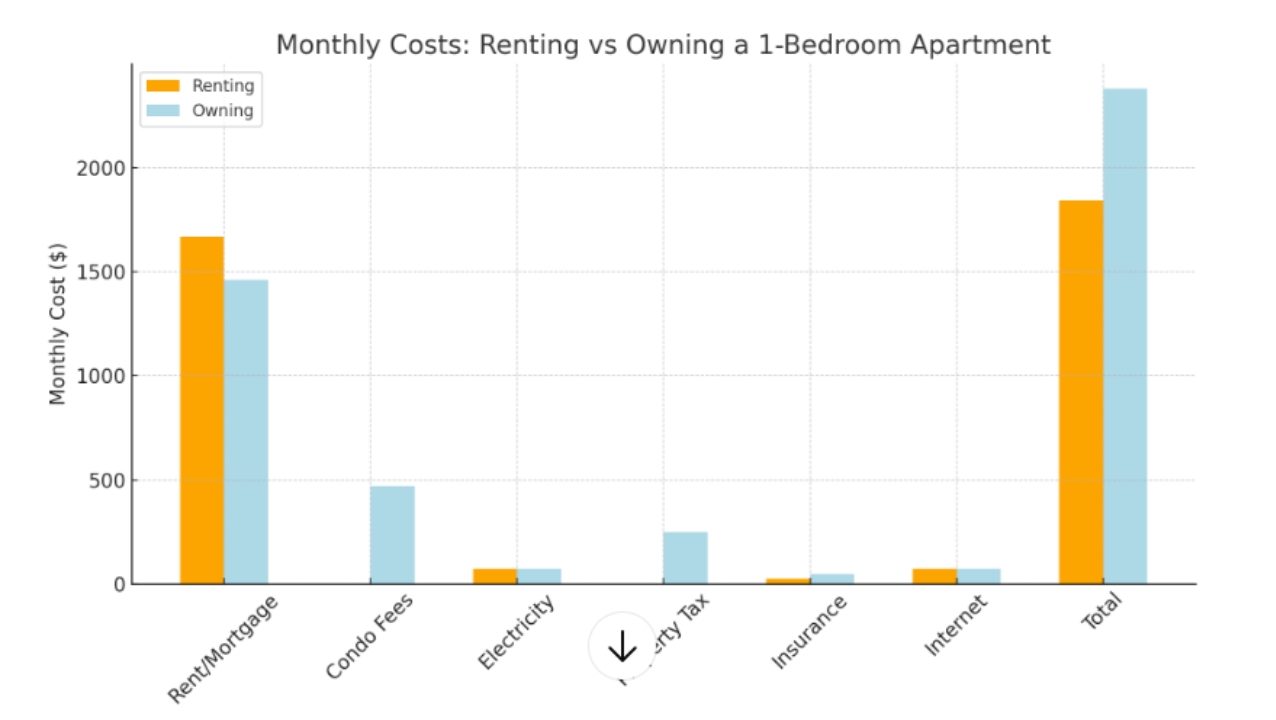
The difference between these two scenarios is $538 a month, enough to be a determining factor for the average buyer. By renting, you save money in the short term. But what does the long run look like? Rent has typically increased about 3.5% each year and mortgage rates have been anywhere from 1.4% to 5.9% over the last 25 years.
If you were to buy a 1 bedroom condo today in Calgary, 25 years from now you will have paid approximately a total of $714,000 for your home and be mortgage free. If, instead, you decided to spend the next 25 years renting, in 2050 you would be paying about $3,960 a month in rent and will have spent approximately $820,650 in the last 25 years.
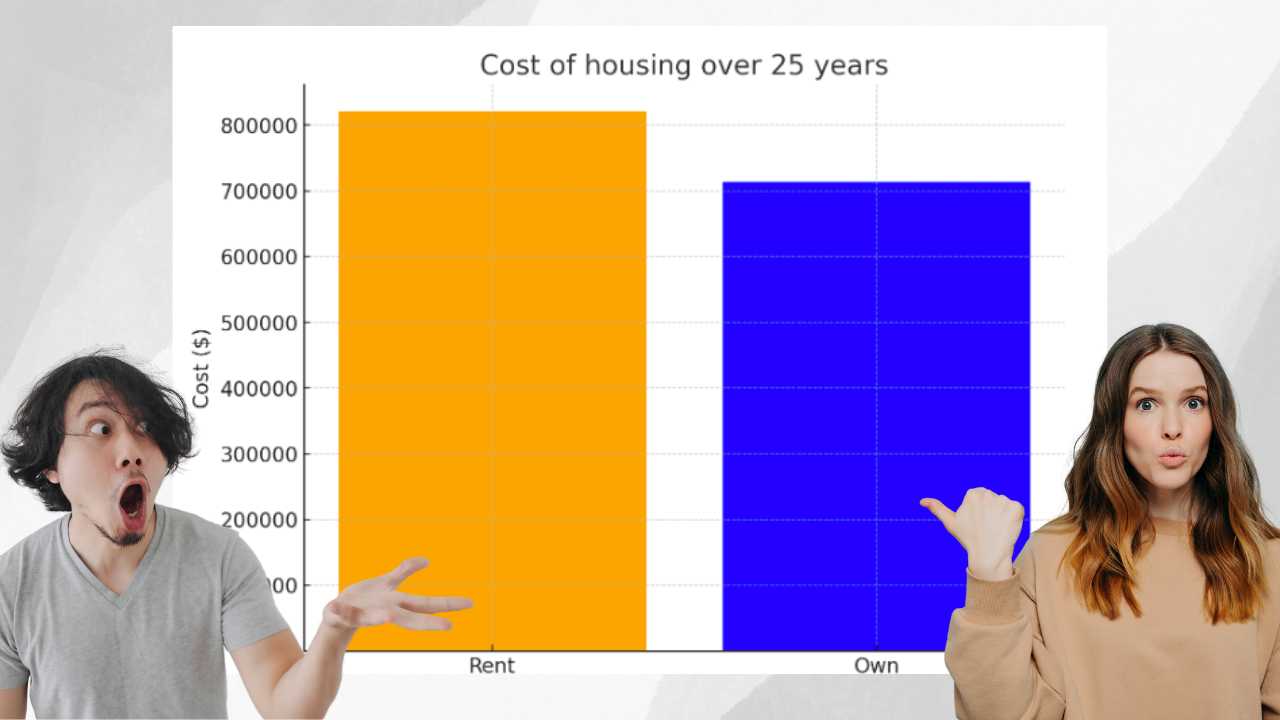
By renting, not only will you end up spending $106,650 more compared to buying, and you’ll also miss out on the equity you could have built in your home. By 2050, the 1 bedroom condo you bought in 2025 for $335,000 is likely to sell for about $477,000 (based on the trends we have seen in housing prices over the last 25 years in Calgary); that’s $142,000 in equity.
What help is there for Calgary first-time buyers?
If you’re leaning toward buying your first home, take advantage of programs like the First Home Savings Account (FHSA), the RRSP Home Buyers’ Plan, and the First-Time Home Buyer Tax Credit. These can help reduce the financial burden of purchasing your first home. It’s also important to work with a mortgage broker who understands the Calgary market. A broker can compare lenders, negotiate rates, and help you decide how much you can realistically afford.
There’s no universal answer to the rent-versus-buy question. Renting may offer peace of mind and flexibility, while buying can provide stability and the chance to build wealth over time. In Calgary’s fast-moving market, the right choice depends on your financial circumstances, lifestyle, and long-term goals.
If you’re a first-time home buyer wondering whether now is the right time to make the leap, I can guide you through the numbers and help you make a decision that fits your future.
How a Calgary mortgage broker helps you decide between renting and buying
The rent-or-buy answer depends on your numbers, not an average. A broker works them out with you:
- Your real monthly cost of owning, with condo fees, property tax and insurance included, next to what you pay in rent now.
- How much you can realistically afford, and what a lender will approve.
- How the FHSA, the RRSP Home Buyers’ Plan and the First-Time Home Buyer Tax Credit fit your down payment and closing costs.
- Rates and terms compared across multiple lenders in Calgary, Edmonton and the rest of Alberta.
Ready to compare renting and buying with your own numbers?
See what you qualify for and what owning would cost you each month.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageQuestions about renting vs buying in Alberta
Is it cheaper to rent or buy a 1-bedroom in Calgary?
Why does owning cost more each month if the mortgage payment is lower than rent?
Is buying cheaper than renting over 25 years?
How much equity would a Calgary condo owner build?
How long should I plan to stay in Calgary before buying?
What programs help first-time buyers in Calgary?
The rent and ownership figures are an illustrative Calgary example from September 2025, based on assumptions about rent growth, mortgage rates and price trends. Your costs, rates and lender policies will differ. This is general information, not financial advice; please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.