
By Josh Tagg, mortgage broker · Mortgages for Less with INDI Mortgage · Calgary, serving all of Alberta ·
This month has already brought a wave of headlines about Canada’s slowing economy — falling factory sales, weaker trade, and more signs that growth is losing momentum. On the surface, that sounds like bad news. But for Albertans thinking about buying their first home, there’s a silver lining: weaker economic data makes it more likely that mortgage rates will drop.
What is happening in Canada’s economy?
Manufacturing and wholesale sales both fell in August, the first decline in months. The government also announced a bailout for the lumber sector after U.S. tariffs hit Canadian producers hard, and Stellantis, a major automative manufacturer, said it’s closing its Brampton plant — a clear reminder that trade tensions are still hurting jobs and investment.
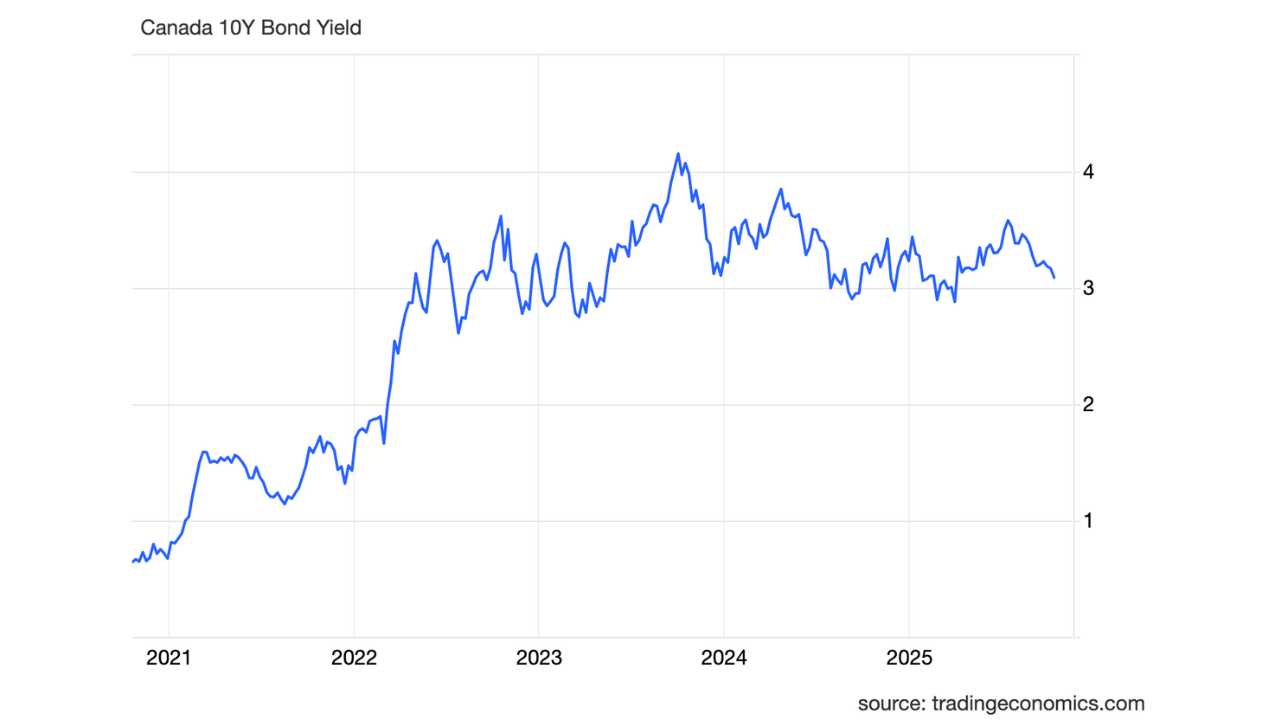
These developments made investors nervous, pushing Canadian bond yields lower. Since fixed mortgage rates are closely tied to bond yields, this drop could soon translate into better deals for borrowers.
Meanwhile, U.S. data is sending mixed signals — slower hiring and weaker demand for workers, but rising prices due to tariffs. That combination unsettled markets but reinforced expectations that central banks will need to cut rates to keep growth on track.
Could mortgage rates ease?
For now, all signs point to lower borrowing costs ahead. Canada’s 4-year swap rate — a key benchmark for fixed-rate mortgages — just hit a five-month low. The 5-year Canada Mortgage Bond yield also slipped, suggesting lenders could soon start trimming fixed rates.
Markets now expect a 62% chance the Bank of Canada will cut rates at its October 29 meeting. In the U.S., rate cuts are almost guaranteed before year-end. The direction is clear: both economies are softening, and policymakers are preparing to act.
What does it mean for homebuyers in Alberta?
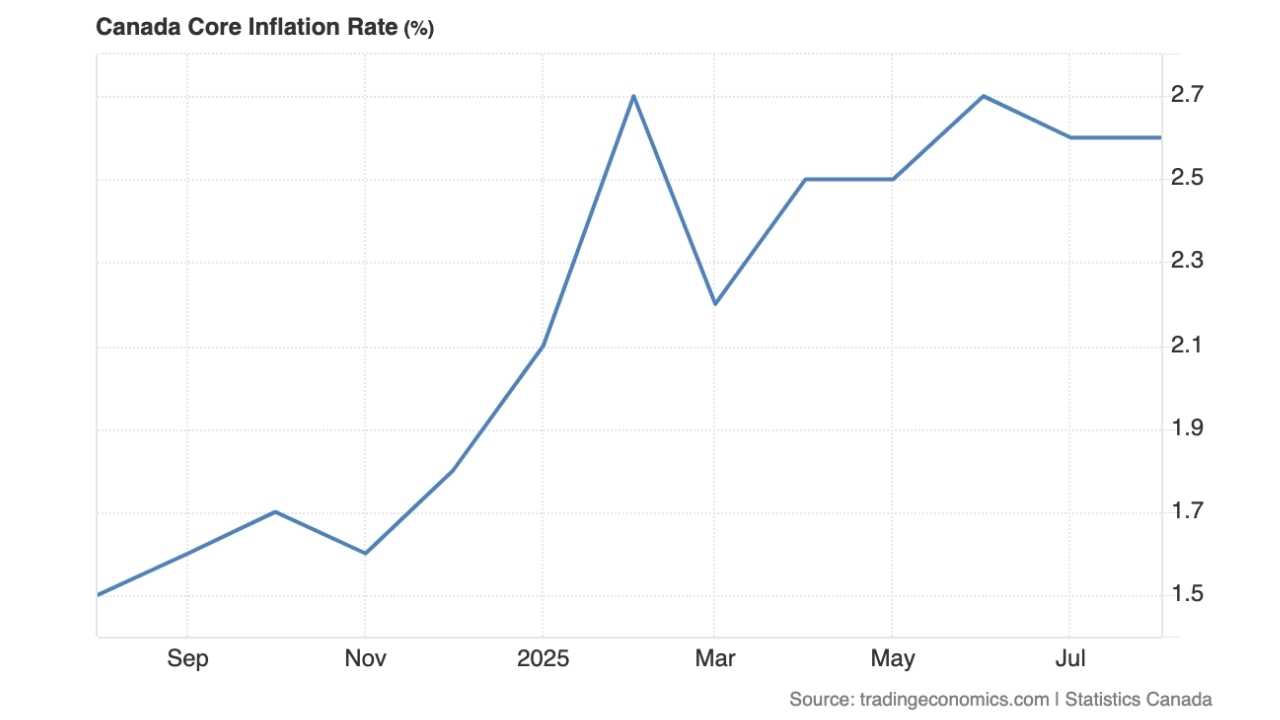
If you’re a homebuyer in Alberta, this could be a window of opportunity. The economy is sluggish, but mortgage affordability is slowly improving. Inflation has cooled from its highs, and analysts expect the Bank of Canada to lower rates by another 0.75% over the coming months.
That doesn’t mean it’s time to rush in blindly — rates can move quickly, and lenders don’t always pass along the full benefit right away. But it does mean there’s room to negotiate. A mortgage broker can help you take advantage of the shifting market, comparing rates from multiple lenders and finding flexible terms that match your financial goals.
Why does a mortgage broker make a difference?
When the market is uncertain — as it is now — having an expert in your corner can make all the difference. Brokers have access to rate sheets and promotions that aren’t always available directly through banks. They also understand how to navigate tighter lending rules and can explain how rate changes affect your qualification and long-term costs.
For Alberta buyers, where regional markets can vary widely, a broker’s insight into local lenders and programs can help you save thousands over the life of your mortgage.
What’s the short version?
Canada’s economy is slowing down, with factories and trade struggling and jobs not growing as fast. That could be good news for Alberta homebuyers because lower interest rates may be coming, which can make mortgages cheaper. Prices for homes and rents are starting to level off, giving buyers a better chance to get a good deal. Working with a mortgage broker can make it easier to compare lenders, find the best rates, and get a mortgage that fits your budget, even with the economy being uncertain. Have questions? Contact me to get no obligation answers!
How an Alberta mortgage broker helps when rates start to fall
Falling bond yields only help if your lender passes them on:
- Compare rate sheets and promotions from multiple lenders, not just your bank’s posted rate.
- Get a pre-approval with a rate hold, then ask for a lower rate if it drops before you close.
- See how a lower rate changes what you qualify for under today’s lending rules.
- Choose flexible terms that fit your plans, not just the lowest number.
- Find a lender when your bank has said no, including self-employed and credit-rebuilding files.
Thinking about buying in Alberta?
Get pre-approved and compare lenders before rates move again.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageQuestions about the economy and mortgage rates
Why does a slowing economy make lower mortgage rates more likely?
What economic news pointed to a slowdown in October 2025?
What are the 4-year swap rate and the 5-year Canada Mortgage Bond yield?
How likely was a Bank of Canada cut on October 29, 2025?
Do lenders pass on lower rates right away?
How can a mortgage broker help Alberta buyers when rates are uncertain?
This article was written in October 2025; interest rates, market data and mortgage rules may have changed since then. It is general information for Alberta homebuyers, not financial, mortgage or legal advice. Rates, products and qualification rules vary by lender. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.


