I’m Josh Tagg, a mortgage broker working with homebuyers and homeowners across Alberta. Lately, a lot of clients have been asking me what’s happening with interest rates and what it means for their mortgage decisions. With the latest forecasts and Bank of Canada (BoC) signals, now is a good time to break it down in plain language so you can plan with confidence.
What is the Bank of Canada’s interest rate outlook for 2026?
Right now, the Bank of Canada’s policy interest rate—the rate that influences borrowing costs like mortgages—is expected to stay unchanged through much of 2026 at 2.25 per cent. That’s what most economists and bank forecasts are telling us based on recent data and central bank messaging.
This means we’re likely at the bottom of the current rate cycle. After several cuts in 2024 and 2025, the BoC is taking a pause instead of moving rates up or down for now.
Why is the Bank of Canada holding rates?
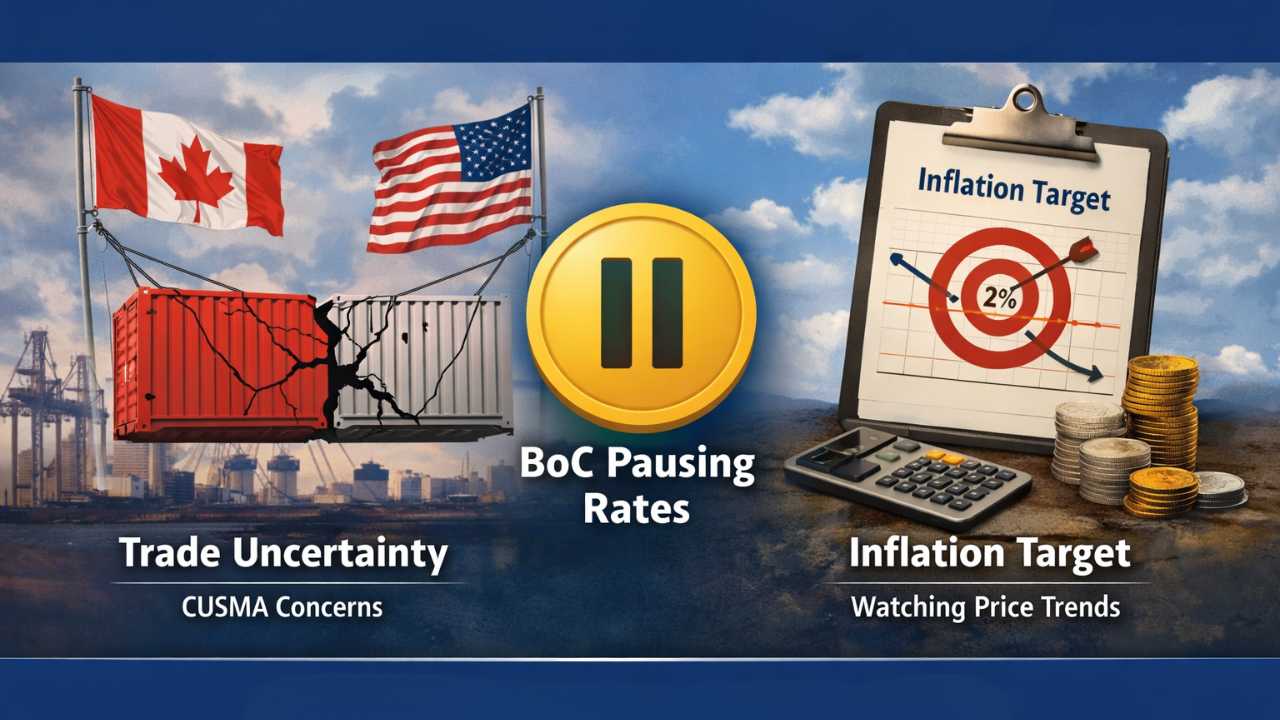
The central bank’s main job is to keep inflation around its target of about two per cent. Recent inflation data suggests that prices are slowing in some key areas, which gives the BoC room to pause.
But there’s a catch: economic uncertainty. Trade tensions—especially uncertainty around Canada’s trade relationship with the United States and the future of the US-Mexico-Canada Agreement (CUSMA)—are weighing on business and consumer confidence. Surveys from the BoC show many firms and households are cautious because of these trade risks.
Because of this uncertainty, policymakers are choosing to watch how things unfold before changing rates. That’s why the upcoming Monetary Policy Report and official BoC statement matter just as much as the rate itself.
What does a rate hold mean for Alberta homeowners and buyers?
If you’re buying a home in Alberta, here’s what the rate outlook generally means:
• Mortgage rates are less likely to jump suddenly in the early part of the year. Most banks expect the policy rate to stay the same through 2026.
• That doesn’t guarantee low rates — just steady ones. Fixed-rate products are priced based on expectations about future rates, so prices today reflect that we’re at a pause.
• For variable-rate mortgages, a stable BoC rate generally keeps those payments more predictable, but markets can still move based on investor expectations.
For homeowners renewing a mortgage in 2026, there’s a chance your payment could be higher than it was when you first signed. As borrowing costs have moved up from the very low rates seen during the pandemic, many fixed-rate renewals reflect that shift. Some forecasts suggest payment increases for five-year fixed-rate holders renewing in 2026 could average around 15–20 per cent compared to older, ultra-low rates.
What should you do next?
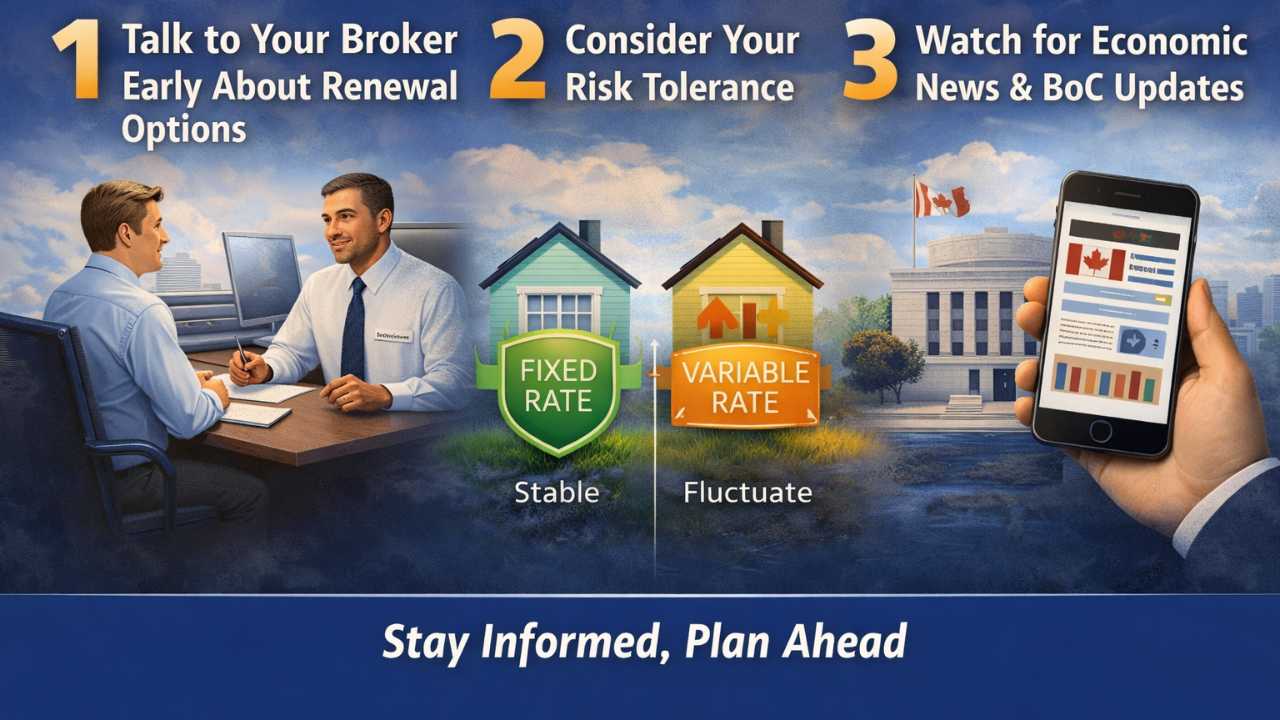
Here are a few practical steps:
Talk to your broker early about renewal options.
If you’re coming up on a renewal, understanding the current market and your lender options can help you choose the right path.Consider your risk tolerance.
Fixed-rate products offer stability, while variable-rate products may have upside if rates stay flat or ease again.Watch for economic news and BoC announcements.
Even though a rate change isn’t expected soon, updates from the BoC can influence mortgage pricing and expectations.
Interest rates are just one part of your mortgage story, but they play a big role in payments and buying power. I’m here to help you understand these shifts and make the choices that fit your goals as an Alberta homeowner or homebuyer. Feel free to reach out if you want to talk mortgage strategy in more detail.
How an Alberta mortgage broker helps while the Bank of Canada is on hold
A pause is a good time to plan rather than wait. Here’s where a broker earns their keep:
- Start your renewal review early, so you see what other lenders offer before your current lender’s renewal letter arrives.
- Lay out fixed versus variable side by side for your payment, your plans and how much movement you can live with.
- Explain how fixed rates are priced off bond-market expectations, not the Bank of Canada rate alone.
- Run the numbers on a higher renewal payment ahead of time, so there’s no surprise at maturity.
- Compare lenders across Alberta, not just the bank you already deal with.
Renewing or buying in 2026?
Get your options in front of you before the next Bank of Canada announcement.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageBank of Canada 2026 outlook: questions Alberta homeowners ask
What was the Bank of Canada’s rate outlook for 2026?
Why was the Bank of Canada holding rates?
Does a Bank of Canada rate hold mean mortgage rates will stay low?
Will my payment go up when I renew my mortgage in 2026?
Should I choose a fixed or variable mortgage while rates are on hold?
What should Alberta homeowners do while the Bank of Canada is on hold?
This article reflects forecasts and Bank of Canada signals as of January 2026 and is general information for Alberta homebuyers and homeowners, not financial, mortgage or legal advice. Rates, forecasts and lender products change; please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.