By Josh Tagg, mortgage broker · Mortgages for Less with INDI Mortgage · Calgary, serving all of Alberta ·
Buying a home is exciting, but it can also be stressful when things don’t go as planned. As a mortgage broker in Alberta, I’ve seen deals fall apart at the last minute, even when buyers thought everything was on track. The good news is that most mortgage issues are preventable with the right preparation and guidance.
I work with first-time home buyers and current homeowners every day, including many clients who are new to Canada. Below are the most common reasons mortgage deals fall apart in Alberta, explained in plain language, and what you can do to avoid them.
1. Why does a change in income or employment sink a mortgage?
One of the biggest reasons mortgage deals fall apart is a change in income or employment after an offer is accepted. In Alberta, this is especially common due to contract work, self-employment, seasonal jobs, and layoffs tied to the energy sector.
Lenders approve mortgages based on your current, stable income. If you switch jobs, reduce hours, move from salary to commission, or start your own business before closing, the lender may no longer approve the mortgage. Even a positive career move can cause problems if it changes how your income is calculated.
Before making any job changes, it’s important to speak with your mortgage broker. I often help clients plan career moves so they don’t accidentally derail their home purchase.
2. How can credit issues discovered late derail a deal?
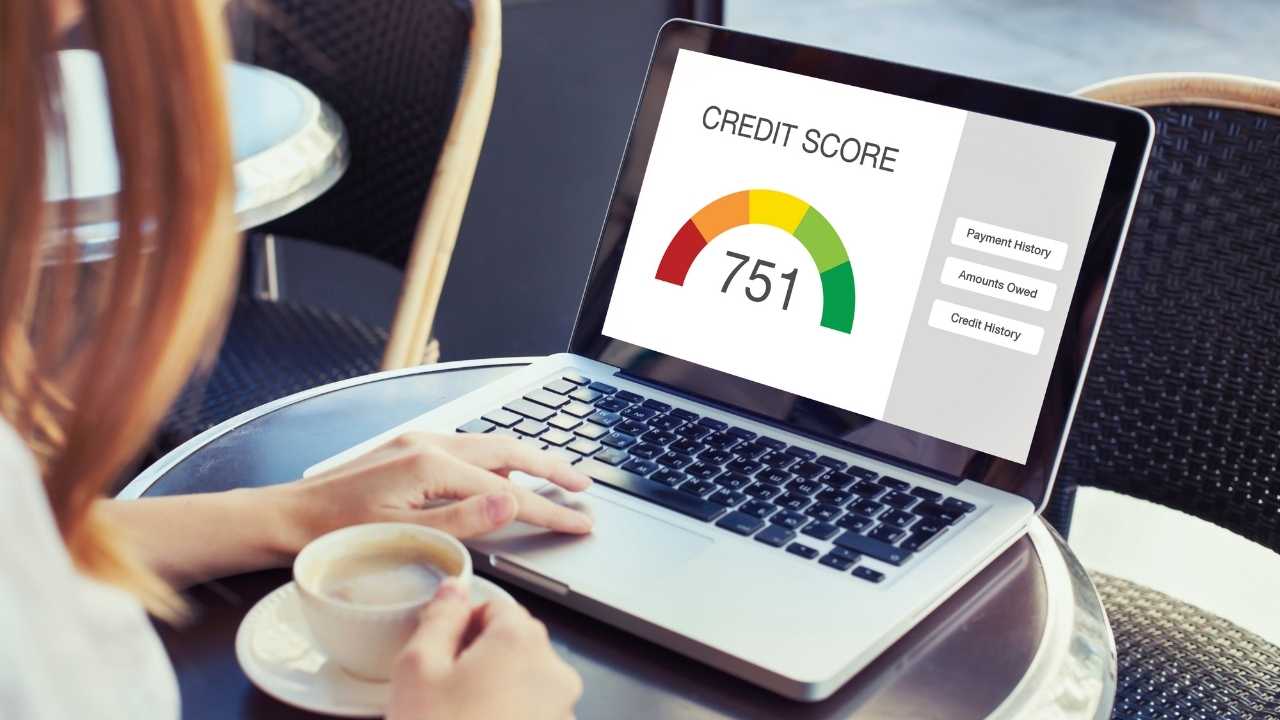
Many buyers assume their credit is “good enough,” but lenders look deeper than just a score. In Alberta, mortgage deals can fall apart when lenders discover missed payments, collections, high credit card balances, or recent new debts.
This can be especially challenging for buyers new to Canada, where credit history may be limited or spread across different institutions. Small issues, like a forgotten phone bill or using too much of a credit limit, can cause a lender to decline or reduce the mortgage amount.
I always recommend reviewing credit early. When I catch issues months or even years ahead of time, we usually have options to fix them before a purchase.
3. Can the property or the appraisal kill a mortgage deal?
Not every home qualifies for every mortgage. In Alberta, deals sometimes fall apart because of property concerns such as older homes, acreage properties, condominiums with weak financials, or homes that don’t appraise at the purchase price.
If the appraisal comes in lower than expected, the lender may reduce the mortgage amount. That means the buyer must bring more cash to closing or renegotiate the price. In some cases, the lender may refuse the property altogether.
This is why it’s important to get pre-approved properly and to understand how property type can affect financing before making an offer.
4. Why does new debt after pre-approval cause problems?
A pre-approval is not a guarantee. It’s based on your financial situation at a specific point in time. Mortgage deals often fall apart when buyers take on new debt after being pre-approved.
Common examples include buying a car, financing furniture, taking out a line of credit, or co-signing a loan for a family member. Even small monthly payments can reduce how much you qualify for or cause the lender to decline the mortgage altogether.
I always advise my clients to pause major financial decisions until after they have the keys.
5. How do missed conditions or timing issues derail a closing?
Real estate transactions in Alberta move quickly. Financing conditions, document deadlines, and closing dates all matter. Deals can fall apart when paperwork is delayed, conditions aren’t met on time, or buyers don’t understand what the lender needs.
Working with a mortgage broker early helps avoid last-minute surprises. My role is to manage timelines, communicate with lenders, and make sure nothing is missed.
How do I help protect your mortgage approval?
Most mortgage problems don’t happen overnight. They build up over time due to lack of planning or unclear advice. I help clients by reviewing income, credit, debts, and property details upfront so there are no surprises later.
Whether you’re buying your first home, renewing your mortgage, or planning to buy in the next few years, having a clear strategy makes a big difference.
If you’re thinking about buying in Alberta and want to avoid having your mortgage deal fall apart, I’m happy to help you plan ahead. Even if you’re not ready today, the right preparation can put you in a strong position when the time comes.
How an Alberta mortgage broker keeps your deal together
Most collapsed deals were fixable weeks earlier. Here’s what that work looks like:
- Review income, credit, debts and the property up front, before you write an offer.
- Plan around job changes, contract, commission or self-employed income so the way a lender calculates it doesn’t change mid-deal.
- Catch credit issues early, including thin or scattered credit for newcomers to Canada.
- Flag property types (older homes, acreages, condos with weak financials) that narrow the lender list.
- Manage conditions, documents and deadlines with the lender so nothing slips before closing.
- Find another lender when your own bank has said no, through a broad panel of banks, monolines and alternative lenders.
Want your approval to hold all the way to closing?
Get your income, credit and property reviewed before you make an offer.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageQuestions Albertans ask about mortgage deals falling apart
Why do mortgage deals fall apart in Alberta?
Can changing jobs before closing cancel my mortgage?
Is a mortgage pre-approval a guarantee?
What happens if the appraisal comes in lower than the purchase price?
Which properties are harder to finance in Alberta?
Can small credit issues really stop a mortgage?
This article is general information for Alberta homebuyers and homeowners, not financial, mortgage or legal advice. Lender policies on income, credit, property types and conditions vary and can change. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.