By Josh Tagg, mortgage broker · Mortgages for Less with INDI Mortgage · Calgary, serving all of Alberta ·
The holiday season is busy, but it’s also a great time to get your finances in order if you’re planning to buy a home next year. Whether you’re a first-time buyer or upgrading, these five year-end financial moves can help you start 2026 on the right foot.
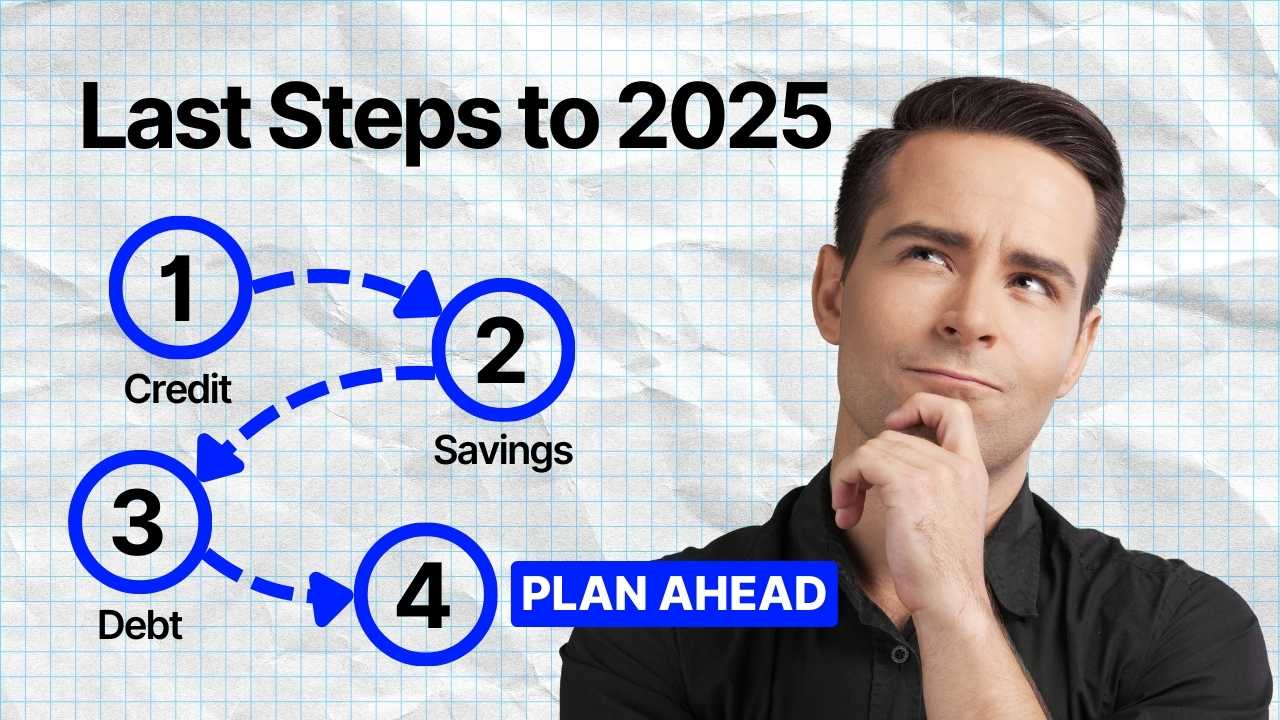
1. Why should you check your credit score before year-end?

Your credit score affects the mortgage rate you’ll qualify for. Take a few minutes to review your report from Equifax or TransUnion. If you spot any errors, correct them before applying for a mortgage—every point counts. People tend to spend a lot of money during the holiday season, but make sure you’re making your payments and keeping your credit in good condition.
2. How can an RRSP, TFSA or FHSA boost your home savings?

Registered Retirement Savings Plans (RRSPs) and Tax-Free Savings Accounts (TFSAs) are great tools to grow your home savings. Contributions to your RRSP before December 31 can give you a tax refund, which you can put toward your down payment. Think of it as a Christmas present to your future!
It’s also smart to set up a dedicated savings account just for your down payment or closing costs. Keeping your savings separate makes it easier to stay on track and avoid dipping into it during the holidays.
If you’re a first-time homebuyer, consider opening a First Home Savings Account (FHSA) before December 31. Canadians who qualify can contribute up to $8,000 per year, and contributions are tax-deductible. By opening an FHSA now, you’ll have an additional $8,000 of contribution room for next year—a simple way to give your down payment a boost. It’s a free Christmas present to yourself!
3. Why pay down high-interest debt before you apply?

High-interest debt, like credit cards or personal loans, can hurt your mortgage application. Paying it down improves your debt-to-income ratio and helps you qualify for better mortgage rates. So if you went over budget on your Christmas list this year, make sure you take care of it before submit your mortgage application.
4. What upfront costs should you plan for?

Buying a home comes with upfront costs like legal fees, home inspections, and moving expenses. Planning for these now ensures you won’t be caught off guard in the new year. Read this blog post to learn more about what these fees might cost.
What’s the short version?
Taking a few simple steps before December 31 can make a big difference in your ability to buy a home. By checking your credit, boosting your savings (including using an FHSA), managing debt, and planning for costs, you’ll start 2026 ready to achieve your homeownership goals. Contact me today to go over your specific details and to craft a plan just for you!
How an Alberta mortgage broker helps you get ready to buy
Year-end prep works best when you know what a lender will look at. Here’s what a broker does with you:
- Review your credit report and flag anything to fix before you apply.
- Plan how your RRSP, TFSA and FHSA savings come together for the down payment.
- Show which debts to pay down first to improve what you qualify for.
- Estimate your closing costs so the cash is ready on possession day.
- Get a pre-approval in place so you know your price range before you shop.
- Find a lender when your own bank has said no, through a broad panel of banks, monolines and alternative lenders.
Planning to buy a home this year?
Get a plan built around your credit, savings and budget before you start shopping.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageQuestions about year-end moves before buying a home
What financial moves should I make before year-end if I want to buy a home?
How do I check my credit score before applying for a mortgage?
How much can I put into a First Home Savings Account?
Can an RRSP contribution help with my down payment?
Should I pay off credit card debt before applying for a mortgage?
What upfront costs come with buying a home?
This article was written for the 2025 year-end; contribution limits, deadlines and rates may have changed since then. It is general information for Alberta homebuyers, not financial, tax, mortgage or legal advice. Rates, products and qualification rules vary by lender and can change. Please speak with a licensed mortgage professional, and a tax professional about registered accounts, about your specific circumstances. Mortgages for Less with INDI Mortgage.