By Josh Tagg, mortgage broker · Mortgages for Less with INDI Mortgage · Calgary, serving all of Alberta ·
The holidays are a wonderful time to celebrate with friends and family, but they can also leave your wallet feeling a little light. As a mortgage broker in Alberta, I often see clients wondering how to bounce back financially after the holiday season. Whether you’re a new homebuyer, a homeowner, or planning to buy in the year ahead, taking a few smart financial steps now can set you up for success in 2026.
Why should you review your holiday spending first?
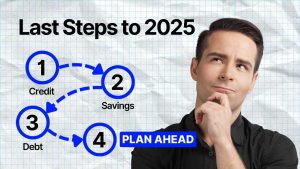
Start by looking at what you spent over the holidays. Take a close look at credit card bills, bank statements, and any other expenses. Knowing exactly where your money went can help you identify areas to cut back in the coming months. If you used credit for gifts or travel, make a plan to pay it down quickly to avoid high interest charges.
How do you update your budget after the holidays?

Now is the perfect time to adjust your monthly budget. Consider all your regular expenses, like mortgage payments, utilities, and groceries, and compare them to your income. If your holiday spending left you short, look for small changes that can free up money for savings. Even simple adjustments, like cooking at home more often or delaying non-essential purchases, can make a difference.
Should you revisit your savings goals in the new year?
If you’re planning to buy a home or make improvements to your current one, your savings goals may need some attention. The start of a new year is a good time to check how much you’ve saved for a down payment, emergency fund, or renovations. Setting clear, realistic goals now makes it easier to stay on track throughout the year.
Is after the holidays a good time to plan a purchase or refinance?
Interest rates and housing market conditions can change quickly. If you’re thinking about buying a home in Alberta or refinancing your current mortgage, reviewing your options after the holidays can give you an advantage. Meeting with a mortgage broker can help you understand your borrowing power, explore current rates, and plan for your next steps.
How do you avoid impulse purchases after the holidays?

Boxing Day sales and post-holiday deals are tempting, but buying on impulse can set back your financial goals. Focus on essentials and planned purchases only. Keeping your long-term financial health in mind will pay off, especially if you’re saving for a home or trying to reduce debt.
Why check your credit after the holidays?
Your credit score is a key factor in mortgage approval and interest rates. Take a moment to check your credit report for errors and pay down any high balances. A healthy credit score can save you money on future borrowing and put you in a stronger position if you plan to buy a home in 2026.
What’s the bottom line on a post-holiday financial reset?
The post-holiday period is a perfect time to reset your finances and focus on your long-term goals. By reviewing your spending, updating your budget, and planning for mortgage opportunities, you can start the year in a strong financial position. If you’re thinking about buying a home in Alberta or want to explore your mortgage options, I’m here to help guide you every step of the way.
How an Alberta mortgage broker helps after the holidays
A new year is a natural checkpoint for your mortgage plans. Here’s what a broker can do with you now:
- Work out your borrowing power from your current income, debts and budget.
- Show how paying down holiday credit card balances changes what you qualify for.
- Set a down payment target and timeline that fits the home you want.
- Review your credit report with you before a lender sees it.
- Compare current rates across lenders for a purchase or a refinance.
- Find a lender when your own bank has said no, through a broad panel of banks, monolines and alternative lenders.
Starting the year with a mortgage plan?
Find out what you can borrow and what to work on before you apply.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageQuestions about resetting your finances after the holidays
What should I do with my finances after the holidays?
How do I review my holiday spending?
How do I adjust my budget if the holidays left me short?
Should I take advantage of Boxing Day and post-holiday sales?
Why does my credit score matter if I plan to buy a home?
When should I talk to a mortgage broker about buying or refinancing?
This article was written for the 2025 holiday season; rates and market conditions have moved since then. It is general information for Alberta homebuyers and homeowners, not financial, mortgage or legal advice. Rates, products and qualification rules vary by lender and can change. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.