
By Josh Tagg, mortgage broker · Mortgages for Less with INDI Mortgage · Calgary, serving all of Alberta ·
I’m Josh Tagg, a mortgage broker here in Alberta. One question I hear a lot from first-time homebuyers — especially people new to Canada — is this: What credit score do you need to buy a house? I’ll explain how credit scores work, why they matter, and what you can do to improve your chances of getting a mortgage in Alberta.
What is a credit score in Canada?
In Canada, credit scores range from about 300 to 900. The higher the score, the more confident lenders feel that you’ll repay your debts on time. This matters because your credit score helps influence whether you get approved for a mortgage and the interest rate you’re offered.
What is the minimum credit score for a mortgage in Alberta?
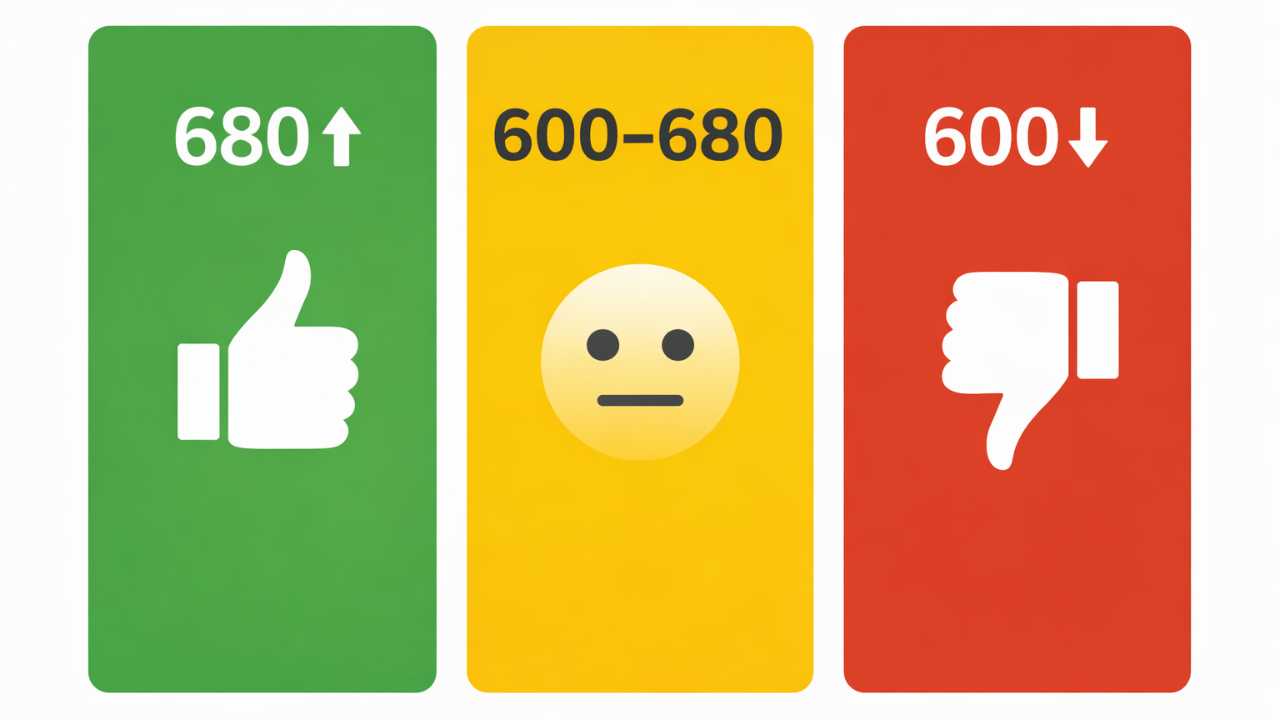
There isn’t one fixed number that all lenders use. Generally:
- 680 and up is considered a strong score for most traditional banks and gives you the best chance at approval with better interest rates.
- 600–680 may still get you approved, especially if other parts of your application (like income and down payment) are strong, but rates could be higher.
- Some alternative lenders may look at scores below 600, but this usually means higher rates and larger down payment requirements.
In practical terms, I tell most of my clients that aiming for at least a 680 credit score gives you the best shot at qualifying for the most competitive mortgages in Alberta.
How does your credit score affect your mortgage rate?
Your credit score doesn’t just help you get approved — it also influences the interest rate you pay. Borrowers with higher scores are typically offered lower rates because lenders see them as lower risk. Scores above about 760 will often qualify for the best rates available.
If your score is lower, you might still get a mortgage, but expect:
- Higher interest rates
- Less flexibility from some lenders
- Potentially larger monthly payments over time
What else do lenders look at besides your credit score?
While credit score is important, it’s just one piece of the mortgage decision:
- Your income and employment stability
- The size of your down payment
- Your debt-to-income ratio
- Results of the mortgage stress test
- Your credit report accuracy
Before applying, it’s a good idea to check your credit report for errors — mistakes could lower your score and hurt your approval chances.
How can you improve your credit score before applying for a mortgage?
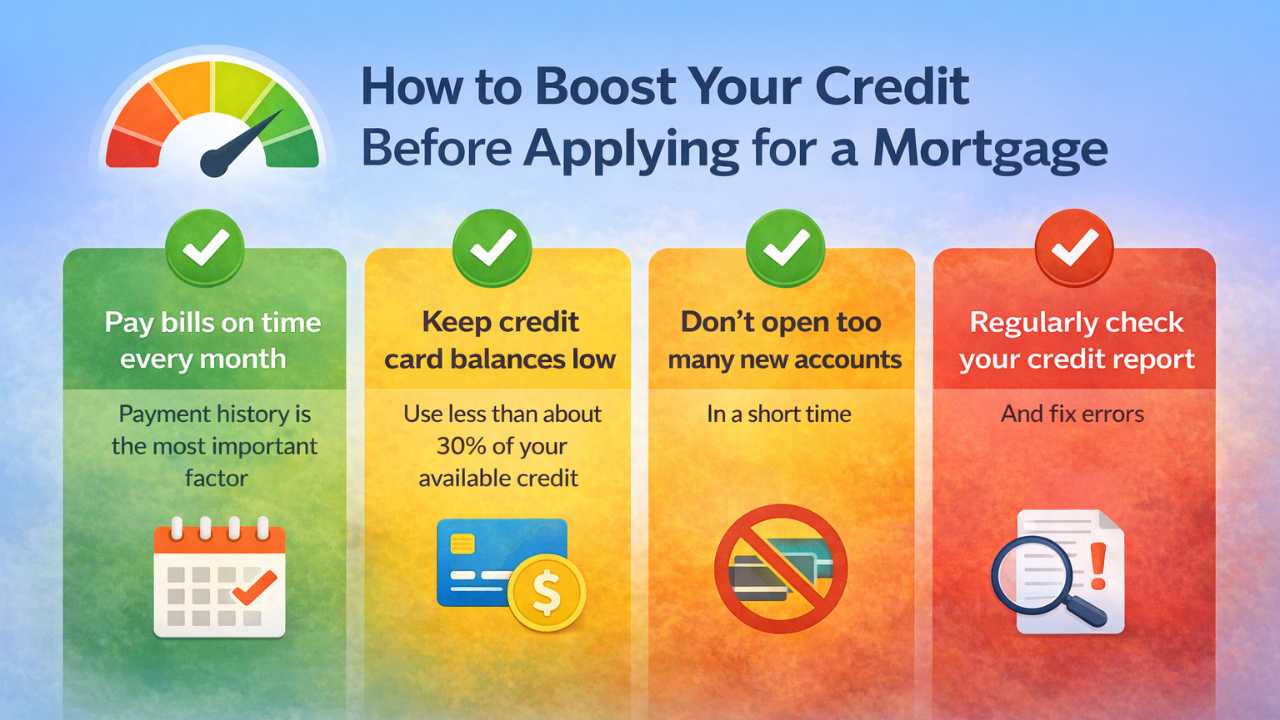
If you want to boost your credit before applying for a mortgage, here are some steps that work well:
- Pay bills on time every month — payment history is the most important factor.
- Keep credit card balances low — use less than about 30% of your available credit.
- Don’t open too many new credit accounts in a short time.
- Regularly check your credit report and fix errors.
Improving your score can take time, but even a modest increase can lower your interest rate and reduce your monthly mortgage payments.
What if your credit score isn’t where you want it to be?
Your credit score is one of the most important numbers in the mortgage process. But it’s not everything — lenders look at your whole financial picture. If your score isn’t where you’d like it to be, don’t worry. With planning and time, you can build it up and improve your mortgage options.
If you have questions about your specific situation or want help figuring out where you stand, reach out. I’m here to help you make sense of the numbers and move confidently toward buying your home in Alberta.
How an Alberta mortgage broker helps when your credit score is on the line
Your score decides which lenders will look at your file and what rate they offer. Here’s where a broker makes the difference:
- Review your credit report with you before you apply, so errors get fixed first rather than showing up as a decline.
- Match your score to the right kind of lender: a traditional bank, or an alternative lender when your score is below what the banks want.
- Look at your whole application — income, down payment, debt ratios and the stress test — since a strong file can offset a middling score.
- Tell you plainly whether to apply now or build your score first, and what to work on in the meantime.
- Help newcomers to Canada who are still building a Canadian credit history understand their options.
Not sure where your credit score leaves you?
Find out which lenders fit your score before you start house hunting.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageCredit score questions Alberta homebuyers ask
What credit score do you need to buy a house in Alberta?
Can I get a mortgage with a credit score between 600 and 680?
Can I get a mortgage with a credit score below 600?
What credit score gets the best mortgage rate?
What do lenders look at besides my credit score?
How can I improve my credit score before applying for a mortgage?
What is the credit score range in Canada?
This article is general information for Alberta homebuyers, not financial, credit, mortgage or legal advice. Credit score thresholds are general guidelines; each lender sets its own criteria, and rates, products and approval depend on your full application. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.


