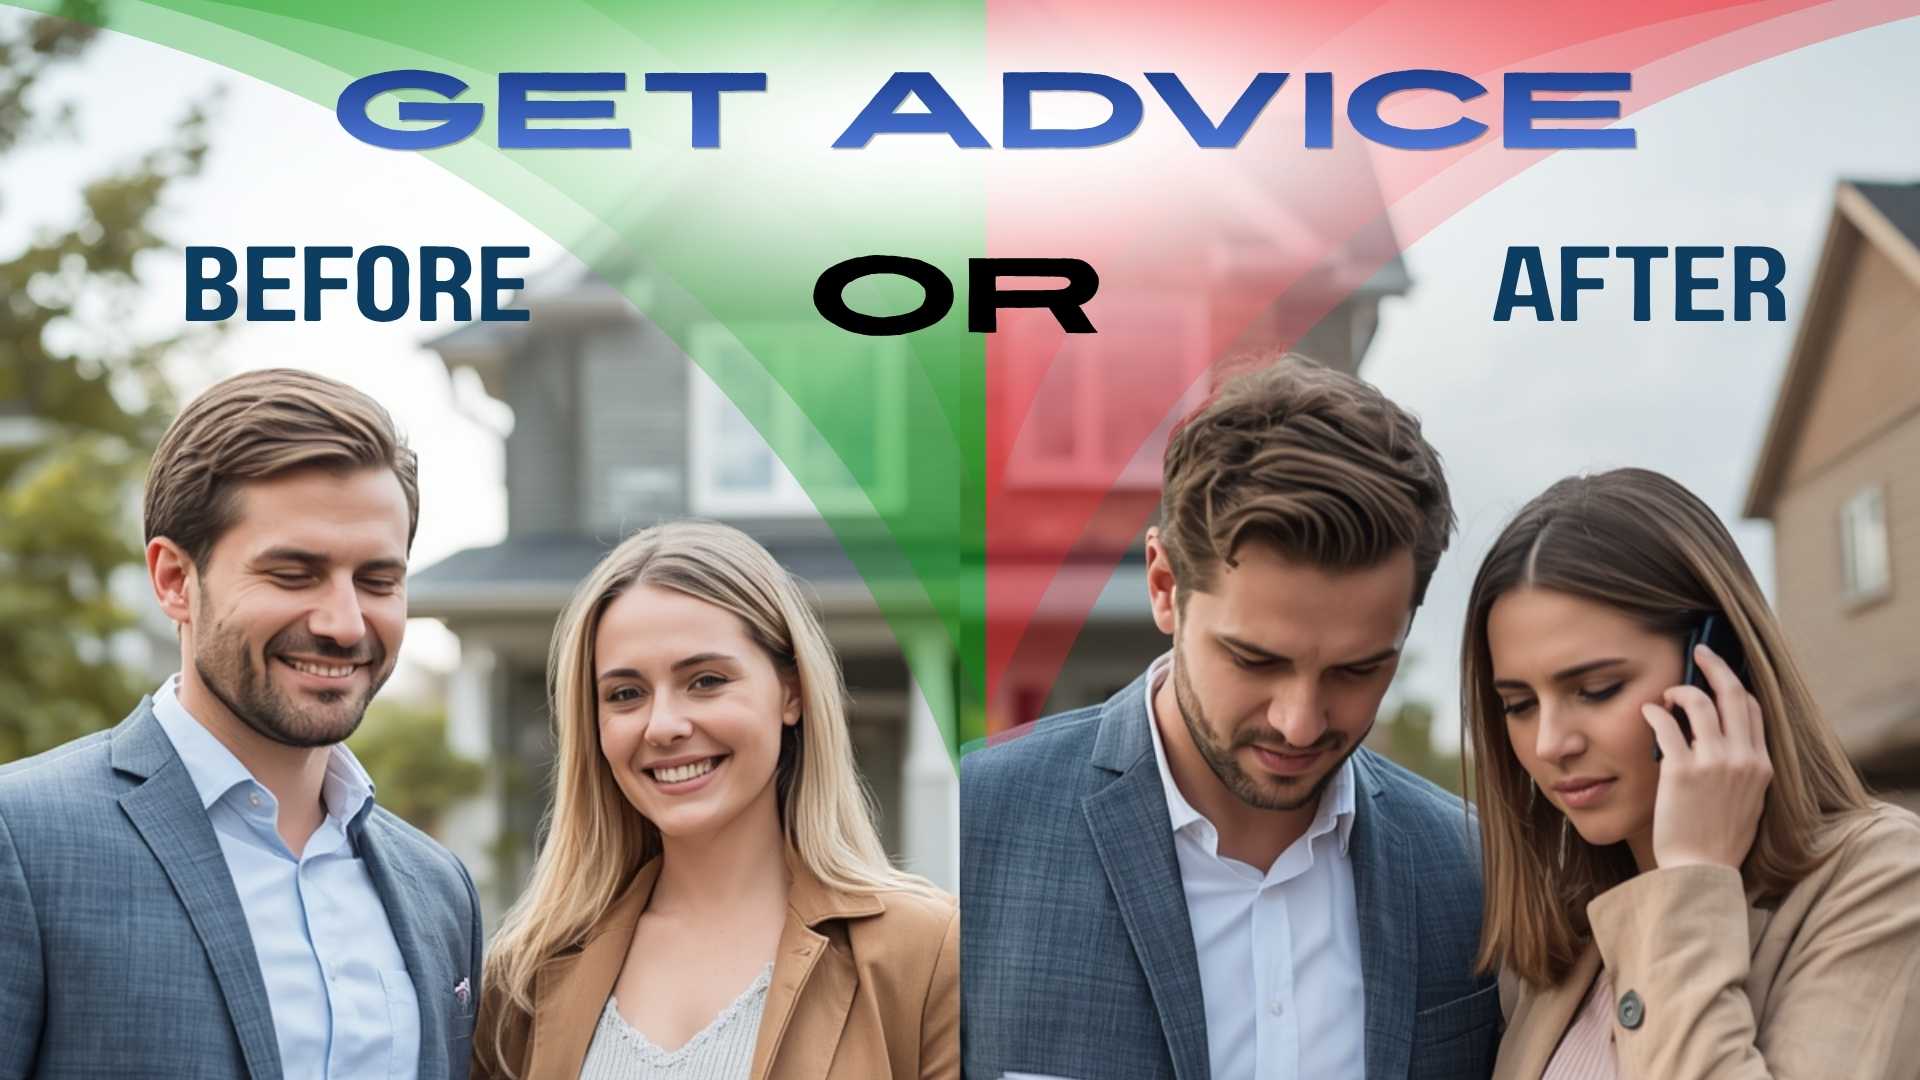
If you’re buying your first home, it can feel like there are a hundred decisions to make all at once. One of which is:
Both approaches happen all the time. But they can lead to very different experiences.
In this article, I’ll walk you through both options with the goal to help you understand which one fits your situation best so you can move forward with confidence.
What happens when you talk to a mortgage broker BEFORE house shopping?

This means you speak with a mortgage broker before you start going out and booking walk-throughs. In most cases, this involves getting a pre-approval.
Here’s how it works:
- You share your income, savings, and debts
- We review your credit and financial picture
- We estimate how much you can afford
- You get a price range and often a pre-approval letter
In this scenario, you know your budget upfront and understand your monthly payments early, allowing you can shop with confidence.
Many first-time buyers want clarity before they start. They don’t want to fall in love with a home they can’t afford. This approach helps avoid surprises.
What happens when you talk to a mortgage broker AFTER house shopping?
This is when you start looking at homes first, and only speak to a mortgage broker once you’re ready to make an offer—or after you already have.
Here’s how it works:
- You browse listings and attend showings
- You find a home you like
- Then you reach out to a broker to arrange financing
In this scenario, since you focus on the home first and financing comes later, timing can end up tighter. Some people want to “see what’s out there” before thinking about financing. Others assume the mortgage step is quick and can be handled later.
What are the pros and cons of each approach?
Advice BEFORE shopping Pros
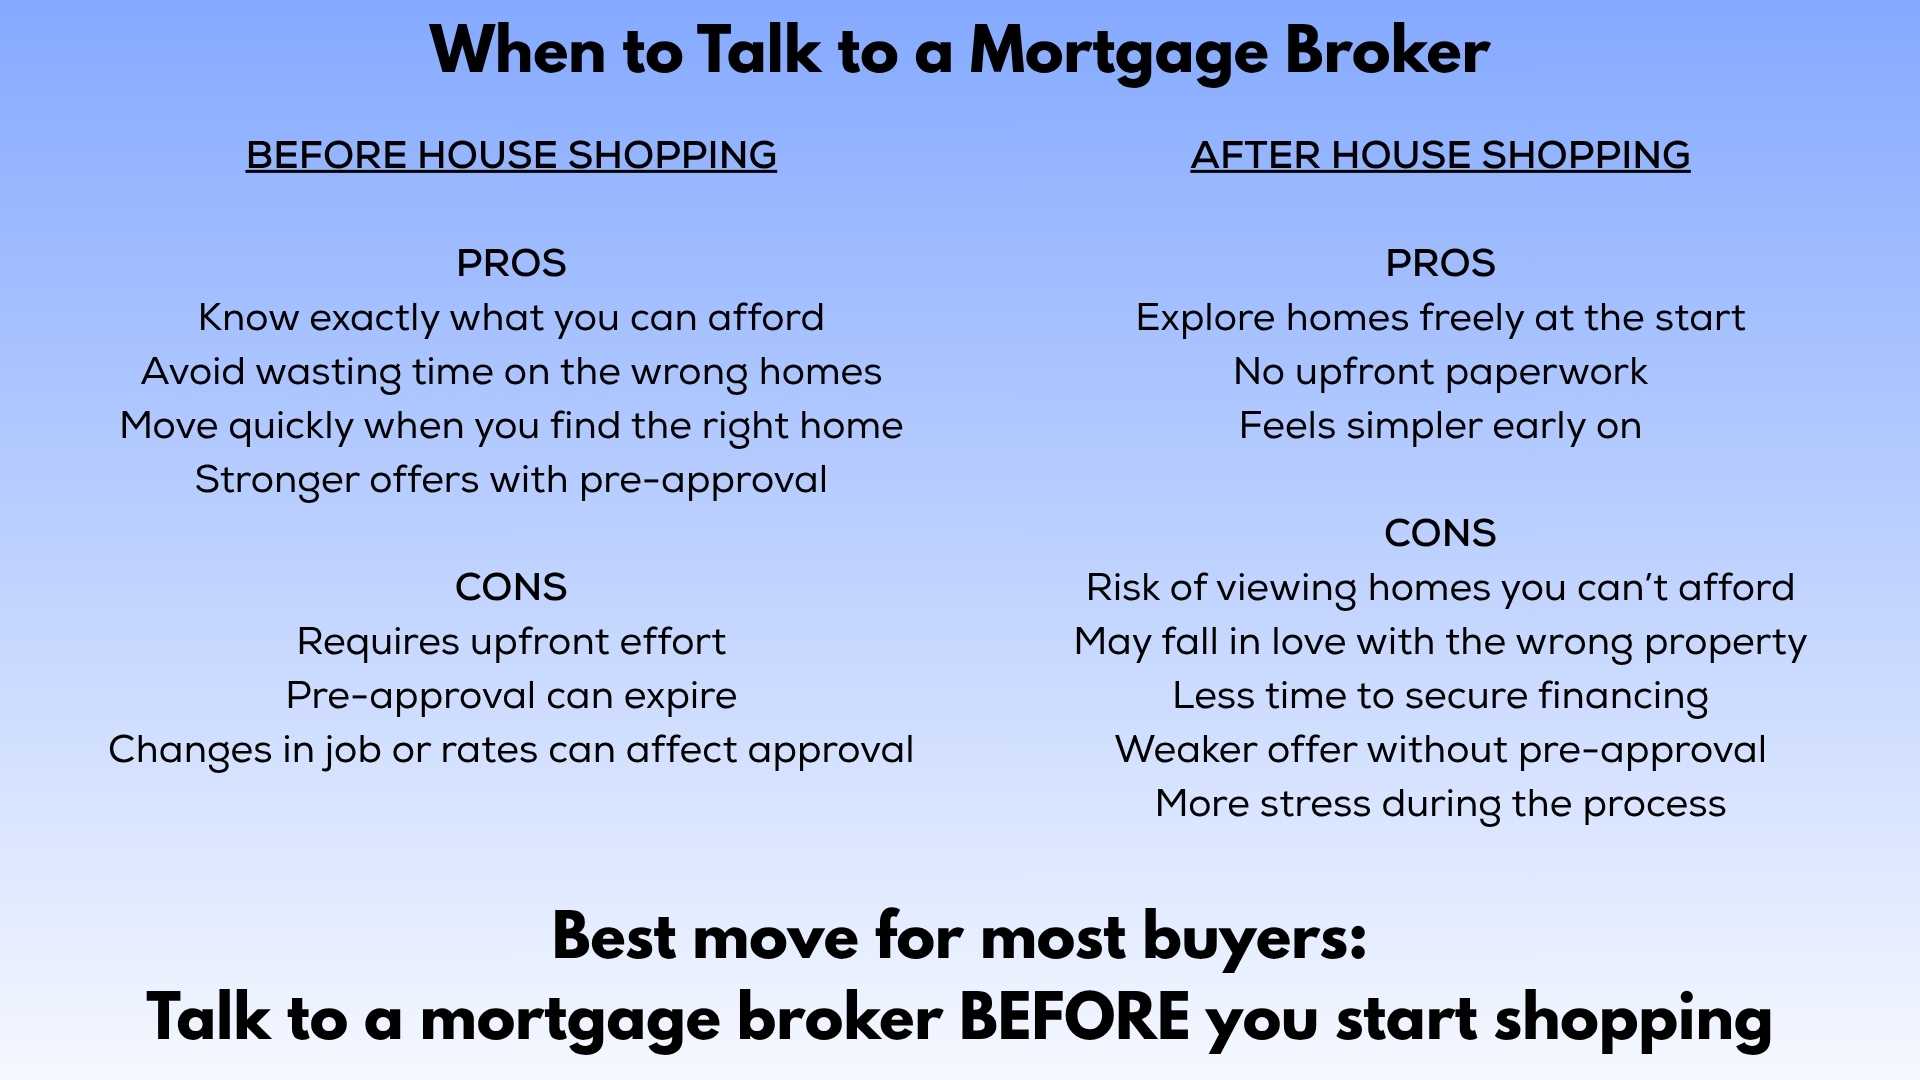
When you talk to a mortgage broker before house shopping, you know exactly what you can afford right from the start and avoid wasting time looking at homes that are outside your budget. You can act quickly when you find the right home because you’ll know what you qualify for and can afford, and sellers will take you more seriously.
Advice BEFORE shopping Cons
Talking with a mortgage broker first does require a bit of upfront effort. Additionally, your pre-approval may expire if you take too long to buy, or it may no longer qualify if you have employment changes or if rates change.
Advice AFTER shopping Pros
You can explore homes freely at the start, there’s no upfront paperwork, and it makes the earlier stages feel simpler.
Advice AFTER shopping Cons
Waiting to talk to a mortgage broker until after you’ve started house hunting may lead you to viewing homes you can’t actually afford so you risk falling in love with a property outside of your budget. Once you do set your heart on a property, you will have less time to secure financing after making an offer, which may be weaker without a pre-approval. All of this can cause higher stress during the purchase process.
Which option is better for first-time buyers?
In most cases, talking to a mortgage broker before house shopping is the better choice. But let’s look at real situations.
When income stability is questionable
If your income varies (self-employed, commission, new to Canada), it’s especially important to talk to a broker early. We can confirm what lenders will actually accept.
When affordability is your main concern
If you’re trying to stay within a tight budget, knowing your numbers upfront is critical. It helps you avoid stretching too far.
When you want flexibility
If you’re just casually browsing and not ready to buy yet, it can be okay to look first. But I still recommend at least a quick conversation so you have a rough idea of your limits.
When the market is competitive
In fast-moving markets, pre-approval gives you a real advantage. You can move quickly and confidently when the right home comes up.
What mistake do many first-time buyers make?
Buyers assume getting a mortgage is quick and easy, so they leave it until the last minute. That may be true from some, but in reality, financing can take time—especially if your situation is even slightly complex.
Things that take time include:
- Income verification
- Down payment sourcing
- Credit checks
- Lender requirements
These can all slow things down. I’ve seen buyers find the perfect home, only to run into stress (or even lose the deal) because they didn’t sort out financing early.
How does a mortgage broker help you decide?
A big part of my job isn’t just finding you a rate. It’s helping you understand your options.
When we talk early, I can help you understand your true price range, estimate your monthly payments, and plan your down payment strategy. All of which allows us to avoid surprises.
If you come to me later in the process, I can still help—but we’re often working under tighter timelines. Either way, the goal is the same: to make sure your mortgage fits your situation, not just the property.
My Advice
In most cases, talking to a mortgage broker before house shopping makes the process smoother, less stressful, and more predictable. It helps you shop with confidence and avoid costly surprises. The best next step is understanding what your mortgage options actually look like. Contact me to find out.
How an Alberta mortgage broker helps before you start house shopping
The early conversation costs you nothing and changes almost everything about how the rest of the purchase goes. Here is what we actually do in it:
- We turn a price range into a real monthly payment, including the costs buyers forget until they are at the lawyer’s office.
- We check your credit and financial picture early, while there is still time to fix anything that would cost you an approval.
- We confirm what lenders will actually accept if your income is self-employed, commission or new to Canada — before it becomes an offer-day problem.
- We sort out down payment sourcing in advance, because proving where the money came from is one of the slowest steps in a file.
- We shop multiple lenders, since what one lender declines another will approve at a competitive rate.
- We get you a pre-approval you can write an offer behind, so a fast-moving market is something you can compete in.
Thinking about house shopping this year?
Have the mortgage conversation first. It takes one short call to know your real budget — and it is the cheapest hour in the whole purchase.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageWhen to talk to a mortgage broker: common questions
Should I talk to a mortgage broker before or after house shopping?
What happens if I talk to a broker before I start looking at homes?
What does talking to a broker after house shopping look like?
Are there downsides to getting pre-approved early?
What can go wrong if I wait until I have found a home?
What if my income is self-employed, commission, or I am new to Canada?
Which parts of getting a mortgage take the longest?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. Lender policies, pre-approval terms and mortgage rates change, and any mortgage is subject to lender approval. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.