I’m Josh Tagg, a mortgage broker here in Alberta. One question I hear a lot from first-time homebuyers — especially people new to Canada — is this: What credit score do you need to buy a house? I’ll explain how credit scores work, why they matter, and what you can do to improve your chances of getting a mortgage in Alberta.
What is a credit score in Canada?
In Canada, credit scores range from about 300 to 900. The higher the score, the more confident lenders feel that you’ll repay your debts on time. This matters because your credit score helps influence whether you get approved for a mortgage and the interest rate you’re offered.
What is the minimum credit score for a mortgage?
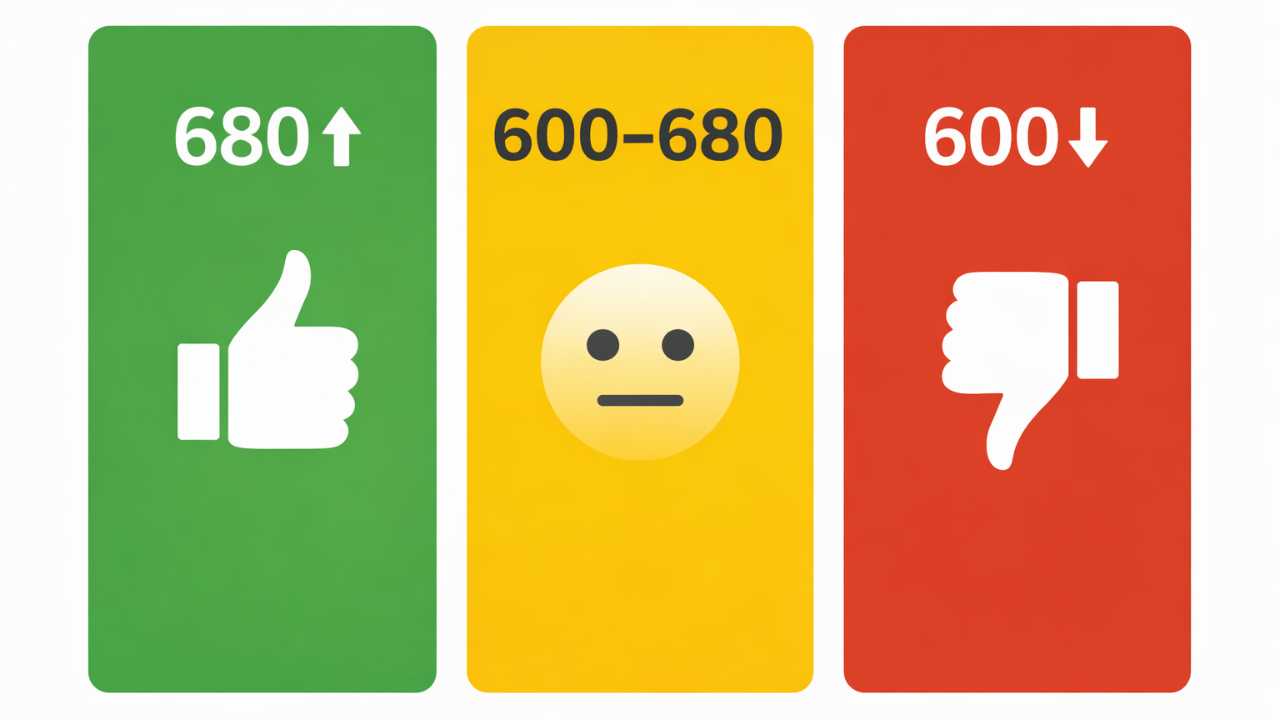
There isn’t one fixed number that all lenders use. Generally:
-
680 and up is considered a strong score for most traditional banks and gives you the best chance at approval with better interest rates.
-
600–680 may still get you approved, especially if other parts of your application (like income and down payment) are strong, but rates could be higher.
-
Some alternative lenders may look at scores below 600, but this usually means higher rates and larger down payment requirements.
In practical terms, I tell most of my clients that aiming for at least a 680 credit score gives you the best shot at qualifying for the most competitive mortgages in Alberta.
How does your credit score affect your mortgage rate?
Your credit score doesn’t just help you get approved — it also influences the interest rate you pay. Borrowers with higher scores are typically offered lower rates because lenders see them as lower risk. Scores above about 760 will often qualify for the best rates available.
If your score is lower, you might still get a mortgage, but expect:
-
Higher interest rates
-
Less flexibility from some lenders
-
Potentially larger monthly payments over time
What else do lenders look at besides your credit score?
While credit score is important, it’s just one piece of the mortgage decision:
-
Your income and employment stability
-
The size of your down payment
-
Your debt-to-income ratio
-
Results of the mortgage stress test
-
Your credit report accuracy
Before applying, it’s a good idea to check your credit report for errors — mistakes could lower your score and hurt your approval chances.
How can you improve your credit score before applying?
If you want to boost your credit before applying for a mortgage, here are some steps that work well:
-
Pay bills on time every month — payment history is the most important factor.
-
Keep credit card balances low — use less than about 30% of your available credit.
-
Don’t open too many new credit accounts in a short time.
-
Regularly check your credit report and fix errors.
Improving your score can take time, but even a modest increase can lower your interest rate and reduce your monthly mortgage payments.
So what is my advice on credit scores?
Your credit score is one of the most important numbers in the mortgage process. But it’s not everything — lenders look at your whole financial picture. If your score isn’t where you’d like it to be, don’t worry. With planning and time, you can build it up and improve your mortgage options.
If you have questions about your specific situation or want help figuring out where you stand, reach out. I’m here to help you make sense of the numbers and move confidently toward buying your home in Alberta.
How an Alberta mortgage broker helps when your credit score is the question
A score is a starting point, not a verdict. Here is what we actually do with it:
- We pull and read the report, not just the number — and check it for the errors that quietly cost people points.
- We match you to the right lender tier, because 680+, 600–680 and below 600 are three different lender conversations, not one.
- We show you what a higher score is worth in dollars on your payment, so you can decide whether waiting is worth it.
- We look at the rest of the file — income and employment stability, down payment size, debt-to-income ratio — which is often what gets a 600–680 file approved.
- We run the mortgage stress test before you shop, so the approval you get is one you can actually use.
- If the score needs work, we build a short repair plan around payment history and balances and tell you roughly when to re-apply.
Not sure where your credit stands?
Let’s look at the real number, the real report, and which Alberta lenders will say yes at that score — before you start house hunting.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageCredit score questions Alberta homebuyers ask
What credit score do you need to buy a house in Alberta?
What is the range of credit scores in Canada?
Can you get a mortgage with a credit score under 680?
What credit score gets the best mortgage rates?
What else do mortgage lenders look at besides credit score?
How can I improve my credit score before applying for a mortgage?
Should I check my credit report before applying?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. Credit score requirements, rates and lender guidelines vary by lender and mortgage product and can change at any time, and any mortgage is subject to lender approval. The score ranges shown are general guidance, not a guarantee of approval. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.