Getting a mortgage approval can feel like the finish line. You submitted the documents, answered a mountain of questions and finally saw the word you were waiting for: approved.
Then your mortgage broker says, “We still have a few conditions to satisfy.”
For first-time homebuyers, that can sound more alarming than it is. Mortgage conditions are a normal part of the approval process. They are simply things the lender needs to verify or receive before they are prepared to fund your mortgage.
What does it mean to be “approved with conditions”?
The lender has reviewed what we’ve told them (how much money you make, what house you want to buy and at what price, etc.) and is willing to lend you the money, provided certain requirements are met. Think of it as the lender saying, “Everything sounds good, now it’s time to prove it.”
Some conditions are extremely simple. Others require documents or changes to your finances before closing.
The important thing is to deal with them early rather than discovering a problem three days before possession when everyone suddenly becomes much more interested in their email inbox.
What kinds of mortgage conditions can a lender ask for?
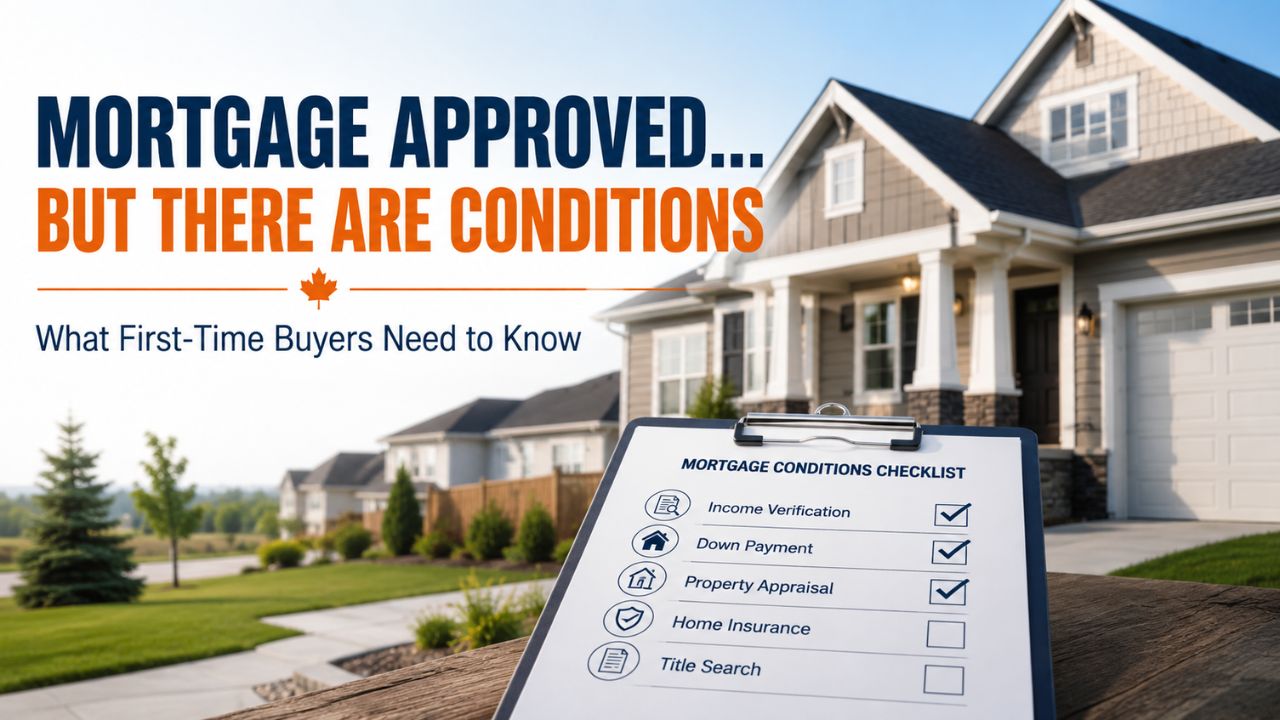
The exact conditions depend on your application, but common examples include:
- Proof of income, such as pay stubs, employment letters or tax returns
- Proof of your down payment and where the money came from
- Bank statements showing that you have enough money for closing costs
- Confirmation that certain debts have been paid
- Proof of home insurance before the mortgage funds
If you’re using gifted money for your down payment, for example, the lender may ask for a signed gift letter and proof that the money has been deposited into your account.
None of this necessarily means something is wrong with your application. Lenders simply have rules about what they need to document. Some of those rules are set by the lender and some are set by the government.
What’s the difference between mortgage conditions and purchase conditions?
This is where terminology can get confusing.
When you make an offer to purchase a home, your Realtor may include conditions for things like financing and an inspection. These allow you time to sort out your mortgage (and back out if you can’t get approved) and to ensure the home is in good condition.
Then, the mortgage lender will also have its own conditions attached to your approval (as listed above.)
Why you shouldn’t make financial changes before closing
Even after your mortgage has been approved, the lender may verify information again before funding.
This is why the period between approval and possession is not the ideal time to finance a new truck, open several credit cards or quit your job to pursue your lifelong dream of becoming a competitive alpaca groomer.
Large purchases, new debts or employment changes can seriously impact your mortgage qualification. If anything about your finances changes before possession, talk to your mortgage broker before assuming it won’t matter.
When are mortgage conditions considered satisfied?
As we collect the required documents, they are sent to the lender for review. Once the lender accepts them, those particular conditions are considered fulfilled. Ideally, we want them satisfied as early as possible.
There may still be routine items that happen closer to closing, such as confirming home insurance or your lawyer completing final mortgage paperwork. That’s normal.
The goal is to avoid having any major unanswered questions hanging over the purchase.
Conditions aren’t something to be afraid of
Seeing a list of mortgage conditions does not mean your mortgage is in trouble. Most of the time, they’re simply the lender’s checklist for turning an approval into a funded mortgage.
As your mortgage broker, part of my job is to explain those conditions, help you gather what the lender needs and identify anything that should concern us before you remove your financing condition.
For a first-time buyer, you shouldn’t have to look at a lender commitment full of banking terminology and figure out on your own which parts are important. That’s what I’m here for.
To get started on a mortgage application or to get some free tailored advice, please send us a message.
How an Alberta mortgage broker helps you clear your conditions
Conditions are far less stressful when someone is managing them with you. Here’s what that looks like:
- We translate the lender’s commitment into plain language, so you know exactly what each condition means.
- We tell you which documents to send and in what form — and chase down anything the lender comes back on.
- We flag anything that could be a problem before you remove your financing condition, not after.
- We keep the file moving so conditions are satisfied early, not in a panic three days before possession.
- We’re your point of contact with the lender, so you don’t have to decode banking jargon on your own.
Have a lender commitment full of conditions? Let’s walk through it together.
Whether you’re just starting your first purchase or staring at a list of conditions you don’t understand, we’ll explain what the lender needs and help you clear it — calmly and early. Start online or book a quick call.
Apply Online → Book a Discovery Call → Serving Calgary, Edmonton & all of Alberta · Mortgages for Less with INDI MortgageMortgage conditions: common questions from first-time buyers
What are mortgage conditions?
Does being “approved with conditions” mean my mortgage is in trouble?
What’s the difference between mortgage conditions and purchase conditions?
Can I buy a car or open a credit card before my mortgage closes?
Do I need home insurance before my mortgage funds?
When are mortgage conditions considered satisfied?
This article is general information for Alberta homebuyers, not financial, mortgage, tax or legal advice. Mortgage conditions, documentation requirements and timelines vary by lender and by individual situation and are subject to change and to lender approval. Please speak with a licensed mortgage professional about your specific circumstances. Mortgages for Less with INDI Mortgage.